


Top-line & Bottom-line Results1
Q4 2024 Revenue: $5.11Bn (exp. $5.04Bn; +1.6% vs. $5.02 in Q4 2023)
Q4 2024 EPS: $1.29 (exp. $1.28; +9.3 vs. $1.18 in Q4 2023)
FY24 Revenue: $20.44Bn (-0.3% vs. $20.5Bn in FY23)
FY24 EPS: $5.12 (+3.4%vs. $4.95 in FY23) – latest FY24 guidance: adjusted diluted EPS in a range of $5.07 to $5.15, representing a growth rate of 2.5% to 4.0% from a base of $4.95 in 2023
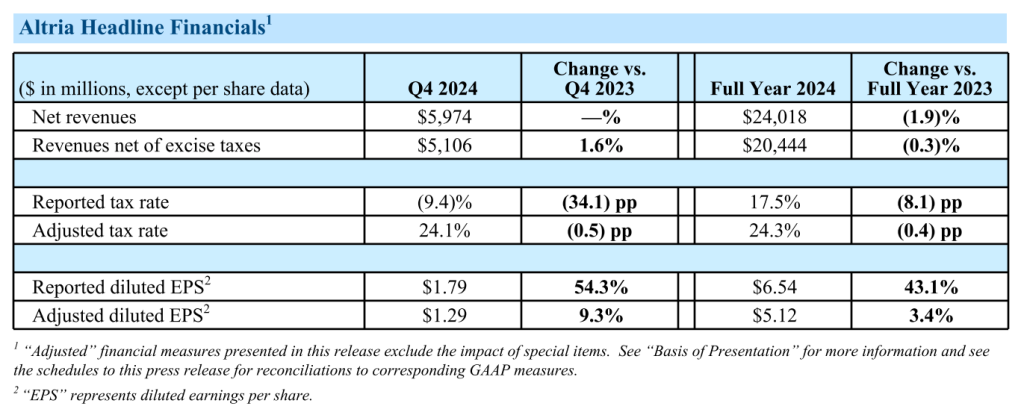
FY25 Guidance: FY25 EPS in a range of $5.22 to $5.37, representing a growth rate of 2% to 5% from $5.12 in 2024
US Nicotine Market
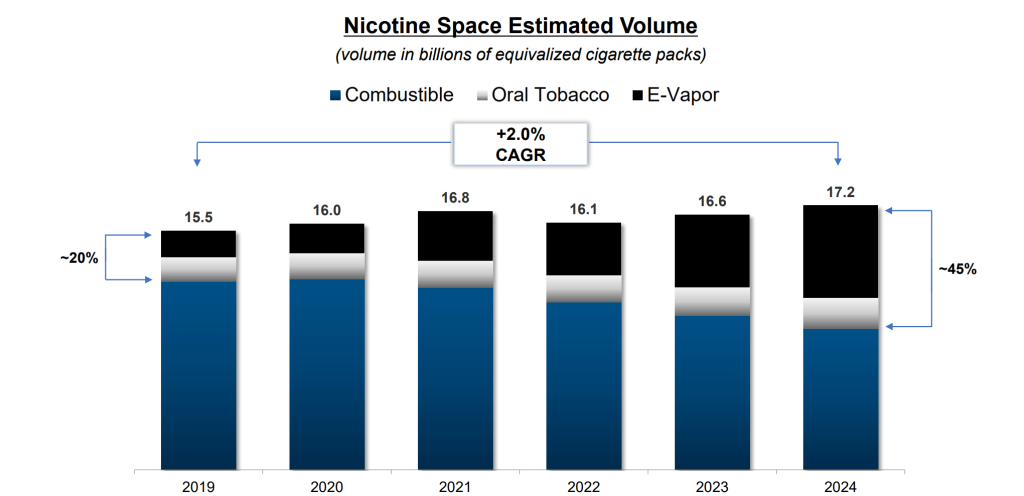
– Annual growth of +2% in the last 5 years (2019-24). +3.6% growth in FY24, driven by the illicit e-vapor products which now represent more than 60% of the e-vapor category volume
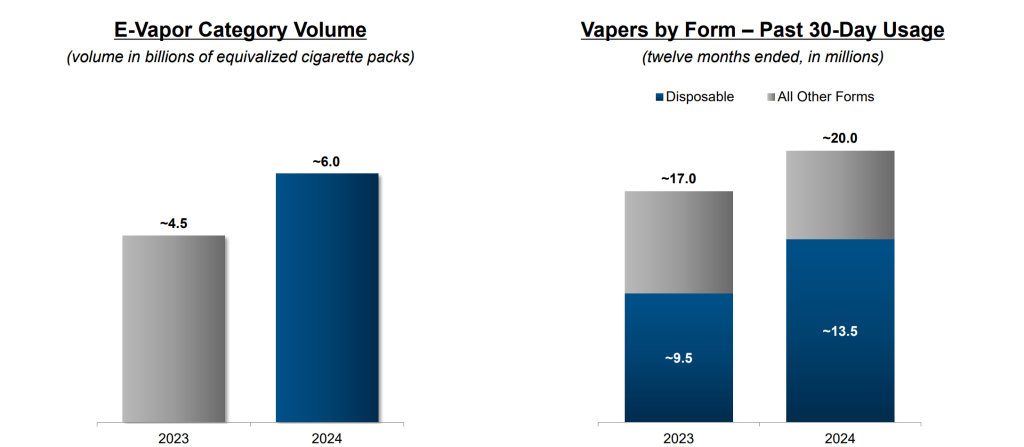
– E-vapor category volume: up +33% from 4.5 billion to 6.0 billion packs equivalent in 2024
– Illicit disposable vapes now represent more than 3.6 billion packs equivalent (i.e. 21% of the overall nicotine consumption in the US)
– 20 million e-vapors in the US (+3 million in one year), 67.5% of which use illicit disposable vapes
Business Segments: Smokable
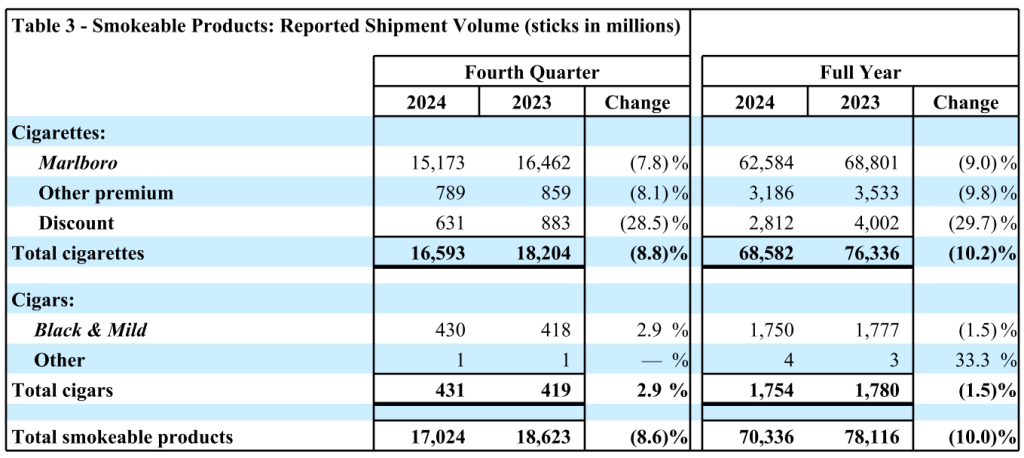
– Cigarette volume down -8.8% in Q4 and -10.2% in FY24, primarily driven by the industry’s decline rate (impacted by macroeconomic pressures and the growth of illicit e-vapor products), trade inventory movements and retail share losses
– Adjusted for calendar differences and trade movements, Altria’s cigarette volume is down -11% in both Q4 and FY24 (industry volume down -8% and -9%, respectively)
– Altria’s cigarette SoM is down -1pp to 45.9% in FY24 although Marlboro held up better at 41.7% (down only -0.5pp). Marlboro’s share in the Premium segment is up +0.4pp to 59.3%
– Discount segment’s share is 30.4% (+1.7pp versus the prior year)
Business Segments: Smokeless
– Smokeless volume is down -0.4% in Q4 and down -1.0% in FY24, primarily driven by retail share losses and trade inventory movements, partially offset by the industry’s growth rate, calendar differences and other factors
– Adjusted for trade movements and calendar differences, Altria’s smokeless volume is flat in Q4 and -2.0% in FY24
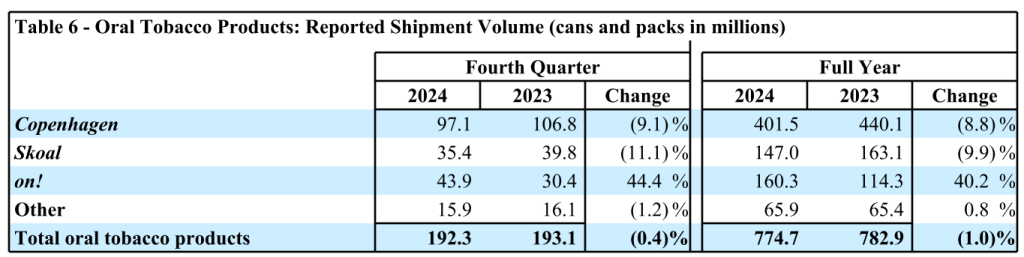
– Total smokeless industry volume increased by +8% over the six months to December 2024, primarily driven by growth in oral nicotine pouches (e.g. ZYN), partially offset by declines in MST volumes (e.g. Copenhagen, Skoal, Grizzly). Altria’s smokeless SoM is down -5.0pp to 37.5% in FY24
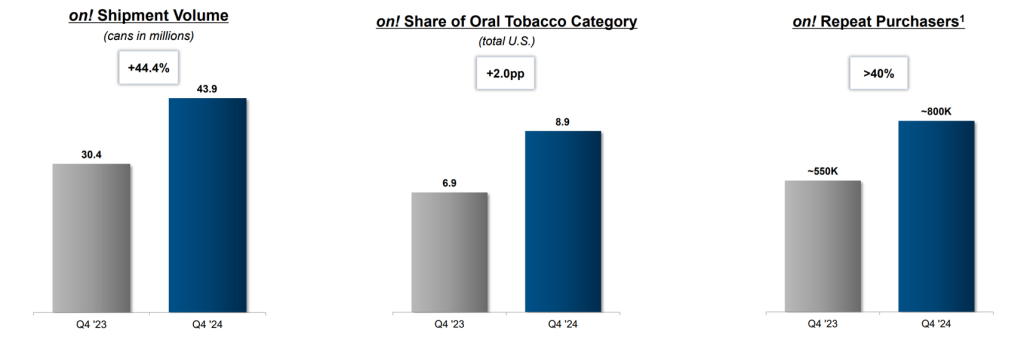
– on! shipment volume is up +44.4% in Q4 2024 and +40.2% in 2024, reaching 8.9% smokeless category share. Altria’s nicotine pouch business (“Helix Innovations”) achieved profitability for the first time in Q4 2024 and will be profitable in FY25
Business Segments: E-vapor
– NJOY consumables volume: +15.3% to 12.8 million units in Q4 2024 (46.6 million units in FY24)
– NJOY device volume: +22.2% to 1.1 million units in Q4 2024 (5.0 million units in FY24)
– NJOY SoM in the tracked channels: consumable +2.8pp to 6.4% in Q4 2024 (5.5% in FY24)
– ITC bans the importation and sale of NJOY ACE, agreeing with JUUL’s infringement claims with respect to the four patents at issue in the case. For further details: Patents Wars
Other Highlights
– Both the 2028 smoke-free volume/revenue targets and NJOY-specific financial targets (established at the time of the acquisition) are to be re-assessed due the current state of illicit markets
– Completed the previously authorized $3.4 billion share repurchase program: 73.5 million shares purchased at an average price of $46.26.
– New $1 billion share repurchase program authorized for 2025
Summary
In terms of the current state of business, there is nothing much to cheer about in Altria’s Q4 2024 disclosures. Fast-declining traditional tobacco market, rampant illicit trade in new nicotine products and NJOY importation ban continue to be the major headaches for Altria. Moreover, the need to re-assess the 2028 smoke-free volume/revenue targets and NJOY-specific financial targets resurfaces the reluctance on Altria’s ability to achieve success in transformation to smoke-free (i.e. by maintaining its market position and profitability).
Nevertheless, we still believe Marlboro has enough gas power to finance Altria’s transformation provided that Altria makes smart investment decisions and achieves a quantum leap in the next 5 years. For further details: Altria: Winds of Change
Further Readings:
References:

