


Top-line & Bottom-line Results1
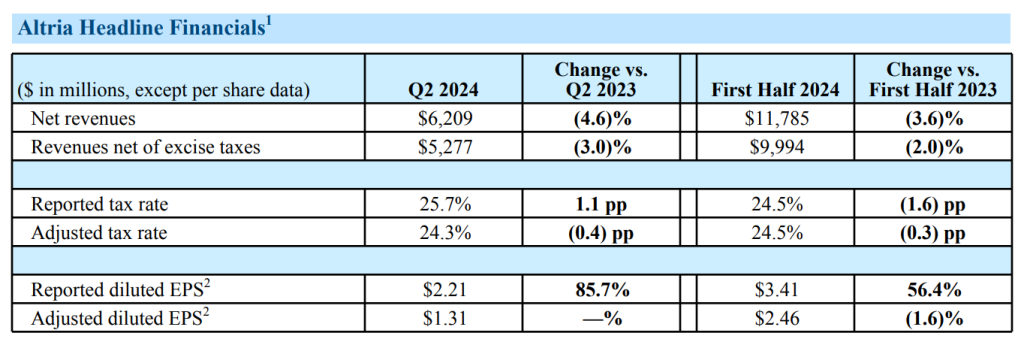
Q2 2024 Revenue: $5.28Bn (exp. $5.39Bn; down -3% from $5.44Bn in Q2 2023)
Q2 2024 EPS: $1.31 (exp. $1.34; flat vs. $1.31 in Q2 2023)
FY24 Guidance:
Narrowed. Adjusted diluted EPS in a range of $5.07 to $5.15, representing a growth rate of 2.5% to 4.0% from a base of $4.95 in 2023 (before: range of $5.05 to $5.17, representing a growth rate of 2% to 4.5%). H2 2024 weighted EPS delivery (i.e. H1 2024 EPS declined by -1.6%)
Business Segments: Smokable
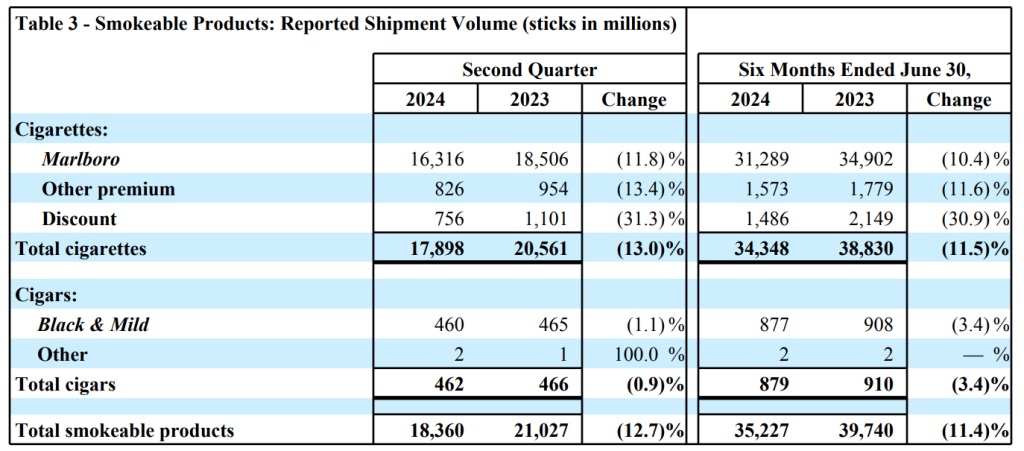
– Cigarette volume down -13% in Q2 and -11.5% in H1 2024, primarily driven by the industry’s decline rate (impacted by macroeconomic pressures and the growth of illicit e-vapor products), trade inventory movements and retail share losses
– Adjusted for trade movements, Altria’s cigarette volume is down -11% in Q2 and -10.5% in H1 2024 (industry volume down -9.5% and -9% in the same period, respectively)
– Altria’s smokable SoM is down -0.7pp to 46.3% in H1 2024 although Marlboro held up well at 42.0% (down only -0.1pp)
– Discount segment’s share is 29.3% (+1.0pp versus the prior year)
Business Segments: Smokeless
– Smokeless volume down -1.8% in Q2 and -2.5% in H1 2024, primarily driven by retail share losses, partially offset by the industry’s growth rate, trade inventory movements and other factors
– Adjusted for trade movements and calendar differences, Altria’s smokeless volume is down -3% in Q2 and -3.5% in H1 2024
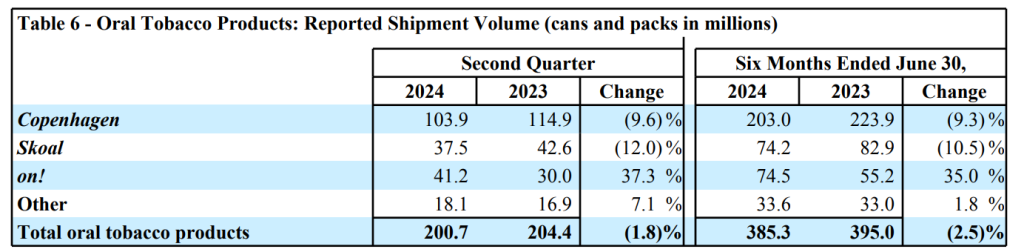
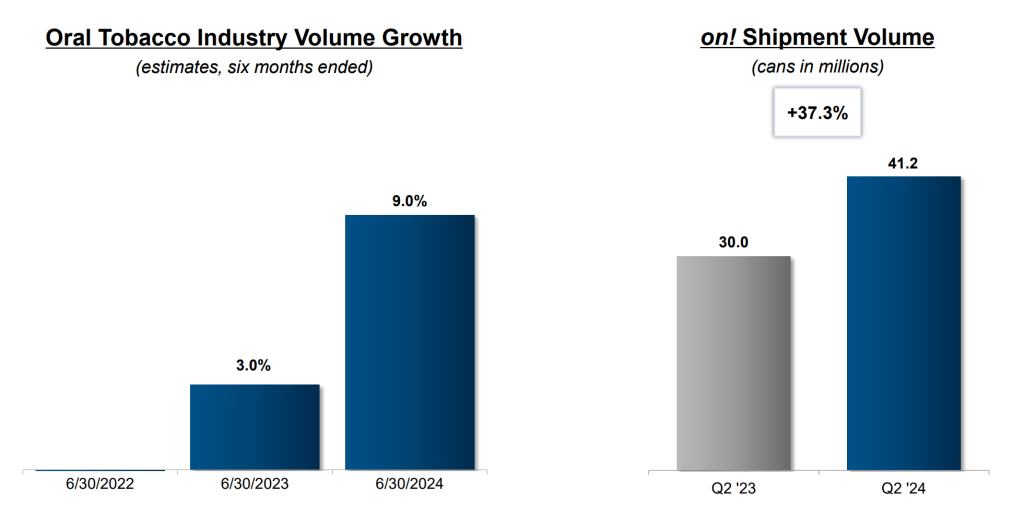
– Total smokeless industry volume increased by +9% in H1 2024, primarily driven by growth in oral nicotine pouches (e.g. ZYN), partially offset by declines in MST volumes (e.g. Copenhagen, Skoal, Grizzly). As a result, Altria’s smokeless SoM is down -6.4pp to 37.9% in H1 2024
– on! shipment volume up +37.3% in Q2 2024, reaching 41.2 million cans (- under-performing ZYN, which is up +50% despite the retail stock-outs)
Business Segments: E-vapor
– NJOY consumables volume: +14.7% sequentially to 12.5 million units in Q2 2024 (23.4 million units in H1 2024)
– NJOY device volume: +80.0% sequentially to 1.8 million units in Q2 2024 (2.8 million units. in H1 2024)
– NJOY SoM in the tracked channels: consumable +1.3pp sequentially to 5.5% in Q2 2024 (4.8% in H1 2024); device +13.8pp to 25.4% in Q2 2024 (note: Altria hopes the device share to be an early indicator of the future consumable share without disclosing any details on the repeat purchase)
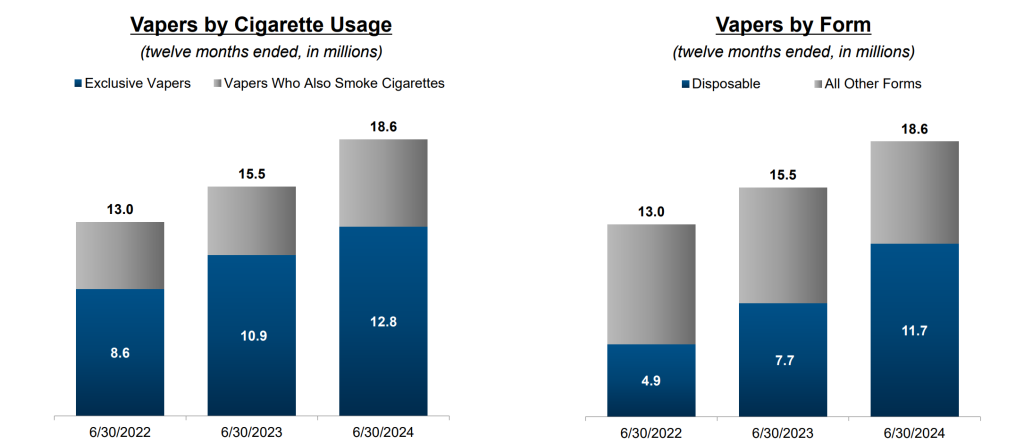
– 18.6 million vapers, up +20% from a year ago: 69% of the vapers don’t smoke and 63% use disposable vapes (vs. ~50% a year ago)
Other Highlights
– 2.1x debt-to-EBITDA ratio as of June 30, 2024.
– Completed the $2.4 billion accelerated share repurchase program (ASRP), which was announced during Q1 2024 (following the ABI stake sale). Under the ASRP, 53.9 million shares are repurchased at an average price of $44.50
– As of June 30, 2024, $990 million remained under the currently authorized $3.4 billion SRP (to be completed by December 31, 2024)
– In June 2024, NJOY received marketing orders from the US FDA for four menthol e-vapor products (first and only menthol e-vapor products authorized). NJOY submitted a supplemental PMTA for the NJOY ACE 2.0 device with access restriction technology designed to prevent underage use. In addition, NJOY resubmitted PMTAs for blueberry and watermelon pods that work exclusively with the 2.0 device
– Helix submitted PMTAs to the FDA for on! PLUS pouches made with “soft-feel” material (3 flavors x 3 nicotine strengths)
Summary
Altria’s Q2 2024 results (“a double miss”) are weak all across the board, reflecting the fundamental challenges of the business: the core cigarette franchise is under immense pressure (i.e. volume down -13%) and PMI’s ZYN continues to eat into Altria’s Smokeless (Copenhagen & Skoal) Kingdom (i.e. smokeless SoM down -6.4pp from a year ago). There is nothing much to cheer about Altria’s current state of business except for the incremental commercial progress achieved in NJOY and the marketing orders received for the NJOY menthol variants.
Further Readings:
References:

