


Release date: October 26, 2023 (before the opening bell)
Sell-side analyst expectations
Revenue: $5.43Bn (up +0.3% vs. Q3 2022)
EPS: $1.29 (up +1% vs. Q3 2022)
FY23 Guidance
Altria re-affirmed its updated FY23 guidance during the Q2 2023 Earnings release (August 1, 2023): “FY23 adjusted diluted EPS in a range of $4.89 to $5.03 – representing a growth of 1% to 4% from $4.84 in 2022”. Altria reported $2.50 adj. EPS in the first half of 2023; thereby, the guidance corresponds to $2.39 – $2.53 (mid-point: $2.46) EPS in the second half – implying no growth vs. H2 2022 ($2.46). This is, primarily, as a result of planned investments (marketing activities) to support the NJOY ACE commercial plans in the second half of 2023.
What to watch out for?
(1) Cigarette volume decline: Altria’s adjusted cigarette volume decreased by 10.5% in H1 2023 in a market that declined by 8% (adjusted: corrected for trade inventory movements, calendar differences and other factors). Thereby, Altria’s SoM declined by 1.2pp (to 47.0%) despite Marlboro’s increasing share in the premium segment. Since Q2 2021 (in two years), Altria’s 12-month rolling cigarette volume is down almost 20Bn/-20%. Accordingly, Altria’s 12-months rolling (total) revenue is flat at $18.1Bn (+/-$0.1Bn) in this period. Recall: Cigarettes have more than 80% weight in Altria’s total revenue.
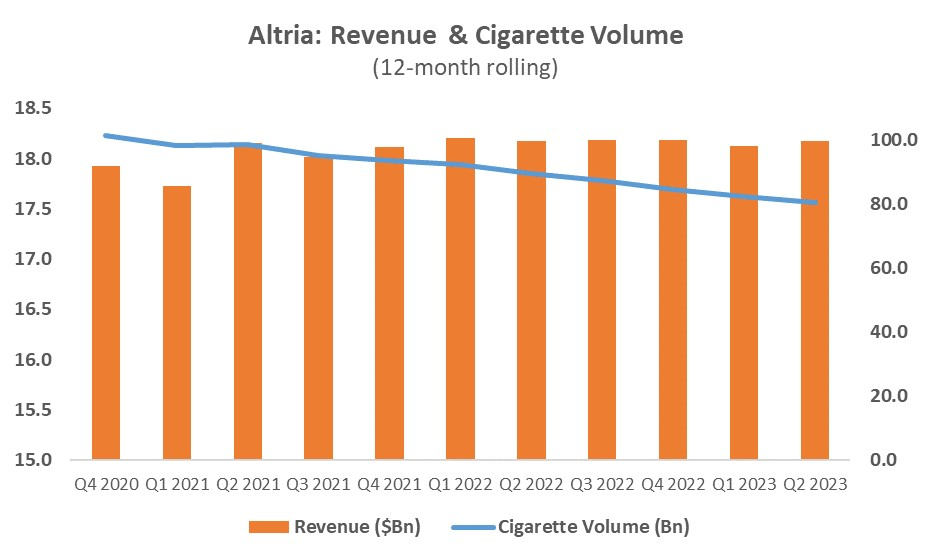
Altria increased the cigarette list prices for the 4th time this year in October. More-than-usual price hikes could mean that the volume pressure is ongoing and Altria is in need of exploiting the consumer price elasticities to the maximum through RGM (i.e. higher prices all across, selectively reduced through promotions at the regional or retail chain/store level). Market would like to see a meaningful softening in the volume decline trend (- seems unlikely).
(2) Smokeless performance: on! has been a remarkable growth engine for Altria – with 43% volume increase in H1 2023, reaching 6.7% smokeless category share (+2.2pp). However, there are still two major issues: (1) on! growth fails to compensate for the volume losses of Copenhagen and Skoal (Altria’s overall category share is down 2.3pp in H1 2023); (2) on! is sold at a major discount to ZYN; thereby, its profit contribution is nowhere as “stellar” as ZYN’s. Market would appreciate more product-level disclosure on on!.
(3) Update on NJOY’s commercial plan: distribution expansion, consumer off-take & repeat purchase, overall share progression and share in specific cross-sections.
Further Readings:

