


Ahead of H1 2025 Earnings release
Release date: July 31, 2025 (before the opening bell)
Revenue: £12.0 billion (-2.7% reported, +1.2% at constant currency)
EPS: £1.548 (-2.9% reported, +1.3% at constant currency)
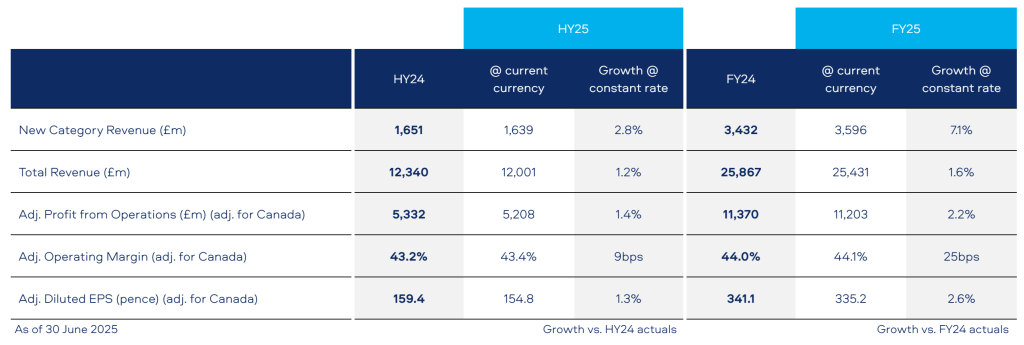
Latest guidance: 1%-2% revenue growth and 1.5%-2.5% adjusted operating profit growth at constant rates in FY25. Similar revenue growth in H1 2025 and FY25. Operating profit growth H2 2025 weighted
H1 2025 Results
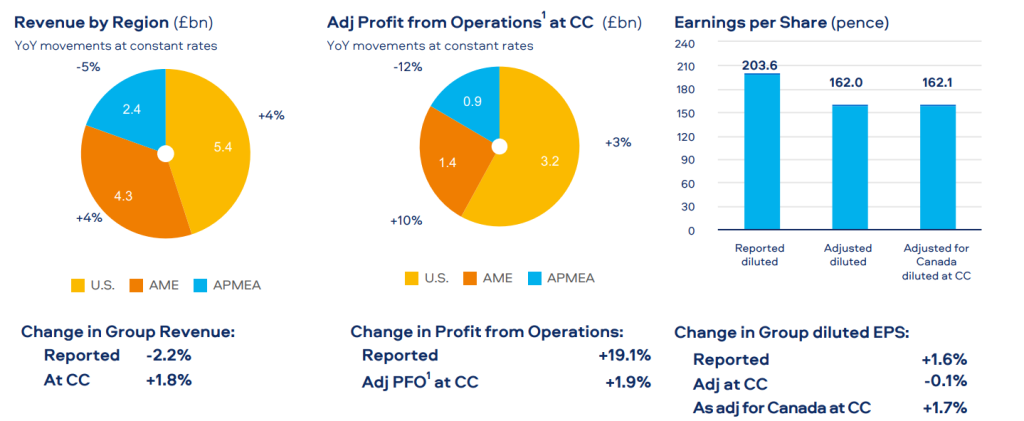
– Revenue: £12.07Bn (vs. £12.0Bn exp.; up +1.8% adj.) => a return to growth in the U.S. (led by combustibles and Velo Plus), continued growth in AME, partly offset by APMEA
– Revenue from New Categories: £1.65Bn (vs. £1.39Bn exp.; up +2.4%); Revenue from New Categories: 13.7% of total; New Category contribution: up +38.6% to £179 million at constant FX (further improvement expected in H2 2025)
– Revenue from Smokeless products (including traditional); 18.2% of total (+up 70 bps vs. FY24); 30.5 million smokeless consumers (+1.4 million)
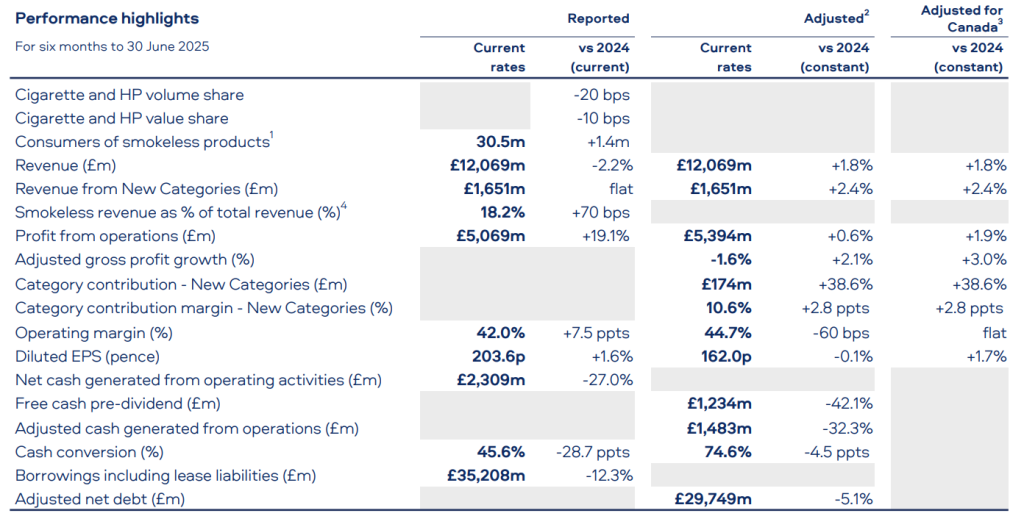
– Adj. Operating Profit: £5.39n (vs. £5.21Bn exp.; up +1.9%)
– Adj. Operating Margin: 44.7% (vs. 43.4% exp.; flat)
– Adj. EPS: £1.62 (vs. £1.548 exp., up +1.7%)
– Already at the low-end of the mid-term growth target (i.e. 3% revenue growth, 4.5% operating profit growth) if the headwinds in Australia and Bangladesh are excluded
Key Financial Highlights
– H1 performance is slightly ahead of expectations; On track for FY25 Guidance led by the U.S. and Velo’s global growth
– Both U.S. revenue and profit up for the first time since 2022; U.S. combustibles volume and value share performance returned to growth. Strong performance in AME while APMEA performance negatively impacted by fiscal and regulatory challenges in Bangladesh and Australia
– Phased roll-out of innovations is expected to drive an accelerated H2 New Category performance; New Categories contribution margin increased by +2.8 ppts to 10.6% at constant FX
– Improved combustibles financial performance (at constant FX), driven by price/mix
– 2025 share buy-back program: £1.1 billion (increased by £200 million as per the previous communication)
– Fit2Win Productivity Program: c.£500m annualised savings by end 2028 (£500m one-off cost; £350m of which is an adjusting factor)
FY25 Guidance
– Revenue growth at the top end of 1.0%-2.0% guidance range, with mid-single digit New Category revenue growth
– 1.5-2.5% adjusted operating profit growth including an expected c.1.0-1.5% transactional
FX headwind; Translational FX headwind of c.4% (half of which is due to weakening $/£ rate)
– Global tobacco industry volume: down c.2%
– Net finance costs: c.£1.8 billion (adj. for Canada), subject to interest rate volatility
– Gross CAPEX: £650 million
– Operating cash flow conversion: more than 90%
– Leverage: continue to deleverage to 2.0-2.5x adjusted net debt/adjusted EBITDA (adj. for Canada) corridor by 2026
Key Highlights – Product Categories:
– Combustibles: Cigarette volume down -8.7% to 229 billion as volume growth in Brazil and Turkey was more than offset by lower volume in a number of markets, mainly driven by Bangladesh, the U.S. and Poland and market exits (including Mali). Volume and value share down 10 bps, growth in the U.S. more than offset by AME and APMEA. On an organic basis, U.S. revenue increased +3.8%, as price/mix (+11.4%) more than offset a 7.6% reduction in volume (industry volume decline: 8.3%). In AME, higher revenue (up +2.8%) driven by higher volume and pricing in both Brazil and Turkey. Combined with robust pricing in Romania and Poland to more than offset a reduction in revenue in Canada. In APMEA, lower revenue (-7.9%) due to fiscal and regulatory headwinds in Australia and Bangladesh, which more than offset higher revenue in the remainder of the region, notably in Pakistan, Nigeria and Indonesia
– Vapor: Continued value share leadership (in tracked channels) despite flat performance. Vapor revenue down -13.0% (at constant rates), with volume down -12.9%, impacted by illicit products in the U.S. and Canada and evolving market dynamics (UK and France). U.S. value share at 49.5% (-20bps). Vapor discountinued in a number of markets (including Malaysia, Japan and Saudi Arabia). Vuse Ultra, new premium product, to be further rolled out in H2 2025, with expected acceleration in vapor revenue.
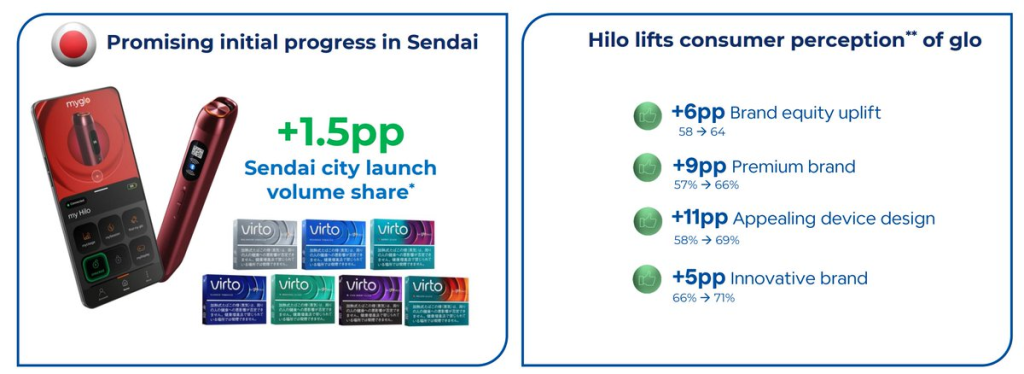
– Heated Tobacco: Revenue up +3.1%, driven by focus in largest profit pools. Volume share down -70 bps, impacted by competitive pressure in Japan and phase-out of legacy super-slims consumables. glo Hilo to be launched in key markets in H2 2025, with expected acceleration in revenue. glo Hilo offers superior heating technology and an integrated display combined with a new consumables range, Virto and tobacco-free Rivo. Pilot of glo HILO in Sendai, Japan: +1.5pp improvement in volume share in 5 weeks, improved perception in terms of brand/product equity. Targeted roll-out in H2 2025. BAT is looking for a turnaround in the key Japanese heated tobacco market (i.e. share down 1pp to 16.8% in H1 2025 vs. FY24)
– Modern Oral: Revenue up +40.6%. Volume up +42.2%. Volume share up 4.4pp. Leadership maintained, with strong financial performances in Scandinavia and the UK. Triple-digit volume and revenue growth in the U.S. following the national roll-out of Velo Plus. Velo category volume share almost doubled to 13.2% (+6.8 pp) in the U.S.
– Traditional Oral: Volume down -10.4% to 2.8 billion sticks equivalents. Revenue flat. U.S. accounts for 96% of the category revenue; revenue down -0.4%, as price/mix (+9.1%) was more than offset by lower volume (down -9.5%) in the U.S. due to the continued cross-category use of Modern Oral.
– Beyond Nicotine: 29 investments since 2020 by Btomorrow Ventures. Exploration in the Wellbeing and Stimulation category with Ryde: functional shots now selling in the U.S. on Amazon and in Texas retailers in addition to Australia and Canada.
Key Highlights – the US Market (56.3% of the total operating profit):
– Revenue up +3.7% to £5,575 million. Operating profit up +3.2% to £3,150. Operating margin down 30bps to 56.5%
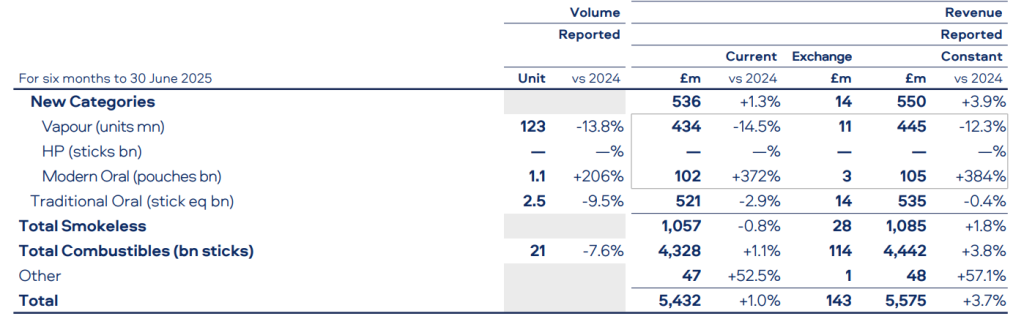
– Combustibles: Revenue up +3.8%, as price/mix (+11.4%) more than offset a 7.6% reduction in volume (industry volume decline: -8%). Volume share up +10 bps and value share up +20 bps
– Vapor: Leadership in value share (closed-system consumables in tracked channels) despite a decline in value share of 20 bps to 49.5%. Revenue down -12.3%, as price/mix (+1.5%) was more than offset by a 13.8% decline in consumables volume mainly due to the continued impact of illicit single-use vapes which is estimated to be more than 50% of the total vape market. Early evidence of a more proactive Federal approach to illicit vapes: c.40% reduction in vape shipments to the U.S. and some key illicit brands are in short supply
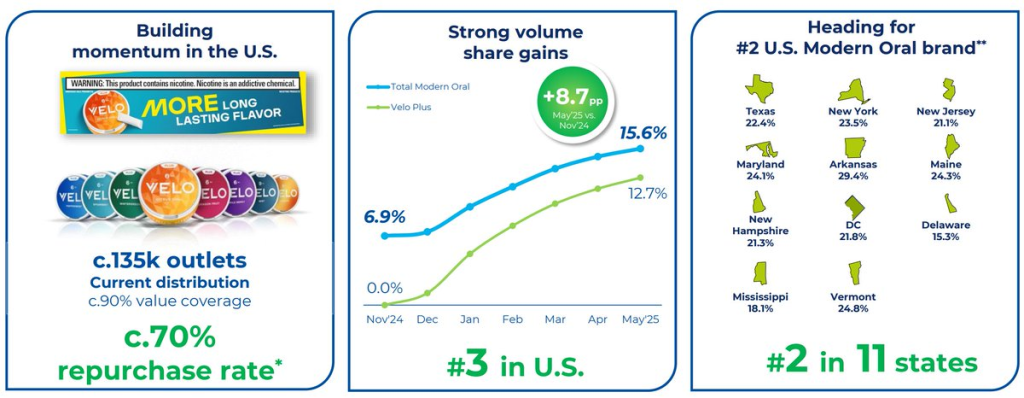
– Modern Oral: Revenue up +384%, driven by higher volume (up +206%) following the successful national roll-out of Velo Plus. Velo category volume share almost doubling, up +6.8 pp to 13.2%. VELO is on track to become #2 in the nicotine pouch category in the U.S. (overtaking Altria’s on!): already #2 in 11 States, 15.6% volume share in May 2025 (12.7% Velo Plus), Velo Plus available in 135k stores (90% weighted distribution), 70% repurchase rate (positive category contribution in first year of launch). Latest reading: 17% category share in the U.S. in July 2025. Progressively reducing the VELO promotional activity in the U.S. following the product trial generation phase. VELO is already sold at a premium to the average category price, ex-ZYN
– Traditional Oral: Revenue down -0.4%, as price/mix (+9.1%) was more than offset by lower volume (down 9.5%) due to the continued cross-category use of Modern Oral.
Our take:
In general, BAT’s H1 2025 results are slighly better than expected thanks to a strong operational performance under challenging market conditions. Especially, a better-than-expected U.S. cigarette volume/pricing provided support to the top/bottom-line. Moreover, major headwinds in Australia and Bangladesh are more than offset by strong performance in other markets.
Performance of VELO, both in the U.S. and elsewhere, is stellar. Rampant illicit vape market in the U.S. and Canada is a major drag on VUSE’s results; nevertheless, the increased momentum in state-level and federal enforcement efforts against illicit vapes in the U.S. could provide an (unbudgeted) upside to BAT over the next 2-3 years. There is no visible improvement in the heated tobacco performance: we will have to follow the results from the glo HILO launch in Japan to assess to what extent the new 2-piece device will improve the competitive position of BAT in the category.
All in all, H1 2025 Results provide further validation to our cautiously positive position on BAT’s ability to transform into a new nicotine business without sacrificing profitable growth and attain its mid-term revenue and operating profit growth targets.

