


Markets Day: 2030 Strategy to Drive Shareholder Returns
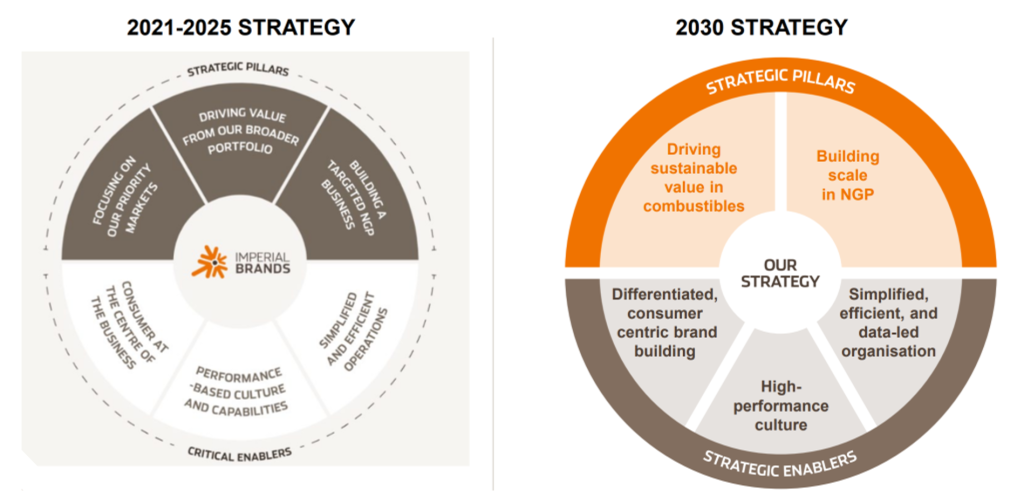
Two core objectives:
1- Drive sustainable value in combustibles: Continue focus on top-5 markets (USA, Germany, UK, Spain and Australia) which represent c. 70% of adjusted tobacco operating profit. Aim to maintain aggregate market share across these five markets to drive sustainable growth and cash delivery.
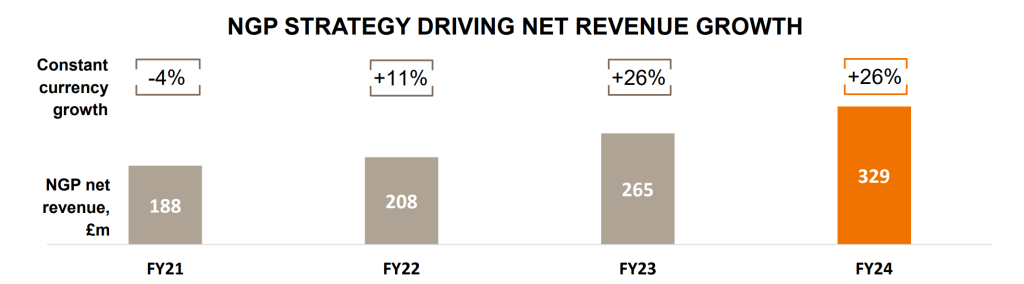
2- Build scale in Next Generation Products: Build a meaningful NGP business to support profitable growth.
Three strategic enablers to deliver the objectives:
1- Differentiated consumer & brand capabilities: Deeper insights into specific target groups, development of more differentiated “challenger” brands and innovation targeted to address the most important needs of consumers
2- High-performance culture: Selective investment in leadership skills, improved business planning and more connected ways of working
3- Simplified, efficient, and data-led organisation: Leverage scale through global business services, drive efficiencies in supply chain through manufacturing excellence and enable people to make more informed decisions through better use of data.
Key notes:
– Improved financial delivery in 2021-24 driven by the improved combustibles performance (i.e. Imperial Brands is no longer a share donor in combustibles) => -79bps market share loss in top-5 markets in 2017-20 reversed to +48bps (roughly half a percent) market share gain in 2021-24

– Total industry net revenue (in a subset of Imperial’s footprint which represent >80% Imperial’s net revenues, ex-Russia & Japan) is projected to grow by +3.2% per annum. In 2030, industry revenue mix will be: 75% combustibles, 9% vapes, 9% heated tobacco and 7% modern oral nicotine => £17bn NGP Industry (25% of the total) in 2030

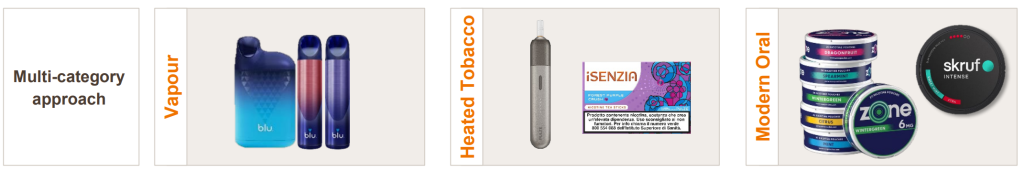
– Imperial is present in 20+ markets with blu vapes, 8 markets with Pulze heated tobacco and 8 markets with Zone and other modern oral nicotine brands. Imperial’s share in NGPs are growing in a subset of selected segments/markets (note: 4% of Imperial’s next revenue is from NGPs in FY24)

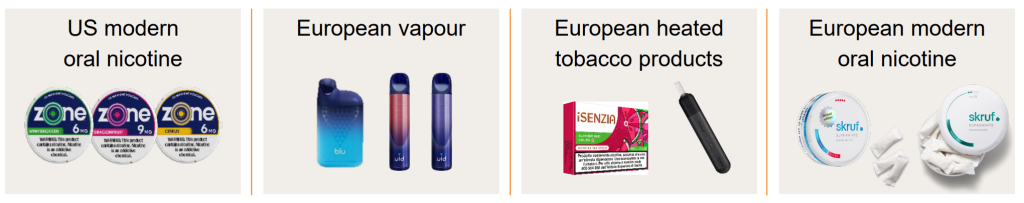
– Imperial will maintain its highly targeted approach in NGPs: Modern oral nicotine in the U.S. and all three platforms in Europe. Imperial will launch NGPs only in markets where NGPs are established and Imperial has an established infrastructure (presence).
– Imperial Brands is getting ready to launch Pulze 3.0, an upgraded heated tobacco device. Pulze 3.0 is the smallest 25+ session all-in-one device, comes with an improved taste experience, increased heating zone and new airflow technology. Based on sensory panel testing, Pulze 3.0 delivers 20% improvement in taste intensity, +16% improvement in nicotine delivery and +50% improvement in visible vapour.

– Imperial’s gross margin is in-line with the Industry average in vapour (55%) and oral nicotine (70%), but is substantially below the Industry average in heated tobacco (40%). Imperial has reached to scale only in a few categories/markets

Regional Highlights:
– USA (36% operating profit): +180bps cumulative share growth achieved in 2021-24 by investing to grow key cigarette brands. ZONE nicotine pouches are available in more than 70k stores and reached 2.7% national share (5.3% share in Imperial’s footprint). Limited investment to blu vapes given market uncertainty (i.e. PMTA outcome and lack of regulatory enforcement against illegal vapes). Salesfoce increased by +43% from 665 in FY21 to 950 in FY24, now covering 196k store locations

– Europe (42% operating profit) & AAACE (22% operating profit): Nothing worth mentioning, business as usual (i.e. brand equity investments to support future pricing, lower-tier brands and promotions to capture downtraders, improved retail coverage, etc.)
Logista: Imperial owns 50.01% of Madrid-listed Logista which distributes tobacco, other convenience products, parcels, pharma and freight across Iberia, France and Italy. Imperial supports Logista’s strategy to diversify outside tobacco. Consistently strong financial performance. Share price +92% since Oct-2020. Operating profit contribution of £0.3bn in FY24. Daily average working capital benefit of £1.8bn in FY24.
Efficiency Improvement Program: Expected annualised savings of c. £320m by the end of 2030, the majority of which will be reinvested to support growth initiatives. Total cash cost of c. £600m and associated non-cash charges of c. £140m

Medium-term Guidance:
– Tobacco & NGP revenue: low-single digit tobacco net revenue growth and double-digit NGP net revenue growth
– Group adjusted operating profit: 3-5% annual growth
– Adjusted EPS: high-single digit growth, supported by a continued reduction in share count
– Free Cash Flow: £2.2bn-£3.0bn per annum (note: £1.29bn dividend payments, £1.25bn share buybacks in FY25)

Capital allocation framework:
1- Investment: Investment to create an even more streamlined, agile, data-led business. Small bolt-on acquisitions, which will be focused on enhancing NGP capabilities
2- Leverage: A strong and efficient balance sheet to support the investment grade credit rating. Maintain the current leverage target at the lower end of net debt to EBITDA range of 2-2.5x (adjusted net debt to EBITDA:1.8x at the end of FY24)
3- Dividends: A progressively growing dividend
4- “Evergreen” share buybacks
FY25 Guidance:
– On track to deliver FY25 expectations: low single-digit tobacco & NGP net revenue growth, middle of mid single-digit (simply, around 5%) adjusted operating profit growth
– Double-digit NGP net revenue growth
– At least high-single-digit adjusted EPS growth, supported by the ongoing share buyback and partly offset by higher adjusted finance and tax costs
– H2-weighted performance driven by the phasing of combustible pricing and investment; low single-digit (1%-2%) adjusted operating profit growth and mid-single digit EPS growth in H1 2025
– Strong combustibles pricing and stable aggregate share in top-5 markets in H1 2025
– 10%-15% NGP net revenue growth in H1 2025
– FX headwinds: c. 2-3% on H1 2025 net revenue and operating profit; c. 1-2 per cent FY25 net revenue and operating profit
Our Take:
Imperial Brands managed to substantially improve its financial delivery in the 2021-24 period, mainly by reversing the share losses in the top-5 combustible markets. Imperial’s 2030 Strategy is mostly based on their existing approach: maximize financial returns from combustibles and build a highly targeted presence in NGPs. We believe what got them here (i.e. a re-rating from 6x to 9x P/E) won’t get them there (i.e. a further re-rating from 9x to mid-teens P/E) as the combustible decline and transformation to NGPs accelerate in Imperial’s footprint. Imperial did not provide any guidance on volume progression; we expect Imperial’s volume will continue to decline 4%-5% per annum (recall: more than 20% decline from FY20 to FY24). We are disappointed by the lack of a concrete 2030 NGP target as % of revenue. Moreover, mid-term annual operating profit growth guidance of 3-5% is below the expected mid-single digit level (5%) and efficiency savings will be mostly allocated to catch-up investments (instead of improving the bottom-line).

