


CEO Transition: Stefan Bomhard to be succeeded by Lukas Paravicini (CFO) as CEO on October 1, 2025. Lukas to be succeeded by Murray McGowan (Chief Strategy & Development Officer) as CFO
Top-line & Bottom-line results1
Adjusted: at constant currencies
– Volume: -3.2% (to 87Bn sticks), reflecting the wider industry decline in the markets where Imperial Brands is present (“established footprint”) and despite aggregate market share gains (+6 bps) in top-5 priority markets (ahead of the strategic objective to maintain share)
– Strong tobacco pricing/mix (+5.9%) more than offsetting volume declines
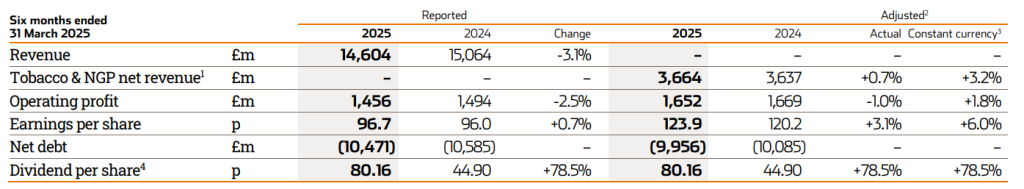
– Revenue: +3.2% (NGP revenue: +15.4%, driven by scale-up in launch markets and product innovation)
– Operating Profit: +1.8% (adjusted NGP operating losses reduced by -14.0% to £43 million despite increased investment in Zone roll-out in the USA)
– Adjusted operating profit – Distribution: Flat as tobacco segment growth offset weakness in long-distance transportation
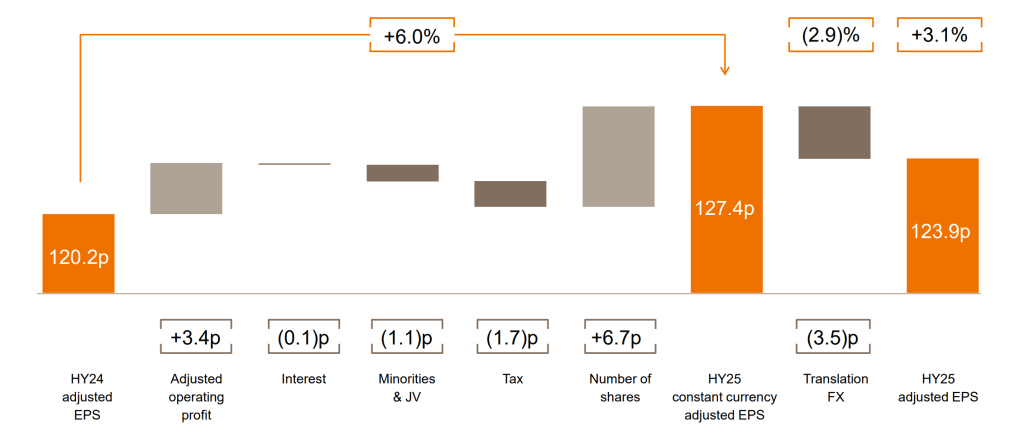
– EPS: +6% (operating profit growth and reduced share count, more than offsetting higher tax rate)
– 12-month FCF: £2.4 billion, reflecting strong cash conversion at 99%
– Interim Dividend: up +4.5% to 80.16p (reported: +78.5% due to rephasing to four equal instalments)
– On track to meet FY25 guidance, supported by H1 2025 tobacco pricing and continued momentum in NGP
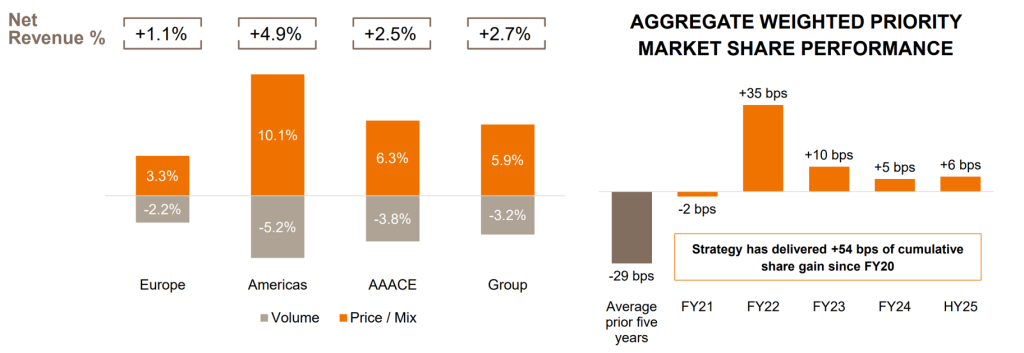
– Regional Overview: Volume decline (-2.2% in Europe, -5.2% in Americas and -3.8% in Rest-of-the-World) more than offset by strong pricing/mix (+3.3% in Europe, +10.1% in Americas and +6.3% in RoW) across all three regions
Highlights – Traditional Products:
– Aggregate SoM up +6bps in five priority markets: gains in USA (+10 bps), Germany (+65 bps) and Australia (+5 bps) offsetting declines in UK (-70 bps) and Spain (-90 bps)
– With SoM gain in Germany, two largest markets (including U.S.) are in share growth
– Focused investment in brand equity and sales force initiatives driving share gains and strong pricing (key for financial delivery)
Highlights – NGPs:
– Growth in net revenue and market share in all three categories: strong growth in the Europe and USA more than offsetting temporary headwinds in AAACE
– Modern Oral: Growing strongly driven by the roll-out of Zone in the USA and product innovation in Europe. Zone (launched in the U.S. in February 2024) is now available in 72,000 stores and reached 2.6% national category share (5.1% in footprint). Continuing momentum in Europe with Skruf: improved pouch format launched in Sweden
– Vapour: Roll-out of new formats to support growth in key European markets. Growing share across footprint, driven by UK. Focused on growing scale in existing markets
– Heated tobacco: Expanding consumable line-up for Pulze 2.0 with iSenzia, flavoured herbal sticks, in Europe. Pulze 3.0 launch in H2 2025 (smallest 25+ session all-in-one device with improved flavour and enhanced nicotine delivery)
Finanical Highlights:
– Adjusted operating cash conversion: ~99% on a 12-month basis
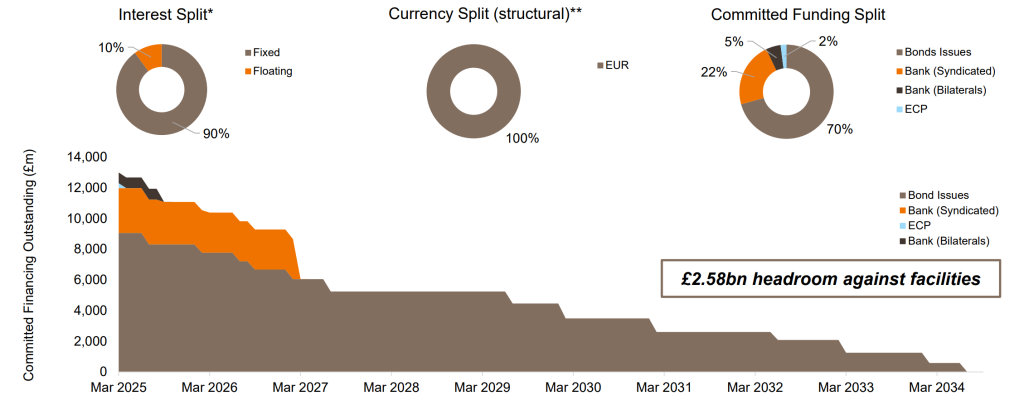
– Adjusted net debt: £10 billion; Adjusted net-debt-to-EBITDA on a 12-month basis improved 0.1x to 2.4x; On track to deliver adjusted net-debt-to-EBITDA of ~2.0x at the year end; Reported net debt: £10.5 billion
– Interim dividend: up +78.5% to 80.16 pence, reflecting underlying growth of 4.5% and the rephasing of dividend to four equal instalments
– On track to grow FY25 dividend in line with underlying business performance and progressive dividend policy. Multi-year/Evergreen buyback: £1.25 billion this year. Cumulative capital returns from FY21 to FY25: ~£10 billion (i.e. ~67% of market capitalisation at January 2021)
FY25 Guidance: Re-iterated
– On track to meet the FY25 guidance despite a more uncertain global economic environment: low-single digit growth in tobacco & NGP net revenue and close to the middle of mid-single-digit (5%) range growth in adjusted operating profit (at constant FX)
– Strong tobacco pricing in H1 2025 and slightly lower NGP losses to support a stronger H2 2025
– Double-digit net revenue NGP growth
– At least high-single-digit EPS growth in FY25, supported by the ongoing share buyback and partly offset by higher adjusted finance and tax costs
– FX translation to be a headwind of 2.0-2.5% to net revenue and 3.5-4.5% to adjusted operating profit and EPS
Summary:
H1 2025 Results are fine (i.e. in line or slightly better than expected). Tobacco volume (-3.2%) held up well despite the strong pricing / mix (+5.9%). NGP revenue growth (+15%) is encouraging at the top-line while not knowing the contribution of different growth drivers (i.e. geographical expansion, portfolio expansion, temporary market share gains – product trial, solid market share gains – product adoption).
However, the CEO transtion announcement is an unexpected development. The 5-year transformation plan, led by Stefan Bomhard, resulted in the stabilization of the Imperial’s financial delivery and extraction of the maximum value from its melting combustible portfolio. “German-style discipline” in financial delivery has been a key selling point for Imperial Brands shares, especially over the past 12-18 months. Market will be disappointed by the departure of Stefan Bomhard at a time when a certain level of stability and momentum were achieved at Imperial Brands.

