


On track to deliver FY25 guidance. £1.45 billion share buyback in FY26, to completed no later than 28 October 2026 (+16% increase compared to £1.25 billion in FY25). FY25 Results to be announced on November 18, 2025
FY25 guidance stated in May 2025: Low-single digit tobacco & NGP net revenue growth. Adjusted operating profit close to the middle of the mid-single-digit range. Double-digit net NGP revenue growth. At least high-single-digit EPS growth
Key Highlights
– The operational and financial delivery is in line with guidance, underpinned by growth in both tobacco and NGP. FY25 is fifth and final year of the 2021-25 Strategy, setting a foundation for 2026-30 Strategy
– Revenue: On track to deliver low single-digit tobacco & NGP net revenue growth at constant FX. Revenue growth underpinned by strong combustible pricing and ~13% (i.e. mid-point of 12-14% range) growth in NGP revenue, driven by the scale-up across the existing footprint (up +26.4% in FY24). Combustible pricing more than offsets volume declines, which have eased across the majority of the footprint, although some volatility exists in certain markets. Imperial expects market share gains in the US, Germany and Australia, to broadly offset declines in Spain and UK – following a cumulative share gain over the last 5 years
– Operating profit/EPS: Adjusted operating profit expected to grow at a similar rate to last year (FY24: +4.6%; FY25 consensus estimate: +4.1%). High-single-digit adjusted EPS growth, driven by adjusted operating profit growth and share count reduction from the ongoing buyback and partly offset by higher adjusted finance and tax costs as well as increased minority interests, given strong growth in some of African markets. NGP losses to be broadly flat year-on-year (FY24: £79 million loss)
– FX translation: c. 2.0 to 2.5% headwind to net revenue (unchanged) and c. 2.5 to 3.0% headwind to adjusted operating profit and EPS (before: 3.5-4.5%)
– Average number of shares (FY25): 824.8 million
– Strong operating cash conversion. FY25 leverage: net debt at the lower end of the 2.0 to 2.5x EBITDA
– Progress on 2026-30 Strategy: Started a consultation regarding the future of the Langenhagen, Germany factory (i.e. either a sale of the site to a third party or a closure)
– Dividend: Increased by +4.5% to 160.32 pence per share, paid in four equal quarterly payments, as per the previous announcement
– FY26 capital returns to exceed £2.7 billion, representing around 11% of the current market capitalisation (cumulative capital returns c. £10 billion in FY21-25)
Latest consesus estimates – summary
Based on the latest closing price (£30), Imperial Brands trade at 9.6x FY25 EPS estimate – at a discount to all other tobacco majors. Dividend yield: 5.3%
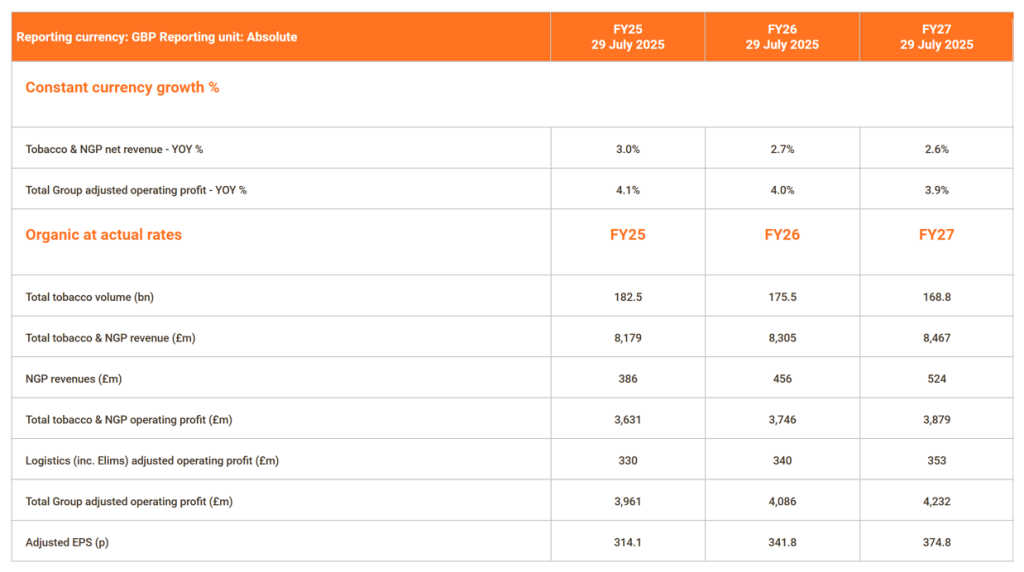
Download the latest consensus estimates: Imperial Brands 2025-27

