


Imperial Brands will release a pre-close trading update for the first half of FY24 (October 2023 – March 2024) on April 9, 2024.
Imperial’s FY23 results (October 2022 – September 2023) were characterized by robust combustible pricing (pricing: +11%, mix: -3%; total price/mix: +8%) and stringent cost control measures more than offsetting the sharp volume decline (-10.4% reported; -7.1% excluding the impact of the Russia exit). As a result, on an adjusted basis, the revenue was up +1.4% and the operating profit growth was up +3.9% (i.e. +4.1% for the Tobacco segment only). Recall: Imperial Brands: FY23 Results.
In FY23, NGP revenue was up +26.4% (driven by launches across categories in the EU: +40.4%) while the NGP losses widened +48.3% to £135Mn (new product and market launches => higher investment). NGP’s weight in total (tobacco) revenue reached 3.4% in FY23 (vs. 2.7% in FY22 and close to 40% for the industry leader, Philip Morris International).
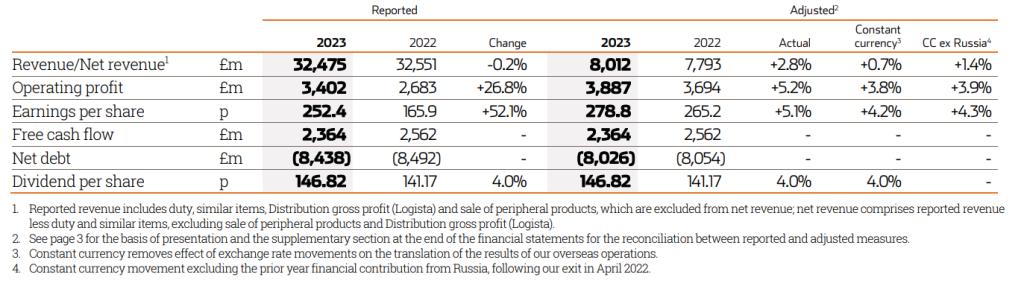
For the FY24, Imperial guided low single-digit revenue growth (1%-3%) and close to the middle of the mid-single digit range (close to 5%) operating profit growth – with the operating profit growth expected to be H2 2024 weighted due to the phasing of pricing and NGP investments: i.e. only low single-digit (1%-3%) growth in H1 2024.
Ahead of the pre-close trading update, sell-side analyst consensus1 closely mirrors the Imperial’s guidance: +2% revenue and +4.2% operating profit growth in FY24. However, there is quite a bit of variation in the profit growth estimates: ranging between 2% to 5%.
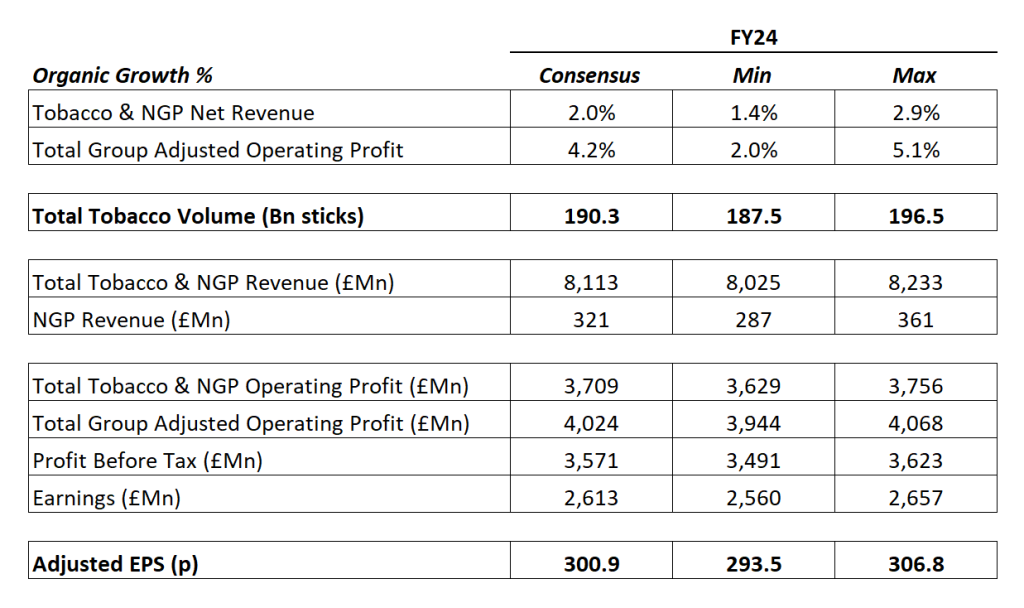
Moreover, there are downside risks to both tobacco volume and NGP growth estimates:
– 3.9% volume decline from a base of 198Bn in FY23 (i.e. a steeper volume decline is likely)
– 46% NGP revenue growth from a base of £220Mn in FY23 (i.e. the growth achieved in FY23 was mostly as a result of the inventory filing effect; unless Imperial’s newly launched NGPs are increasingly adopted / re-purchased by the consumers, it would be difficult to maintain the initial growth momentum).
What to watch out for?
– Confirmation (or revision) of the FY24 revenue and operating profit guidance
– Tobacco volume decline and whether the price/mix improvement continue to compensate the volume decline
– NGP growth (especially, any disclosures on consumer adoption & re-purchase)
Share price action
Imperial Brands (IMB.L) made a 52-week low at £15.53 on October 4, 2023 – just before the announcement of the FY23 Trading Update. However, initiation of the new & extended £1.1Bn stock re-purchase program (announced during the FY23 Trading Update) drove Imperial shares up in the following 4 months – to a local high at £19.5 in late-January 2024. Since then, Imperial shares are in a declining trend (last close: £17.25). Recall: Imperial: FY23 Trading Update and Share Buybacks.
Imperial will report the full H1 2024 results only on May 15, 2024: next week will be about qualitative updates and confirmation/invalidation of the guidance provided during the FY23 earnings release. Considering that IMB.L is already trading at an undemanding 5.75x P/E multiple (based on the FY24 EPS consensus of £3) with a comfortable debt level (around 2x net debt / EBITDA), it is unlikely that the pre-trading update will trigger a major sell-off next week – even if the volume decline and NGP growth disappoint (as explained above).
We continue to expect Imperial to range trade below the key £20 level and at historical lows (in terms of valuation multiples). As long as Imperial fails to address the “business concentration” concerns, the £20 level is likely to act as a impregnable ceiling for the Imperial shares. Recall that Imperial’s business is concentrated in the dying-out cross-sections of the Industry both in terms of product and geographical mix:
– product mix: almost fully dependent on traditional tobacco products (only 3% of the revenues from NGPs)
– geographical mix: excessively dependent on a handful of mature markets (- in which, a “tipping point” has been reached in terms of cigarette volume decline).
References:

