


Key Business Metrics: Q3 20251
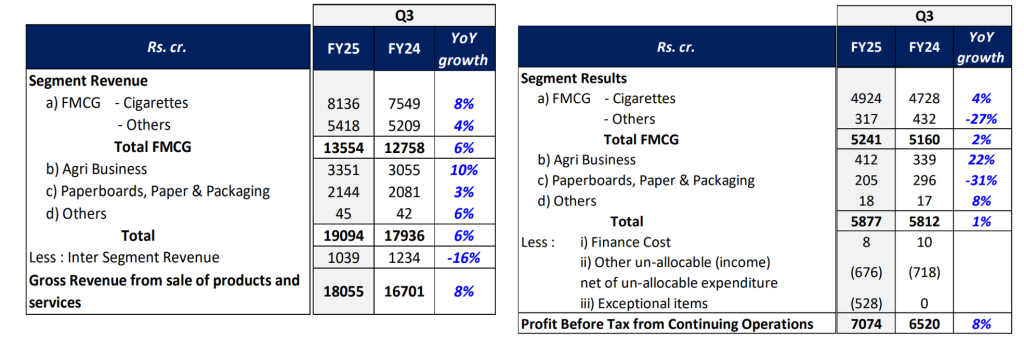
Gross Revenue is up +8% and EBITDA is up +3% (ex-paper +4.5%) despite a subdued demand environment and sharp escalation in key input materials (e.g. edible oil, wheat, potato, leaf tobacco, wood)
Hotels Business demerged into ITC Hotels Limited (ITCHL) with effect from January 1, 2025: reported as “Discontinued Operations” in the ITC financial results
Profit after tax is up +2.1% (on a comparable basis)
Q3 2025 EPS (diluted): ₹4.50 (up +1.1%; flat at ₹4.33 from continuing operations)
12-month rolling EPS (diluted): ₹16.35 (₹15.94 from continuing operations; trading at 27.7x trailing EPS based on the last closing price of ₹441.1)
Interim dividend: ₹6.5 (vs. ₹6.25 in FY24)
Q3 FY25 Segment Highlights
Cigarette Segment: (42.6% weight in gross revenue, 83.8% weight in operating profit)
– Net segment revenue and operating profit are up +8.1% and +4.1%, respectively
– Tax stability supporting volume recovery from illicit trade. Market position reinforced through focused product portfolio & commercial interventions. Premium segment & new innovations continue to gain robust traction
– Sharp escalation in input costs (leaf), partly mitigated through improved mix, strategic cost management and calibrated pricing. Trade marketing spending restructured for sharper last mile execution
– Union Budget 2025: Amendments to Central Goods and Services Tax (CGST) Act that enable a Track & Trace mechanism to strengthen the efforts to control illicit trade
Other Segments:
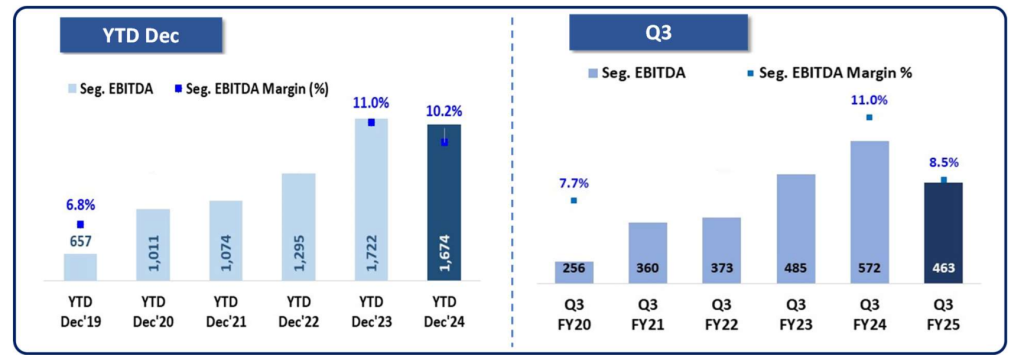
– FMCG (revenue is up +4%, operating profit is down -27%): Segment EBITDA margin is down to 8.5% from 10.2% in YTD24. Severe inflationary pressure in input prices (e.g. edible oil, wheat, maida, potato, cocoa and packaging inputs) is partially mitigated through focused cost management initiatives, calibrated pricing actions and premiumisation
– Agri Business segment (revenue is up +10%, operating profit is up +22%): Strong growth in Value Added agricultural exports of Spices & Coffee. Robust growth in Leaf tobacco exports driven by new business development & agile execution. Stock limits & export restrictions on Wheat continue to limit business opportunities̶. Strong order book in Rice exports after partial easing of trading restrictions
– Mysuru factory (to manufacture and export of nicotine & nicotine derivative products conforming to US & EU pharma standards): Product trials in advanced stage of finalisation; focused business development underway to accelerate scale-up. Export shipments expected to commence shortly.
– Paperboard, Paper & Packaging (revenue is up +3%, operating profit is down -31%): Negatively impacted by low-priced Chinese & Indonesian supplies in global markets and muted domestic demand. Persistent increase in wood cost, exacerbated by heavy cyclonic rainfall in core plantation area.
Summary:
Volume claw-back from illicit cigarette trade – as foreseen by the absence of a tax hike in the FY25 Union Budget – fell short of driving the sequential improvement in ITC’s bottom-line delivery to the level expected in Q3 2025. Subdued demand conditions in the overall consumption (FMCG) space, increasing input costs (leaf, wood etc.) as well as the circumstantial factors continue to put pressure on ITC’s profitability (i.e. overall gross margin down from 34.8% to 32.6%, year-on-year basis).
Nevertheless, Market has been pricing in ITC’s less-than-stellar operational performance since September 2024 with the shares trading more than 15% below its all-time high (₹528 print; ₹499 adjusted for the ITC Hotels spin-off). We will watch whether the ₹400 level to serve as a strong support on the downside.
References:

