


Key Business Metrics: Q4 2025 & FY251
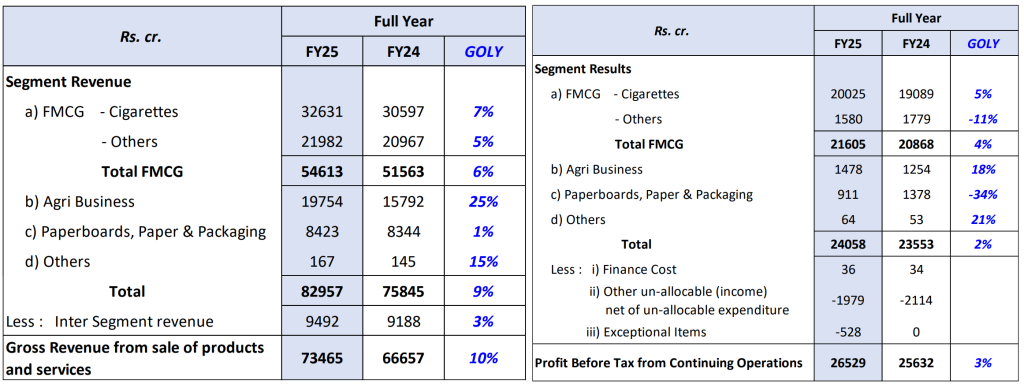
– Q4 2025: Gross Revenue up +9.2% and Operating Profit up +2.5% (ex-Paper, up +4.2%)
– FY25: Gross Revenue up +10.2% and Operating Profit up +2.3% (ex- Paper, up +4.4%)
– Resilient performance amidst a subdued demand environment and sharp escalation in input costs. Sharp escalation in key input materials (edible oil, wheat, maida, potato, cocoa, leaf tobacco, pulpwood etc.), especially in H2 2025
– Q4 2025 EPS (diluted): ₹4.05 (from continuing operations; up +2.3%)
– FY25 EPS (diluted): ₹15.76 (from continuing operations; down -1.1%) => trading at 27x trailing EPS based on the last closing price of ₹425.5
– Final dividend: ₹7.85; Total FY25 dividend: ₹14.35 (including interim dividend of ₹6.50 per share paid on March 7, 2025) => Annual dividend up +4.4% from ₹13.75 in FY24

– Hotels Business demerged into ITC Hotels Limited (ITCHL) with effect from January 1, 2025: reported as “Discontinued Operations” in the ITC financial results
– Several value accretive acquisitions in high-growth & future-facing businesses in the FMCG space: Sresta Natural Bioproducts (24 Mantra Organic Foods), Mother Sparsh Baby Care (Mother Sparsh) and Ample Foods (Prasuma & Meatigo)
– Acquisition of the Pulp and Paper Business of Aditya Birla Real Estate Limited (“Century Pulp and
Paper”) to add scale, efficiencies and resilience to the existing operatiions
– MSCI-ESG “AA” rating for the 7th successive year. Inclusion in the Dow Jones Sustainability Emerging Markets Index for the fifth year in a row
Q4 2025 & FY25 Segment Highlights
Cigarette Segment: (39.3% weight in FY25 revenue, 83.2% weight in operating profit)
– Q4 2025: Net segment revenue and operating profit are up +6.0% and +4.0%, respectively
– FY25: Net segment revenue and operating profit are up +7.1% and +4.9%, respectively
– Strategic portfolio and micro market interventions, with focus on competitive belts and to counter illicit trade, drive volume-led growth and reinforce market standing. Differentiated and premium offerings continued to perform well leveraging mainstream trademarks & innovation. Severe cost escalation in leaf tobacco partially mitigated through product mix enrichment
– Union Budget 2025: amendments to the CGST Act enabling a Track & Trace mechanism to strengthen efforts to control illicit trade (volume recovery from illicit trade expected)
Other Segments:
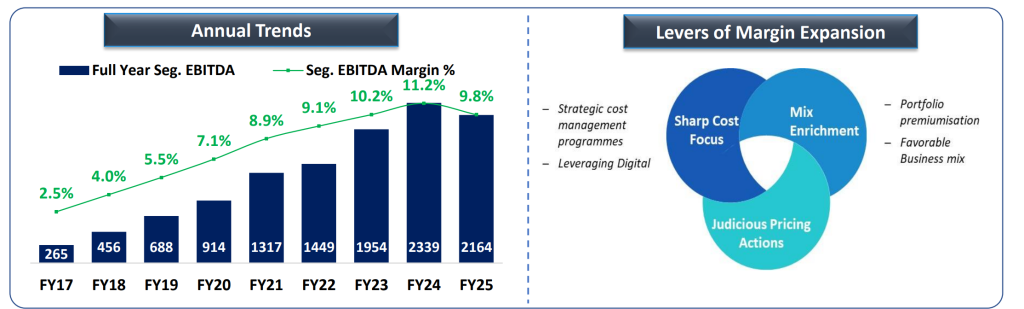
– FMCG (revenue is up +3.7%/+4.8%, operating profit is up +5.4%/+6.2% in Q4/FY25, respectively, ex-Notebooks): Resilient performance in FMCG Segment amidst subdued demand conditions and sharp escalation in input costs. FMCG margin down 140bps to 9.8% in FY25. Notebooks impacted by heightened competitive intensity from the local/regional brands. Strong performance in premium portfolio and alternate channels. Severe inflationary pressures witnessed in prices of edible oil, wheat, maida, potato, cocoa, packaging inputs – partially mitigated through focused cost management initiatives, portfolio premiumisation and calibrated pricing actions. Sustained competitive levels of trade & marketing investments to support growth and market standing
– Agri Business segment (revenue is up +18%/+25%, operating profit is up +26%/+18% in Q4/FY2, respectively): Strong customer relationships and agile execution continue to drive growth in Leaf Tobacco & Value Added Agri exports (Coffee, Spices, etc.). Post extensive product development and customer trials, export shipments from the Mysuru factory (manufacturing Nicotine and Nicotine derivative products) commenced in Q4 FY25. Progressive scale up expected in FY26
– Paperboard, Paper & Packaging (revenue is up +6%/+1%, operating profit down -31%/-34% in Q4/FY2, respectively): Negatively impacted due to low priced Chinese & Indonesian supplies in global markets, including India. Soft domestic demand conditions and unprecedented surge in wood prices continue to weigh on margins. Strategic interventions to be made in plantations (including collaborative public partnership models on degraded forest land), product portfolio and structural cost management
Summary:
Subdued demand conditions in the overall consumption (FMCG) space, increasing input costs (leaf, wood etc.) as well as the circumstantial factors continue to put pressure on ITC’s profitability (i.e. overall gross margin down 240bps from 38.5% to 36.1%, year-on-year basis). Nevertheless, ITG’s financial delivery (+10.2% revenue and +2.3% operating profit growth) is pretty respectable under these circumtances. Market has been pricing in ITC’s less-than-stellar operational performance since September 2024 with the shares trading 15% below its all-time high (₹528 print; ₹499 adjusted for the ITC Hotels spin-off). We continue to expect ₹400 level to serve as a strong support on the downside while the investors wait for the business environment to improve and/or ITC Management’s interventions to pay off.
References:

