


Tobacco Segment: 88% weight in revenue, 100+% weight in adj. operating profit in FY24
Top-line & Bottom-line Results – Tobacco Segment Only1
Excluding Pharmaceuticals and Processed Food Segments; adjusted, at constant currencies
Revenue: +14.5% in Q4 2024 and +9.1% in FY24
Operating profit: +56.1% in Q4 2024 and +9.7% in FY24
Total Volume: +3.0% in Q4 and +2.4% in FY24 (combustible volume +2.5% and +2.0%, respectively)
RRP volume: +27.7% in Q4 and +24.2% in FY23
RRP weight – FY24: 2.0% by volume (+0.4pps) and 3.6% by revenue (+0.3pps)
Dividend: ¥194 (no change; dividend payout ratio of 74.3%)

Operating Profit (at current FX): +5.6%

– Volume (+0.7%): Higher total volume, more than offsetting the impact of negative geographical mix. Acquisition of Vector Group supported the growth
– Price/mix (+25.6%): Robust pricing contribution in multiple markets, more than offsetting the impact of unfavorable product mix due to downtrading
– Others (-16.5%): Incremental investments towards Ploom. Inflation-led cost increases
– FX (-4.1%): Unfavorable impact on adj. operating profit due to the depreciation of emerging currencies and appreciation of cost-related currencies, partially offset by the positive impact of a weaker JPY
RRPs: Ploom X (heated tobacco)
– Heated tobacco stick revenue and volume (net of Ploom S discontinuation) grew by +44% and +40%, respectively, in FY24. Increased investment prioritizing Ploom to accelerate top-line momentum. RRP expected to be accretive to earnings by 2027 at the latest
– Ploom is available in 24 markets, representing c.75% of global heated tobacco volume. 11 additional markets in 2024, including Jordan, the Philippines & South Korea in Q4 2024
– On target to reach ~80% of global volume coverage by end of 2025. Positive consumer feedback across markets, and accumulated learnings support the finetuning of go-to market approach

– Japan: reached 12.6% segment share in Q4 2024. Success of Ploom X ADVANCED, supported by better consumer experiences (increased # of Ploom consumer touchpoints and improved consumer KPIs). For further details, see “Heated Tobacco Products”
– Outside of Japan: reached 1.4%-5.4% segment share in select markets
– Ploom share of segment in measured footprint (i.e. 13 markets where Ploom has at least 12 month of presence): 7.8% in November 2024 (+3.2ppt vs. in Decemeber 2022)
– On track with our 2028 ambition to reach mid-teens heated tobacco share of segment

Combustibles
– Despite 1.8% industry volume decline in the measured footprint (cigarette, fine cut and heated tobacco volume in 70+ markets representing 90+ of the volume), JT volume increased – resulting in +0.5ppt market share gain (including the key markets of Italy, Japan, the Philippines and Taiwan)
– GFB (Global Flagship Brands) volume grew for the 6th consecutive year to 73% of total volume. GFB includes four Brands: Winston, Camel, MEVIUS and LD
– Winston (#2 after Marlboro) and Camel (#3) volume grew +4.4% and +7.9%, respectively
– Robust combustibles pricing offsets impacts from ongoing inflationary pressure & down-trading and drives high single-digit revenue growth

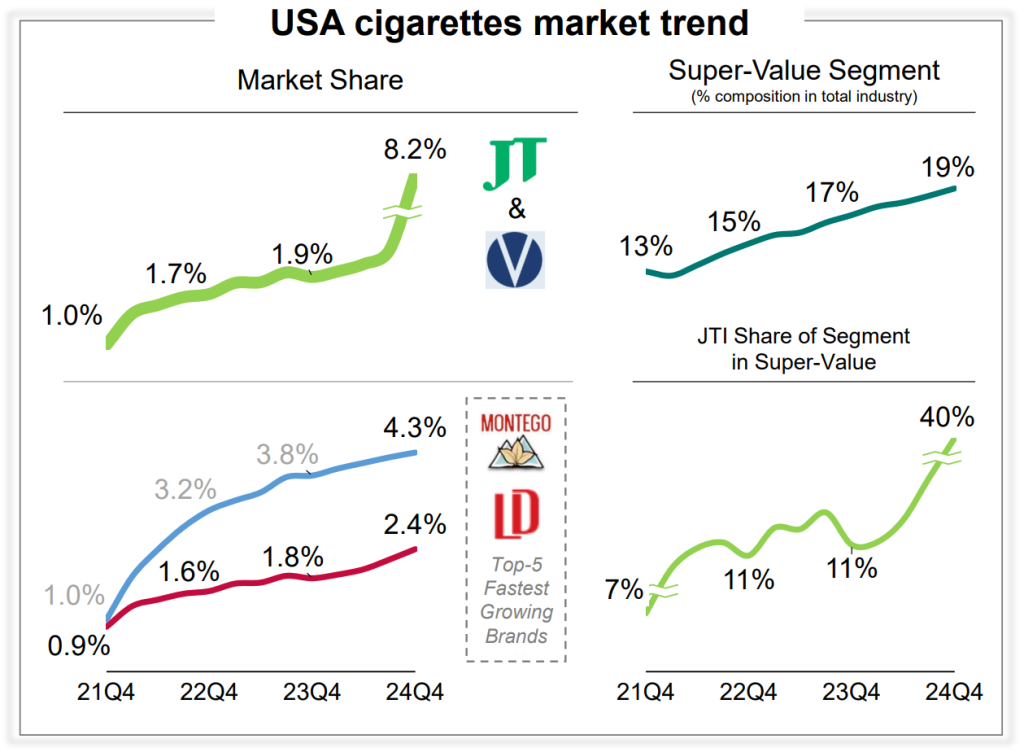
Vector Acqusition & the US Market
– Became the 4th largest player in the US by acquiring Vector Group.
– USA to be a Top-10 profit markets (gross margin/stick c.3x higher than in existing footprint) and rebalance of FX exposure
– Portfolio well-positioned to address consumer trends in the growing Super-Value segment
FY25 Forecast
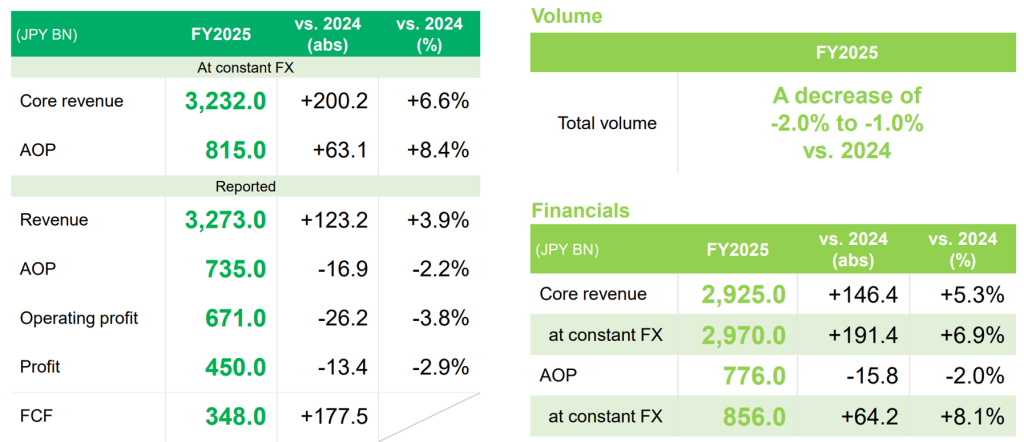
– Consolidated core revenue: +6.6% to ¥3,232Bn (at constant FX; +3.9% on reported basis)
– Consolidated operating profit: +8.4% to ¥815Bn (at constant FX; -2.2% on reported basis)
– Tobacco Segment: revenue +6.9%, operating profit +8.1% (at constant FX)
– Unfavorable FX on both core revenue and operating profit, mainly due to the depreciation of certain emerging market currencies and the appreciation of cost-related currencies
– Tobacco volume: -1% to -2% decline
Summary
Overall, combustible volume growth (+2.0%) combined with strong pricing and contribution from Vector Group helped JT deliver 9+% revenue and operating profit growth in FY24. The FY25 guidance signals another year of strong growth ahead. JT’s traditional business (combustibles) is in good shape.
On the RRP side, thanks to the geographical expansion of Ploom X and progressive category share gains in Japan, year-on-year volume growth accelerated: from +11.8% in FY23 to +24.2% in FY24. Nevertheless, it is yet to be seen whether the progress achieved in heated tobacco is in proportion to the outsized ¥450Bn ($2.9Bn) investment (over the three-year period from 2024 to 2026, mostly in commercial initiatives). With only 3.6% of its revenue coming from RRPs (compared to ~40% for PMI), JT still has a lot to do in terms of portfolio transformation. We will continue to closely watch Ploom X’s performance in the expansion markets (i.e. whether the segment share is progressively increasing towards the mid-teens).
Following a 27-month bull run and +130% price appreciation, the long overdue correction in JT shares is in action since June 2024; JT shares now trade more than 15% below its 52-week high and are where they were a year ago (i.e. below the key ¥4,000 level). At this point, a re-rating requires JT to demonstrate that its outsized RRP investment will result in a more sizable RRP franchise that complements its strength in the cigarette category (i.e. a more balanced & sustainable business mix).
References:

