


Top-line & Bottom-line results1
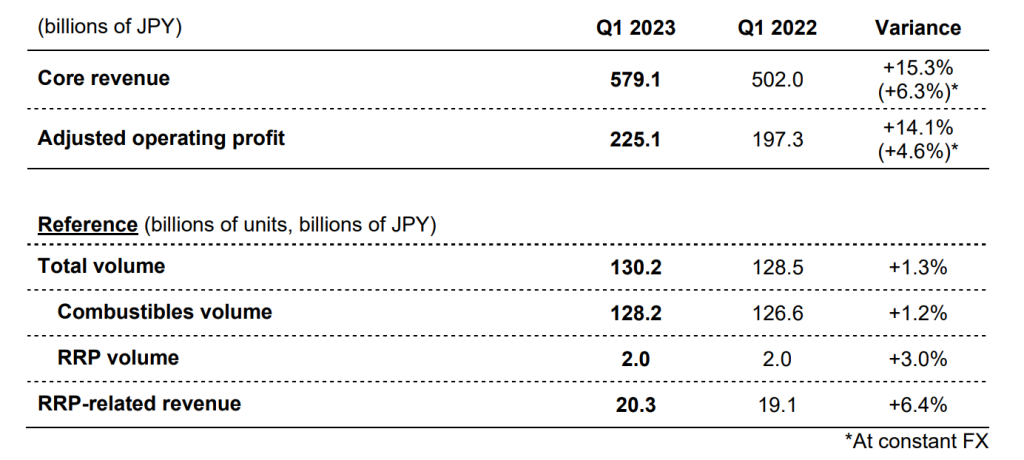
Adjusted, at constant currencies; Tobacco only – excluding Pharmaceuticals & Processed Food
Revenue +6.3% (positive pricing contributions)
Operating profit +4.6% (lower than top-line growth due to the higher supply chain costs)
Total Volume +1.3% (combustible volume +1.2%; RRP volume +3%)
Ploom X (heated tobacco) Update
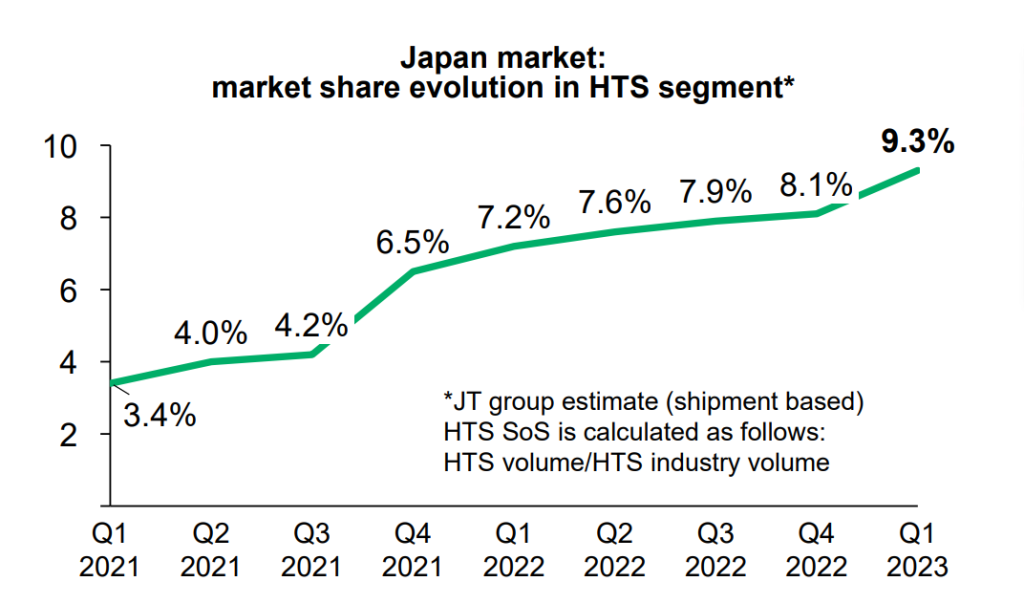
– RRP is ~37% of total tobacco industry volume in Japan and Ploom X reaches 9.3% SoS
– Now available in the UK, Italy & Lithuania
– To be available in Lisbon (Portugal) in mid-May and in 10+ markets by end of 2023 (deployment in 20+ markets in 2023-24)
Our take-away
Overall, combustible volume held up well (+1.2%) and price hikes helped deliver mid-single digit revenue & operating profit increase in Q1 2023. However, as a laggard in transformation to RRPs, JT’s RRP volume growth (only 3%) is especially disappointing. We will closely watch Ploom X’s performance in the expansion markets. That being said, in the “League of Laggards: Altria, Imperial, JT”, we still favor JT due its size/scale, higher emerging market exposure (supporting the combustible volume) and very low indebtedness.
References:

