


Tobacco Segment: 88% weight in revenue, 100+% weight in adj. operating profit in Q1 2024
Top-line & Bottom-line Results – Tobacco Segment Only1
Excluding Pharmaceuticals and Processed Food Segments; adjusted, at constant currencies
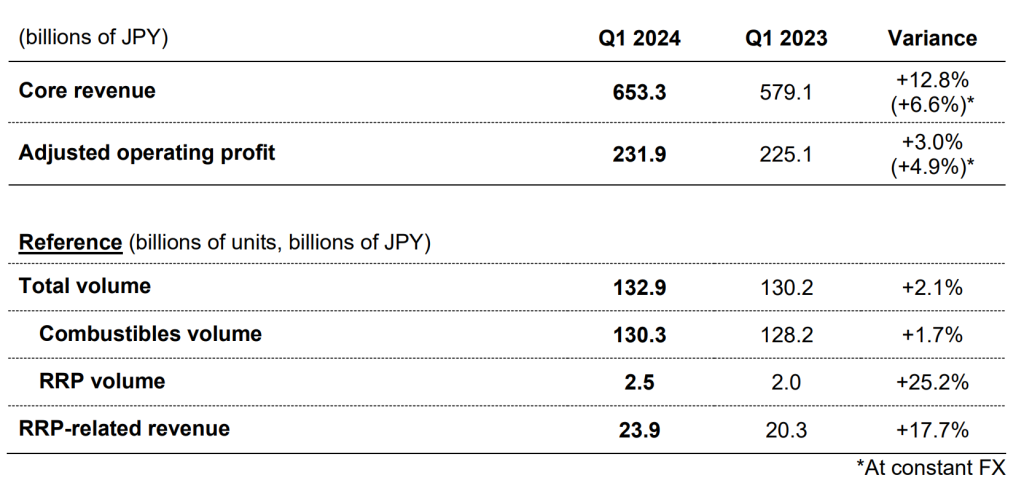
Revenue: +6.6% in Q1 2024, driven by positive price/mix variance from all clusters and RRP-related revenue growth (+17.7%, led by Ploom X in Japan), partially offset by volume decline in Asia (-4.5%) cluster
Operating profit: +4.9% in Q1 2024, driven by core revenue growth and partially offset by higher investments towards heated tobacco and higher supply chain costs
Total Volume: +2.1% (combustible volume +1.7%; RRP volume +25.2%)
RRP weight – Q1 2024: 1.9% by volume and 3.7% by revenue
RRPs: Ploom X (heated tobacco)
– Ploom X is now available in 17 markets: 4 new markets so far in 2024 and 4 additional markets planned by June 2024 => geographical expansion plan on track
– Set to reach mid-teen heated tobacco segment share in key markets and RRP break-even by 2028
– RRP volume growth (+25.2%), driven by continued momentum in Japan and increasing contributions from the other markets
– RRP volume contribution: 2Bn Japan + 0.5Bn other markets (still 80% Japan vs. 34% for PMI in FY23)
– Japan: Solid market share gains in an increasingly competitive market due to aggressive promotions and price reductions by competitors. RRP category now makes up 42.2% of the total tobacco industry volume. JT’s total category share reached 13.5% (i.e. 11% Ploom + 2.5% hybrid platforms) in Q1 2024
– Other markets: Steady growth since the launch (fueled with expansion in distribution), reaching between 1.3% (Hungary) and 4.6% (Czechia) segment share in different markets

Combustibles
– Combustibles volume growth (+1.7%) driven by the Global Flagship Brands (GFB) and the EMA cluster (mostly, Turkey and Russia)
– GBP volume: +6.3%, driven by Winston (+9.8%) and Camel (+10.5%)
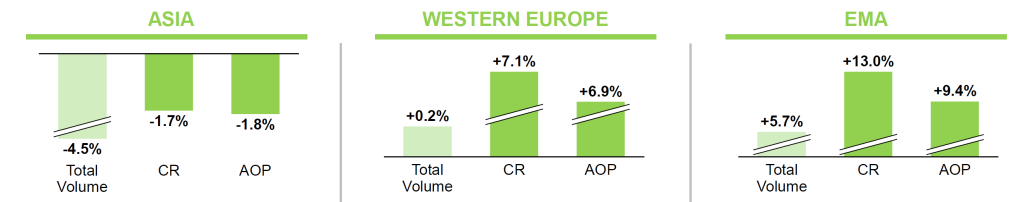
– EMA: Volume +5.7%, Core Revenue +13%, Adjusted Operating Profit +9.4%
– Continued combustibles industry volume decline in the UK (-14.4%), Japan, the Philippines and Taiwan => JT’s cluster volume: Asia -4.5%, Western Europe flattish
FY24 Forecast
– No revisions for the time being: assessing uncertainties (including FX trends) and revisions, if any, to be announced at the Q2 2024 results release or later
Recall: FY24 Guidance from the FY23 Results release
– Tobacco segment (at constant FX): core revenue +4.5%, operating profit +2%
– Basic EPS: ¥256.3. Based on the share price at the time of writing (¥4,342), JT now trades at 17x 2024EPS (the second best multiple among the industry majors after ITC)
Our Recollection
Overall, combustible volume growth (+1.7%) combined with pricing/mix improvements helped deliver mid-single digit revenue & operating profit increase in Q1 2024. Thanks to the geographical expansion of Ploom X and progressive category share gains in Japan, year-on-year RRP volume growth accelerated: from only +3% in Q1 2023 to +17% in Q3 2023 to +25.2% in Q1 2024. We will continue to closely watch Ploom X’s performance in the expansion markets (i.e. whether the segment share is progressively increasing towards the mid-teens).
In February 2023, we noted: “In the League of Laggards to the transformation to RRPs (Altria, Imperial, JT), we clearly favor JT due its size/scale, higher emerging market exposure (supporting the combustible volume), very low indebtedness and strong focus on expanding its presence in the heated tobacco category”.
JT shares increased +65% since our call (i.e. correction from an overly undervalued level, further fueled by the general market interest in Japanese equities) and are now trading well-above the key ¥4,000 level. For further details: Japan Tobacco: Share Price Surge. Although we still favor JT over Altria and Imperial Brands (in terms of business strength & growth), we need to underline that the strong price momentum – rather than the strength in business fundamentals – is driving the JT shares up at this stage (recall: JT now trades at a premium to the industry leader, PMI, despite RRPs having less than 4% weight in its total revenue).
References:

