


Pharmaceutical business (including a 55% stake in Torii Pharmaceutical): Sold to Shionogi on May 7, 2025. For further details: Beyond Nicotine: Japan Tobacco
Top-line & Bottom-line Results – Tobacco Segment Only1
(Excluding Pharmaceuticals and Processed Food Segments. Tobacco Segment has a 89% weight in revenue and 98% weight in adjusted operating companies income in Q1 2025. Adjusted figures, at constant currencies)
Revenue: +14.0% in Q1 2025, driven by strong pricing/mix, the inclusion of Vector Group and RRP-related revenue growth (+11.3%)
Operating profit: +20.9% in Q1 2025, driven by core revenue growth and partially offset by higher investments towards heated tobacco and higher supply chain costs
Total Volume: -1.3% (up +0.2% when adjusted for inventory movements); Combustible volume: -1.7%; RRP volume: +19% (heated tobacco volume: +27.7%)
RRP weight – Q1 2025: 2.2% by volume and 3.6% by revenue

RRPs: Ploom X (heated tobacco)
– A new & improved Ploom device and premium blend heated tobacco stick ecosystem will be presented at the launch event on May 27, 2025. Japan will be the first launch market
– Japan: Category reached 46.1% of the total tobacco industry size (on shipment basis). JT’s RRP volume (including hybrid products) increased by +19.3% and category share grew by +1.3ppt to reach 14.8%. JT’s heated tobacco volume grew by +26.7% and category share grew by +1.8ppt to reach 12.7%.

– In 13 markets where Ploom has at least 12 months of presence, Ploom’s Share of Segment (SoS) is up (+3.6pp) from 4.6% in December 2022 to 8.2% in February 2025. Outisde Japan, Ploom’s SoS varies from 1.5% in Italy to 6.1% in Czechia. On track to reach mid-teens heated tobacco SoS by 2028 with further acceleration through the launch of the new Ploom ecosystem

Regional Overview: Volume, Core Revenue (CR), Adjusted Operating Profit (AOP)
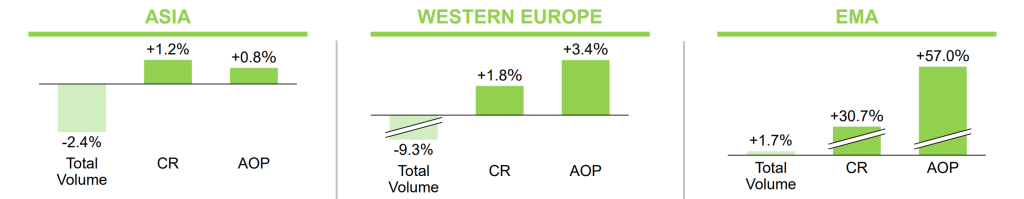
– Asia: Lower combustibles industry volume in Japan, the Philippines and Taiwan. Combustible market share gains mainly in Taiwan. Pricing contribution, mainly in the Philippines
– Western Europe: Lower combustibles industry volume, including in the UK, and unfavorable inventory movements. Market share gains in several markets (UK, Romania, Spain). Pricing contribution, in several markets such as Italy and the UK
– EMA: Inclusion of Vector Group. On-going growth in Global Travel Retail. More resilient industry volume across several markets and market share growth (Russia, Turkey). Pricing contribution in many markets
– US Market (including Vector): 2.8 billion sticks volume and 8.3% SoM (Montego: 4.4%, L&D: 2.4%)
Our Recollection
Overall, strong combustible pricing/mix and contribution from Vector Group helped JT deliver double-digit revenue and operating profit growth in Q1 2025. As noted before, FY25 is set to be an another year of strong growth. JT’s traditional business (combustibles) is in good shape.
On the RRP side, thanks to the geographical expansion of Ploom X and progressive category share gains in Japan, year-on-year volume growth in heated tobacco accelerated to +27.7%. Nevertheless, it is yet to be seen whether the progress achieved in heated tobacco is in proportion to the outsized ¥450Bn ($2.9Bn) investment (over the three-year period from 2024 to 2026, mostly in commercial initiatives). With only 3.6% of its revenue coming from RRPs (compared to ~42% for PMI), JT still has a lot to do in terms of portfolio transformation. We will continue to closely watch Ploom X’s performance in the expansion markets (i.e. whether the segment share is progressively increasing towards the mid-teens).
JT shares are up around +10% in 2025 (+22% in US$ terms) and now trading around the key ¥4,500 level. A further move towards a new all-time high (around ¥4,800) is within the cards considering the renewed buying interest in tobacco stocks in general. The more JT can demonstrate that its outsized RRP investment is resulting in more sizable RRP franchise that complements its strength in the cigarette category (i.e. a more balanced & sustainable business mix), the higher is the upside for its share price.
References:

