


Tobacco Segment: 89% weight in revenue, 100+% weight in adjusted operating profit
Top-line & Bottom-line Results – Tobacco Segment Only1
Excluding Pharmaceuticals and Processed Food Segments; adjusted, at constant currencies
Revenue: +8.1% in Q3 2024, driven by positive pricing in multiple markets and RRP-related revenue growth (+9.8%), partially offset by product mix (downtrading) and volume decline in Asia and Western Europe clusters
Operating profit: +3.7% in Q3 2024, driven by core revenue growth and partially offset by higher investments towards heated tobacco and higher supply chain costs
Total Volume: +2.4% (combustible volume +2.1%; RRP volume +18.1%)
RRP weight – Q3 2024: 1.9% by volume and 3.4% by revenue (both lower than Q2 2024)
No sequential (quarter-on-quarter) growth in RRP volume and revenue
Note on FX: Unfavorable impact on operating profit driven by depreciation of emerging market currencies and appreciation of cost-related currencies more than offsetting the positive impact of a weaker JPY

RRPs: Ploom X (heated tobacco)
– RRP volume growth (18.1%), driven by continued momentum in Japan and increasing contributions from the other markets
– RRP volume contribution: 5.2Bn Japan + 0.7Bn other markets in YTD24 (still 88% Japan vs. 34% for PMI in FY23)
– Ploom X is now available in 23 markets, including the launches in Jordan and the Philippines in
Oct 2024. South Korea launch is set to take place in Nov 2024. Increase in RRP volume in overseas markets driven by the geographical expansion and continuous consumer & trade marketing activation in launch markets
– Japan: RRP category now makes up 42% of the total tobacco industry volume. Market share gains in an increasingly competitive market due to aggressive promotions and price reductions by competitors: Ploom volume increased by +32.7%, exceeding heated tobacco category growth rate. In YTD24, Japan Tobacco (JT)’s total category share reached 13.7% (i.e. 11.4% Ploom + 2.3% infused tobacco capsules). In Q3 2024, Ploom attained 11.8% category share.
– Other markets: Steady growth since the launch (fueled with expansion in distribution), reaching between 1.5% (Italy) and 4.4% (Czechia) segment share in different markets

Combustibles
– Combustibles volume growth (+2.1%) driven by the Global Flagship Brands (GFB), EMA cluster (mainly Russia and Turkey) and the emerging markets
– GBP volume: +4%, driven by Winston (+5%) and Camel (+9.5%)
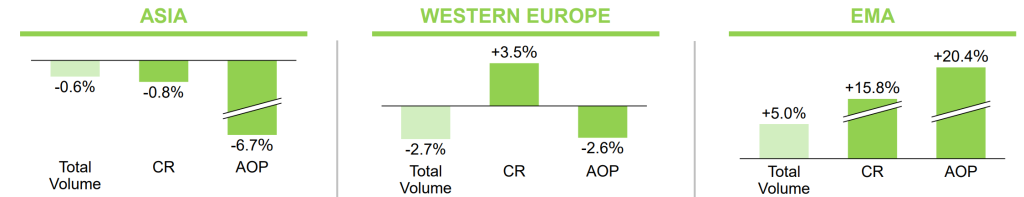
– EMA: Volume +5.0%, Core Revenue +15.8%, Adjusted Operating Profit +20.4%
– Resilient industry volume overall: Strong momentum in emerging markets and Global Travel Retail, mainly in Asia
– Continued combustibles industry volume decline in the UK (-15.6%, driven by the excise tax-led price increases), Japan, Taiwan and the Philippines => JT’s cluster volume decline: Asia -0.6%, Western Europe -2.7%
– Continued positive variance driven by pricing and total volume growth, partially offset by the impact of
negative product mix due to downtrading and unfavorable geographic mix
Vector Acquisition
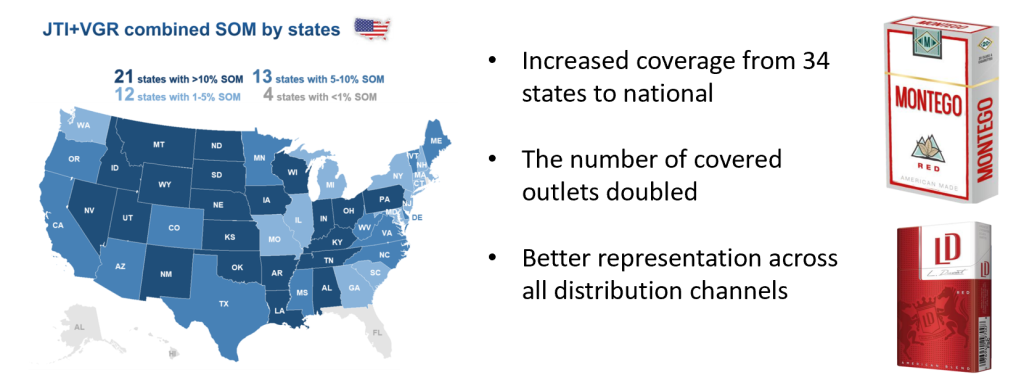
Following the completion of the Vector acquisition, JT becomes the 4th largest tobacco player in the US market with significantly stronger commercial span and geographic footprint. Strategic rationale behind the acquisition:
– Improves Return-On-Investment (ROI) in combustibles by increasing volume by ~9 billion sticks in one of the largest and most profitable tobacco markets in the world
– Strengthens JT Group’s financial position with larger hard currency levels resulting in stable profit and cash flow contributions on a mid to long term
– Expands JT Group’s presence in the US by increasing the US market share from 2.4% to 8.2%, improving competitiveness through an enlarged distribution network and getting full ownership of two of the top-10 US cigarette brands (Montego and LD; also two of the top-5 fastest growing brands since 2021)
– Our take: A stronger JT in the US will further aggravate the pressure on Altria and BAT. JT’s proven track record in growing combustible franchises (for instance, Winston and Camel in the international markets) is a significant threat to Altria and BAT in a market where the overall cigarette volume is declining by ~9% p.a. and consumers are irreversibly downtrading to discount brands (i.e. JT’s main playground in the US).
FY24 Forecast
– Consolidated revenue and operating profit forecasts revised up, both at the reported and constant FX level, reflecting the strong business momentum and Vector inclusion
– Profit forecast revised down to reflect negative impacts from financial costs and higher corporate tax in addition to Vector acquisition related costs. FCF revised down due to payments related to the acquisition of VGR in excess of positive operating profit revision
– Tobacco volume: revised up to “+1% growth” from “-0.5% to 1.0% decrease” vs. 2023
– Tobacco segment (at constant FX): both core revenue and adjusted operating profit +9.0%

– Basic EPS: ¥263. Based on the last close price (¥4,281), JT now trades at 16.3x 2024EPS (- below the 18x peak multiple reached in June 2024)
Our Recollection
Overall, combustible volume growth (+2.1%) combined with pricing/mix improvements helped deliver high-single digit (+8.1%) revenue and mid-single digit (+3.7%) operating profit growth in Q3 2024.
Thanks to the geographical expansion of Ploom X and progressive category share gains in Japan, year-on-year RRP volume growth accelerated: from only +8.2% in YTD23 to +22.8% in YTD24. Nevertheless, the progress achieved in heated tobacco doesn’t seem to be in proportion to the outsized ¥450Bn ($2.9Bn) investment (over the three-year period from 2024 to 2026, mostly in commercial initiatives). Lack of sequential quarterly growth in RRP volume & revenue and limited category shares attained in the expansion markets offer early signals of the difficulty faced by the JT to grow its Ploom franchise. We will continue to closely watch Ploom X’s performance in the expansion markets (i.e. whether the segment share is progressively increasing towards the mid-teens).
In February 2023, we noted: “In the League of Laggards to the transformation to RRPs (Altria, Imperial, JT), we clearly favor JT due its size/scale, higher emerging market exposure (supporting the combustible volume), very low indebtedness and strong focus on expanding its presence in the heated tobacco category”.
JT shares doubled since our call (i.e. correction from an overly undervalued level, further fueled by the general market interest in Japanese equities) and traded as high as ¥4,600 in June 2024. For further details: Japan Tobacco: Share Price Surge.
Following JT’s Q1 2024 results, we noted: “Although we still favor JT over Altria and Imperial Brands (in terms of business strength & growth), we need to underline that the strong price momentum – rather than the strength in business fundamentals – is driving the JT shares up at this stage (recall: JT now trades at a premium to the industry leader, PMI, despite RRPs having less than 4% weight in its total revenue)”. For further details: Japan Tobacco: Q1 2024 Results.
The long overdue correction in JT shares took place after our note above and JT shares lost the upward price momentum since June 2024. For further appreciation in the share price, JT needs to demonstrate that its outsized RRP investment will result in a more sizable RRP franchise that complements its strength in the cigarette category (i.e. a more balanced & sustainable business mix). Although JT’s Q3 2024 results are stronger than most of its peers, the progress achieved in RRPs are lukewarm at best.
References:

