


Q4 2023 & FY23 Results1
Revenue: ₩1.45Tn in Q4 (+3.2% year-on-year), ₩5.87Tn in FY23 (+0.4%)
EBITDA: ₩260.3Bn in Q4 (-0.6%), ₩1.41Tn in FY23 (-5.6%)
EBITDA Margin: 17.9% in Q4 (-0.7pp), 24.0% in FY23 (-1.5pp)
Operating Profit: ₩198.6Bn in Q4 (-1.4%), ₩1.17Tn in FY23 (-7.9%)
Net Income: ₩117.1Bn in Q4 (—), ₩926.6Bn in FY23 (-7.8%)
EPS: ₩1,105 in Q4 (—), ₩7,866 in FY23 (-7.3%)
2024 Outlook: 3 core businesses (Cigarettes, NGP and Health-Functional Food) expected to drive top and bottom line growth while cost headwinds persist
KT&G results are mostly in line with pre-earnings estimates of ₩1.43Tn revenue (slight beat) and ₩200Bn operating profit (slight miss). We expect the share price reaction to be muted. Based on the last closing price (₩90,000), KT&G trades at 11.4x reported FY23 EPS. Although KT&G associates the divergence between the revenue (+0.4%) and profit (-7.8%) performance with the persistent cost pressures, critics will mark 2023 as another year in which the revenue base is grown at the expense of profitability.
Results: Tobacco Division
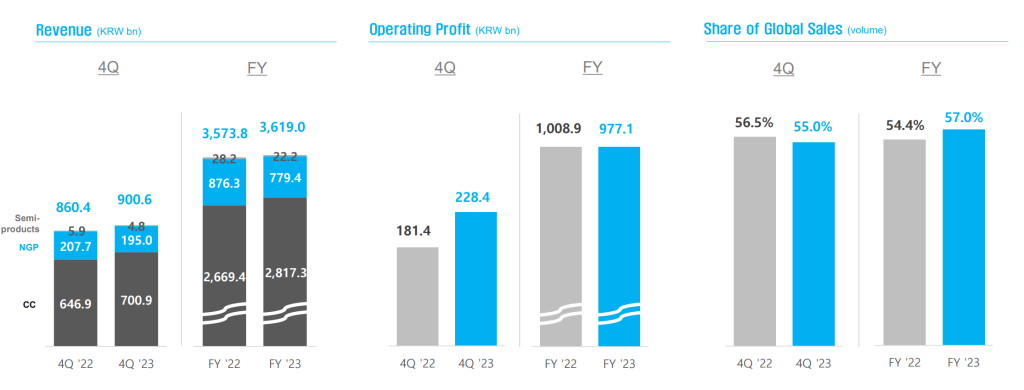
Key announcement highlights for FY23 (tobacco business only):
– Revenue +1.3% to ₩3.62Bn; Operating Profit -3.2% to ₩977Bn => Margin down 28.2% to 27%
– NGP revenue weight in total tobacco: down from 24.5% to 21.5% (due to the excessive amount of lil device shipments made to PMI in 2022)
– International (ex-Korea) revenue: now 57% of the total (+2.6pp)
– Conventional – Korea: -1.1% volume decline to 40.7Bn sticks due to the market contraction (down -2.1% to 61.6Bn sticks) and despite the SoM growth (up +0.6pp to 66%)
– Conventional – International: +7.7% volume growth (to 53.2 sticks) coupled with price/regional mix improvements leading to +12.8% year-on-year revenue growth. FY23 Indonesian volume: 12Bn sticks
Results: NGP Segment
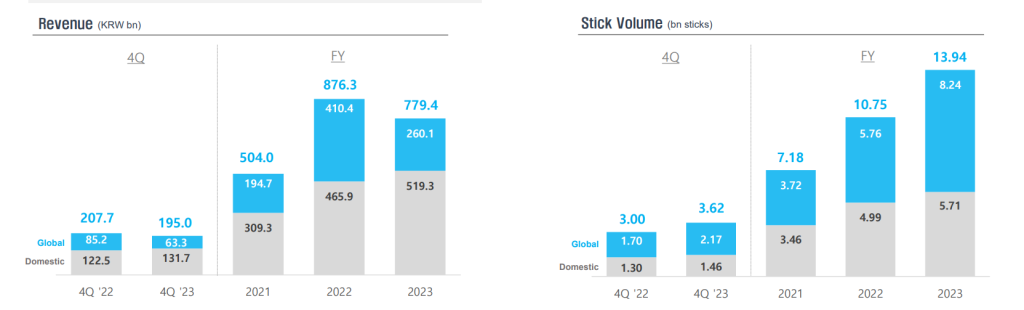
– NGP – Korea: Leadership is maintained, but SoS is down to 46.6% (-0.9pp) due to fiercer competition with more aggressive promotions and new device launches from competitors (e.g. IQOS ILUMA). Volume is up +14.4% to 5.7Bn sticks; revenue is up +11.5%. Aims to improve competitiveness with the nationwide launch of lil Hybrid 3.0 despite the aggressive promotions of PMI and BAT.
– NGP – International (Global Partnership with PMI): Revenue is down -36.6% due to the excessive amount of devices shipped last year and despite +43% growth in consumable volume (to 8.2Bn sticks).
– Overall NGP volume: 13.9Bn sticks in FY23.
KT&G continues to be the world’s 5th largest tobacco company with ~108Bn shipment volume (note: Imperial Brands is 4th-placed with 198Bn sticks). ~14Bn annual NGP/HTP volume (12.9% weight in overall volume) makes KT&G the third largest heated tobacco franchise in the Industry (after PMI & BAT).
References:

