


Q4 2024 & FY24 Results1
Revenue: ₩1.56Tn in Q4 (+8.0% year-on-year), ₩5.91Tn in FY24 (+0.8%)
EBITDA: ₩272.8Bn in Q4 (+5.0%), ₩1.435Tn in FY24 (+1.9%)
EBITDA Margin: 17.5% in Q4 (-0.5pp), 24.3% in FY24 (+0.3pp)
Operating Profit: ₩208.5Bn in Q4 (+5.3%), ₩1.18Tn in FY24 (+1.5%)
Net Income: ₩301.7Bn in Q4 (+167.2%), ₩1,141.6Bn in FY23 (+23.8%)
EPS: ₩2,696 in Q4 (+152.7%), ₩10,167 in FY24 (+29.6%)
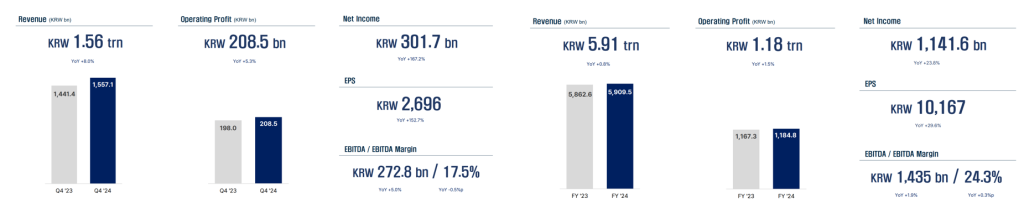
2025 Outlook: Revenue growth of 5%-7%; Operating Profit growth of 6%-8%
Results: Tobacco Division
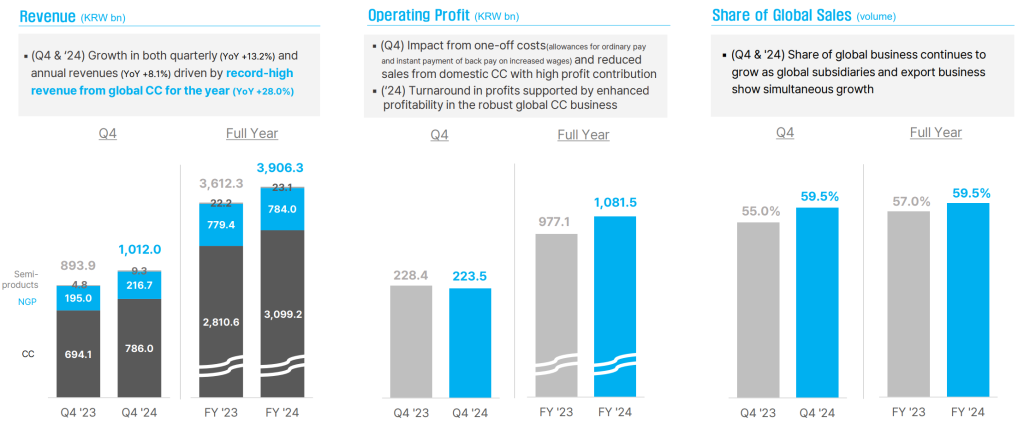
– Revenue +8.1% to ₩3.91Tn; Operating Profit +10.7% to ₩1,081.5Bn => Margin up from 27% to 27.7% in FY24 (yet, down from 25.6% to 22.1% in Q4 2024). Bottom-line turnaround supported by the enhanced profitability in the international combustible division
– Growth in Q4 2024 (+13.2%) and FY24 revenue (+8.1%) driven by record-high revenue from international combustible division (+28.0% in FY24). 2024
– Q4 2024 operating profit adversely affected by the one-off costs (allowances for ordinary pay and instant payment of back pay on increased wages) and reduced cigarette sales in S. Korea (with high profit contribution)
– Share of international business (ex-Korea) reaches 59.5%
– NGP revenue weight in total tobacco: down from 24.5% in FY22 to 21.5% in FY23 and 20.1% in FY24 – mostly, due to the excessive amount of lil device shipments made to Philip Morris International (PMI) in 2022
– Conventional – Korea: Q4 2024 and FY24 volume down by -3.4% and -2.9%, respectively (FY24 volume: 39.5 billion sticks). Annual revenue down -1.7% despite continued market share gain (+0.7pp to 66.7%) and increased contribution from high-ASP (average selling price) products. Visible acceleration in cigarette volume decline
– Conventional – International: Revenue growth (+35.2% in Q4 2024 and +28% in FY24) driven by the exponential growth in high-ASP export volumes (+45.3% in Q4 2024) and active pricing strategies. Q4 2024 and FY24 volume up +21.4% and +10.3%, respectively (FY24 volume: 58.6 billion sticks). FY24 Indonesian volume: 14.2Bn sticks (+18.3%)
Results: NGP Segment
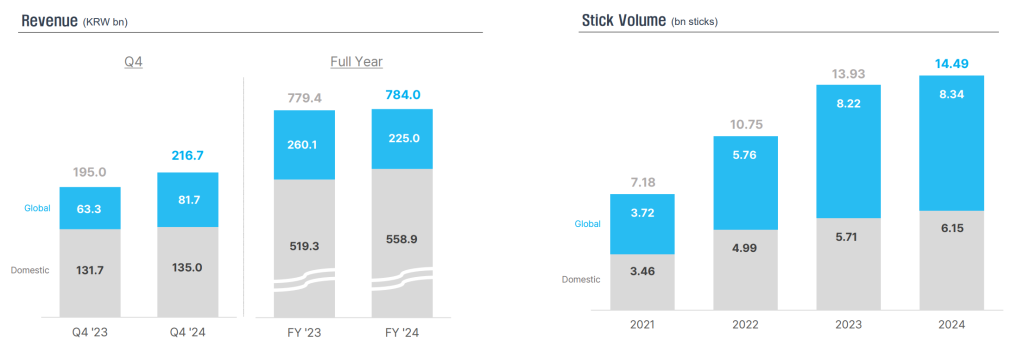
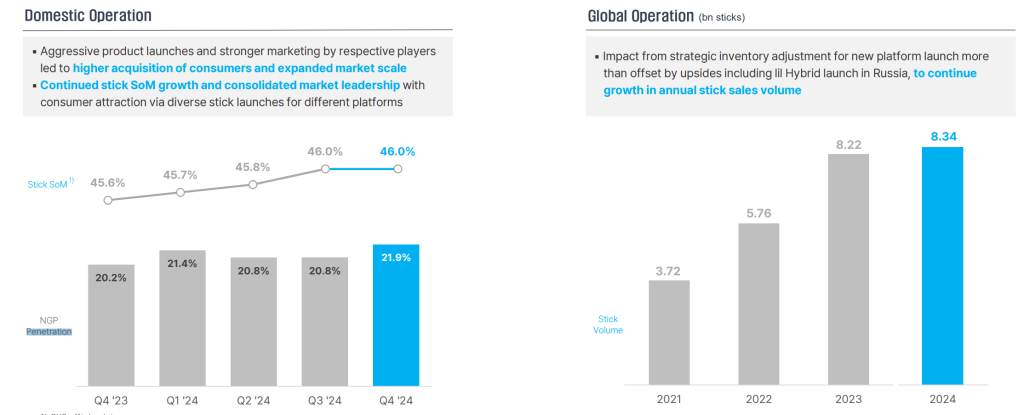
– NGP – Korea: Leadership is maintained with consumer attraction via diverse stick launches for different platforms, but SoS flat to 46.0%. Volume is up +7.7% to 6.15Bn sticks; revenue is up +7.6%. NGP penetration reaches 21.9% (+1.7pp, although the quarter-on-quarter progression of the penetration is not linear). Aggressive product launches and marketing investment by the competition (PMI, BAT and Japan Tobacco).
– NGP – International (Global Partnership with PMI): Revenue is down another -13.5% in FY24 (i.e. down -36.6% in FY23) despite +1.5% growth in consumable volume (to 8.3Bn sticks). Impact from strategic inventory adjustment for new platform launch more than offset by upsides including lil Hybrid launch in Russia.
Shareholder returns
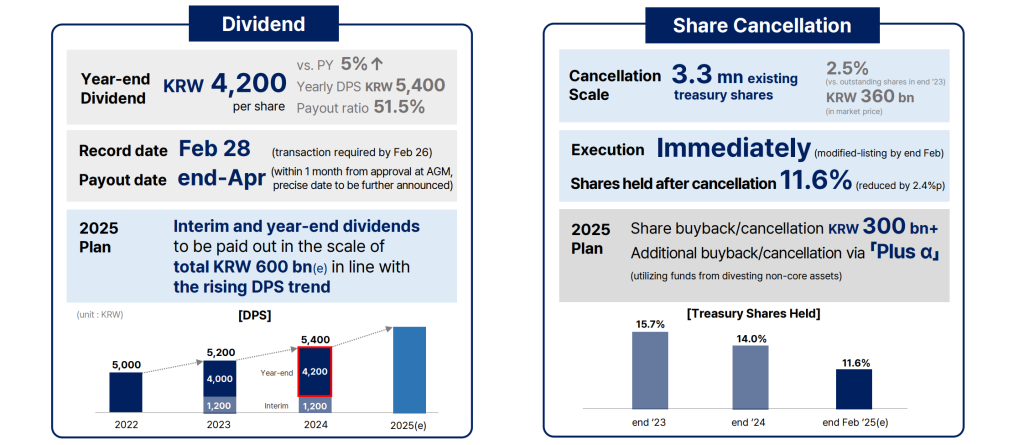
– Year-end dividend increase by 5% to ₩4,200 => annual dividend: ₩5,400 (4.95% yield based on the last close price of ₩109,200; payout ratio: 51.5%)
– ₩600Bn to be paid in dividends in 2025 (in two tranches: interim and year-end)
– 3.3 million shares (2.5% of the share capital; ₩360Bn in market value) to be cancelled
– More than ₩300Bn share buyback in 2025 (additional buybacks utilizing funds from the divestiture of non-core assets)
Summary
KT&G made good progress towards a profitability-oriented financial delivery in FY24. For the first time in four years, KT&G’s operating profit increased – albeit only by low single-digit (+1.5%). Moreover, ₩1.18 trillion operating profit delivered in FY24 is still 30% below the FY20 figure (₩1.48 trillion). Stellar international cigarette performance and maintained leadership in the highly competitive South Korean RRP market are the main 2024 business highlights. However, acceleration of the decline in the key South Korean cigarette market (i.e. 42% of the total tobacco revenue) and limited contribution from the global NGP partnership with PMI are sources of concern. +1.5% annual volume increase and -13.5% annual revenue decline from NGP International is far from the guidance communicated at the time of the 15-year PMI partnership extension.
Trading at an undemanding 10.7x P/E multiple and set to deliver more than ₩1.1 trillion to its shareholders in 2025, KT&G has limited downside at the current price level. Nevertheless, the valuation upside depends on the market conviction about KT&G’s turnaround to “profitable growth”. In that regards, a more meaningful contribution from the global NGP partnership from PMI is key to the improved bottom-line delivery.
Profile: KT&G is the world’s 5th largest tobacco company with 112.6Bn shipment volume (note: Imperial Brands is 4th-placed with 190Bn sticks). KT&G the third largest RRP/NGP franchise in the Industry (after PMI & BAT) with 14.5Bn annual volume (12.9% weight in overall volume).
References:

