


Q4 2025 & FY25 Results1
Revenue: ₩1.71Tn in Q4 (+10.1% year-on-year), ₩6.58Tn in FY25 (+11.4%)
EBITDA: ₩325.8Bn in Q4 (+17.7%), ₩1.64Tn in FY25 (+14.1%)
EBITDA Margin: 19% in Q4 (+1.2pp), 24.9% in FY25 (+0.5pp)
Operating Profit: ₩248.8Bn in Q4 (+17.1%), ₩1.35Tn in FY25 (+13.5%)
Net Income: ₩274.2Bn in Q4 (-15.3%), ₩1.09Bn in FY24 (-6.1%)
EPS: ₩2,472 in Q4 (-15.3%), ₩10,143 in FY25 (-3.0%)

Results: Tobacco Division
– Revenue +11.8% to ₩4.37Tn; Operating Profit +6.7% to ₩1.157Tn => Margin down from 27.7% to 26.5% in FY25s. Margin negatively affected by geographical mix (i.e. reduced contribution from South Korea), input cost pressures and one-off items
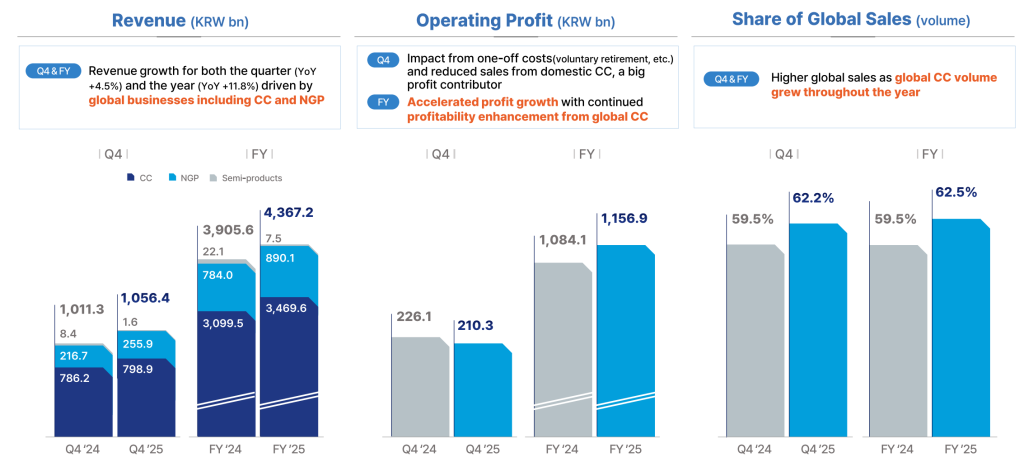
– Share of international business (ex-Korea) reaches 62.5% (+3pp)
– NGP revenue weight in total tobacco: 20.4% in FY25 (+0.3pp). Record high was 24.5% in FY22 – mostly, due to the excessive amount of lil device shipments made to Philip Morris International (PMI) in 2022
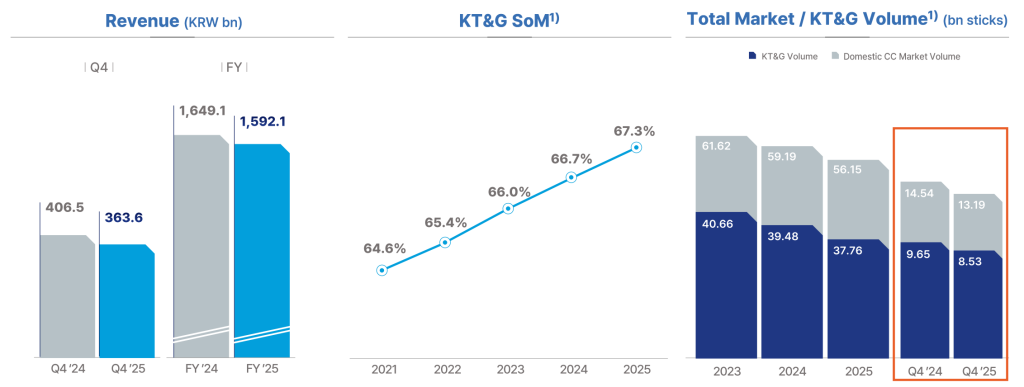
– Conventional – Korea: Q4 2025 volume down by -11.6% due to the demand shifted to Q3 2025 in preparation of the Chuseok holiday. Annual volume (FY25: 37.8 billion) and revenue down -4.4% and -3.5%, respectively, despite continued market share gain (+0.6pp to 67.3%) and differentiated new product launches. Visible acceleration in cigarette volume decline.
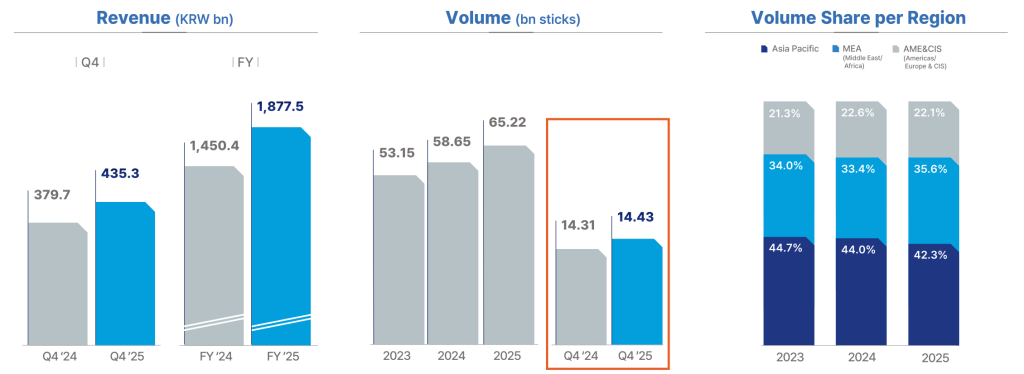
– Conventional – International: Q4 2025 revenue growth (+14.6%) driven mainly by double-digit ASP (+13.7%) increase amid sluggish volume growth (+0.8%). FY25 volume up +11.2% to 65.2 billion sticks. FY25 revenue (+29.4%) and operating profit (+53.8%) growth fueled by double-digit ASP increase (+16.4%) alongside the volume growth
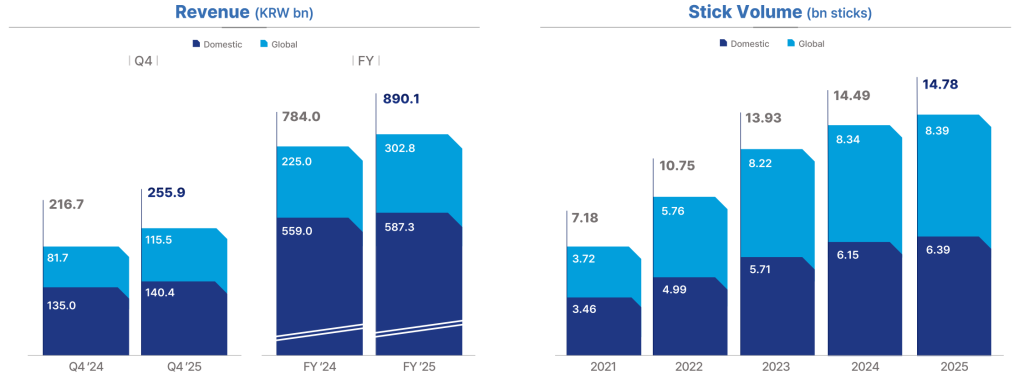
– NGP – Korea: Leadership is maintained with 46% category share (+0.1pp) despite intensifying competition. Volume is up +3.9% to 6.39Bn sticks; revenue is up +5.1%. NGP penetration reaches 23.5% in Q4 2025 and 22.8% in FY25 (+1.6pp)
– NGP – International (Global Partnership with PMI): Revenue is up +34.6% in FY25 despite only +0.6% growth in consumable volume (to 8.39Bn sticks). Revenue growth is presumably driven by device shipments
Health Functional Food
– FY25 revenue down 12.6% to ₩1.137Tn while operating profit is up +4.7% to ₩102.8Bn. Margin up 1.5pp to 9%. Share of global sales: down 6.7pp to 22.2% due to reduced revenue from Greater China
– Amid declining demand and high consumer prices, strategic re-orientation towards profitable channels and products – driving lower revenue, but higher operating margin
Real Estate
– FY25 revenue up +97% to ₩713Bn, driven by stronger earnings from mid-to-small sized projects and one-time earning recognition for Seocho project
– Return to operating profit (from ₩4.9Bn loss in FY24 to ₩81.6Bn profit in FY25) with reduced infrastructure costs for Suwon
2026 Outlook: Revenue growth of 3%-5%; Operating Profit growth of 6%-8%
Shareholder returns
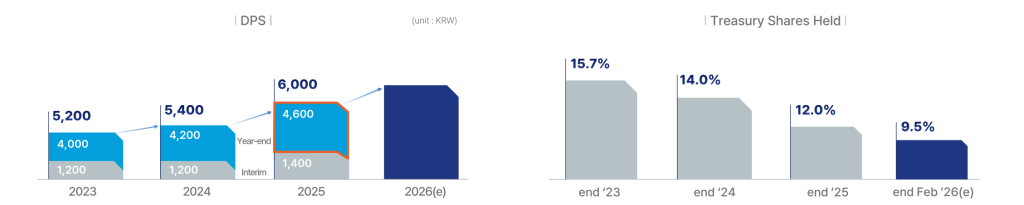
– Year-end dividend increase by 9.5% to ₩4,600 => annual dividend: ₩6,000 (+11.1% annual increase; 3.7% yield based on the last close price of ₩161,800; payout ratio: 59%)
– Treasury shares held: 12% of the share capital (to be reduced to 9.5% at the end of Feb 2026)
– More than ₩300Bn share buyback and cancellation planned in 2026 (additional buybacks utilizing funds from the divestiture of non-core assets)
Summary
KT&G made good progress towards a sustainable, profitable growth path (revenue: +11.8%) in FY25 with EBITDA margin expansion (+0.5pp) despite unfavorable geographical mix (i.e. declining weight of South Korea). Stellar international cigarette performance and maintained leadership in the highly competitive South Korean RRP market are the main highlights of 2025. On the flip side, acceleration of the decline in the key South Korean cigarette market (i.e. 36.5% of the total tobacco revenue) and sluggish RRP volume growth (+0.6%) in the international markets are sources of concern.
Profile: KT&G is the world’s 5th largest tobacco company with 117.8 billion sticks shipment volume (note: Imperial Brands is 4th-placed with 186.9 billion sticks). KT&G has the third largest RRP/NGP franchise in the Industry (after PMI & BAT) with 14.8 billion annual volume (12.6% weight in overall volume).
Download KT&G Q4 2025 & FY25 Results
References:

