


Q1 2025 Results1
“Solid financial delivery, driven solely by the international cigarette division. Problems persist elsewhere ”
Revenue: ₩1.49 trillion (+15.4% year-on-year) => record-high quarterly revenue from international cigarette segment (+23.3% volume growth, +53.9% revenue growth)
EBITDA: ₩354.3 billion (+19.1%)
EBITDA Margin: 23.8% (+0.8pp)
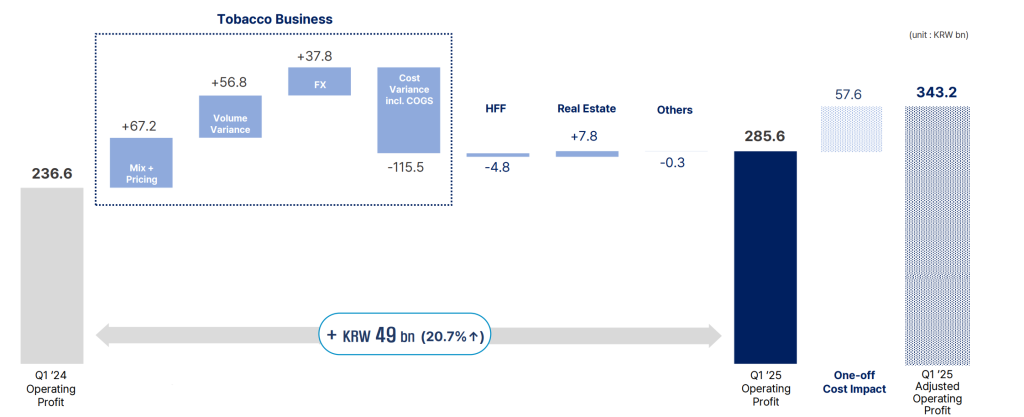
Operating Profit: ₩285.6 billion (+20.7%; adjusted for one-off items: +45.1%)
Net Income: ₩257.9 billion (-9.7%)
EPS: ₩2,370 (-4.7%)
Results: Tobacco Division
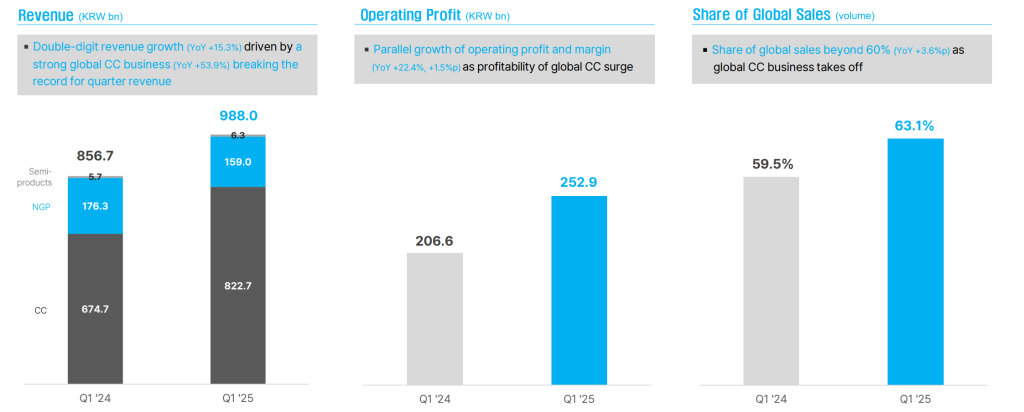
Key announcement highlights for Q1 2024 (tobacco business only):
– Revenue +15.3% to ₩988 billion; Operating Profit +22.4% to ₩252.9 billion => Margin up from 24.1% to 25.6% (+1.5pp)
– Overall volume +9.4% to 27.8Bn sticks (cigarettes +11.5% to 24.4Bn sticks)
– NGP revenue weight in total tobacco: down from 20.6% to 16.1% (due to the re-adjustment of the excessive lil device inventory built in the international markets)
– International (ex-Korea) revenue: 63.1% of the total (+3.6pp)
– Cigarettes – Korea (37.8% weight in tobacco revenue): -4.8% volume decline to 8.74Bn sticks due to the market contraction (-8.2%) and despite the SoM gains (up +2.4pp to 68.4%). Revenue down -2.4% with pricing only partially offsetting volume decline
– Cigarettes – International (45.5% weight in tobacco revenue): +23.3% volume growth (to 15.67Bn sticks). Revenue up +53.9%, driven by strong pricing and improved product mix in addition to the volume growth.
Results: NGP Segment
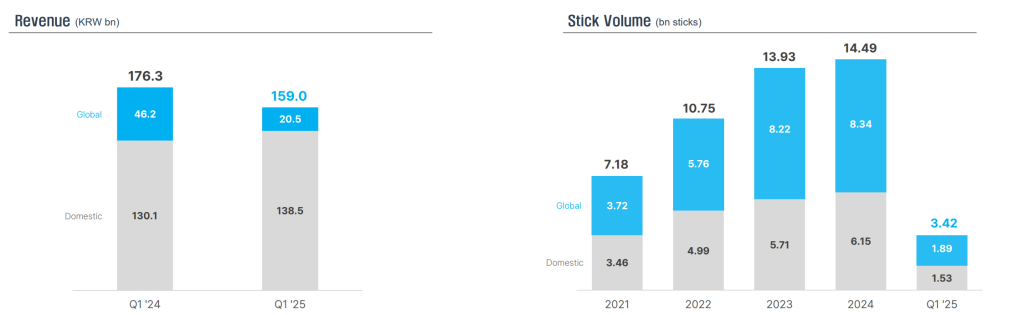
– Overall NGP volume: -3.4% to 3.42Bn sticks in Q1 2025
– NGP – Korea (14% weight in tobacco revenue): Leadership is maintained with 46% SoS (+0.3pp) despite fierce competition (e.g. more aggressive promotions offered by PMI and BAT) and device supply disruption. Volume is up +7% (to 1.53Bn sticks), revenue is up +6.5%. NGP Penetration: 23.2% of the total market (+1.8pp)
– NGP – International (2.1% weight in tobacco revenue, Global Partnership with Philip Morris International): Revenue is down -55.6% lower due to the lower tobacco stick volume (i.e. existing devices becoming outdated) and the impact from device supply disruption. Volume is down -10.4% (to 1.89Bn sticks)
Health-Functional Food (HFF) division:
– Co-CEO system is introduced: domesic focus on improving profitability via channel and product restructuring vs. international focus on fostering localized brands and accelerating expansion. International has 21.4% weight in total HFF revenue (+0.9pp)
– Revenue: up +1.9% to ₩314.4 billion as the impact of a slow economy was more than offset by the Lunar New Year promotion and higher sales from key overseas markets
– Operating profit: down -20.9% to ₩18.2 billion due to higher marketing expenses to revitalize forward domestic demand despite improved profitability in the global business
Summary:
KT&G delivered an impressive double-digit revenue and operating profit growth in Q1 2025, almost solely thanks to the great volume & pricing performance of the international cigarette division. However, problems persist elsewhere. Acceleration in domestic cigarette volume decline (-8.2%) is one concern. Intensifying competition in domestic NGP business is another concern. Most recently, KT&G was forced to reduce the RSP of 8 fiit heated tobacco sticks by ₩200 in the domestic market. But, above and beyond all, the Global Partnership with Philip Morris International is of major concern. Every quarter, we are hearing a new excuse: this time, it is the supply chain distruption that is delaying the device replacement cycle. Whatever the excuse is, ₩20.5 billion (less than $15 million) quarterly revenue from the global lil franchise is beyond miserable.
References:

