


Q3 2024 Results1
Revenue: ₩1.64Tn (-3.1% year-on-year)
EBITDA: ₩479.2Bn (+2.5%); EBITDA Margin: 29.3% (+1.6pp)
Operating Profit: ₩415.7Bn (+2.2%)
Net Income: ₩239.9Bn (-28.0%); EPS: ₩2,251(-16.9%)
Shareholder returns: KT&G announces an upgraded Corporate Value-up Plan which aims to achieve 15% ROE by 2027 and return ₩3.7 trillion to shareholders through 2027 – in the form of share repurchases (₩1.3 trillion, including the ₩150 billion already spent in 2024) and dividends (₩2.4 trillion). Share repurchases from Nov 2024 to 2027 will represent about 20% of the outstanding shares as of the end of 2023.
Results: Tobacco Division
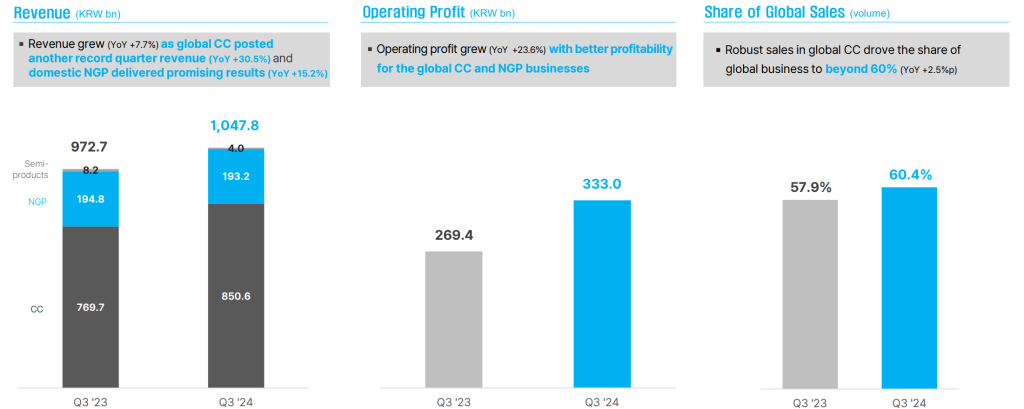
Key announcement highlights for Q3 2024 (tobacco business only):
– Revenue +7.7% to ₩1,047.8Bn; first-ever ₩1 trillion quarterly revenue
– Operating Profit +23.6% to ₩333Bn => Margin up from 27.7% to 31.8%
– Record-high quarterly revenue driven by the growth of international cigarette (+30.5%) and domestic NGP (+15.2%) businesses
– Cigarette volume up +3.9% to 26.65Bn sticks, driven by the growth in international markets
– NGP revenue weight in total tobacco: down from 20% to 18.4%
– International (ex-Korea) revenue: 60.4% of the total (+2.5pp); above the 60% mark for the first time
– Conventional – Korea: -4.5% volume decline to 10.33Bn sticks due to the market contraction and despite the SoM growth (up +0.6pp to 67.4%)
– Conventional – International: Growth Trifecta (volume – revenue – profit) and record-high quarterly revenue. +10.1% volume growth (to 16.32Bn sticks) coupled with +30.5% revenue growth and +167.2% operating profit growth
Results: NGP Segment
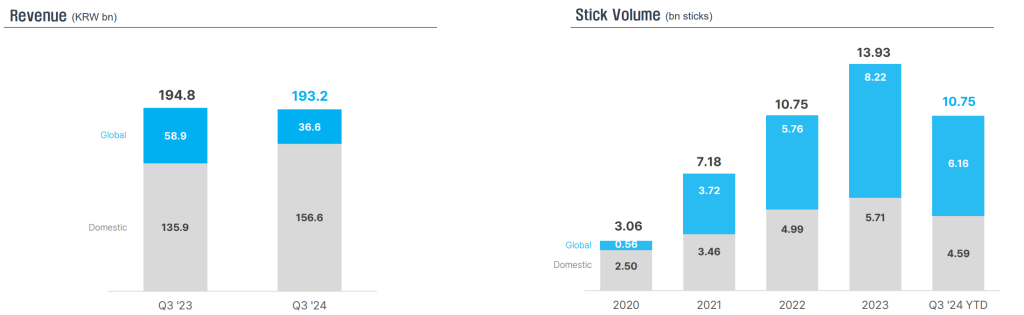
– Overall NGP volume: +1.4% to 3.53Bn sticks in Q3 2024
– Overall NGP revenue: down -0.8% in Q3 2024 (Korea: +15.2%, international: -37.9%)
– NGP – Korea: Leadership is maintained with SoS is flattish around 46% (+0.1pp year-on-year basis), supported by the improved competitiveness of lil Hybrid platform despite intensifying competition. Volume is up +12.4% (to 1.63Bn sticks), revenue is up +15.2%.
– NGP – International (Global Partnership with PMI): Volume is down -6.4%. Revenue is down -37.9% due to the strategic sales adjustment of devices in preparation for new platform launch overseas and lower consumable volume. Operating profit improves as the sales of NGP sticks, the main source of profit in the business, continue to grow => volume growth (+1.8% in YTD24) is significantly below the target communicated during the extension of the global partnership agreement with PMI (i.e. “20% annual growth aimed in NGPs over the next 15 years”). Moreover, lower-than-expected international NGP volume growth resurfaces the concerns about the “Global Partnership with PMI”.
Summary:
Overall, KT&G’s Q3 2024 results (-3.1% revenue, +2.2% operating profit) are mediocre: neither as good as the Q2 2024 results (+6.6% revenue, +30.6% operating profit) nor as bad as the Q1 2024 results (-7.7% revenue, -25.2% operating profit). Exceptional performance in the international cigarette segment, supported by the strong delivery in domestic NGP segment and Health-Functional Food (HFF) segment in China, more than offset the collapse in the Real Estate business and weak operating performance in the domestic HFF, domestic cigarette and international NGP segments. Yet, Market is likely to focus on the strong performance in the core tobacco business (+7.7% revenue, +23.6% operating profit) and offer time & space to the new CEO to make the strategic inventions needed in the non-core businesses.
Nevertheless, international NGP business remains as a sore spot in the Tobacco unit. Following the Q2 2024 earnings results, we noted that: “The Q2 2024 volume [in the international NGP segment] decline is hidden in the earnings release and weakness is solely attributed to the new platform launch preparation. In the upcoming coming quarters, we will continue to keep an eye on two points: (1) the financial return from the PMI partnership, (2) global heated tobacco slow-down”. Q3 2024 results further aggravated our concerns.
International NGP business is critical for KT&G to catch a new wave of concurrent volume – revenue – profit growth (even beyond what the “stellar” international cigarette segment currently delivers) and uplift its business scale to a new level in terms of financial delivery. The path to a valuation re-rating (i.e. P/E from low-teens to high-teens) for KT&G goes through success in international expansion with NGPs.
References:

