


Q3 2025 Results1
“Double-digit revenue and operating profit growth, mainly driven by the international cigarette division”s
Revenue: ₩1.83 trillion (+11.6% year-on-year) => record-high quarterly revenue, driven by international cigarette segment and higher real estate development income
EBITDA: ₩540.5 billion (+12.3%); EBITDA Margin: 29.6% (+0.2pp)
Operating Profit: ₩465.3 billion (+11.4%), driven by volume growth and price/mix improvement in tobacco business, partially offset by the negative cost variance
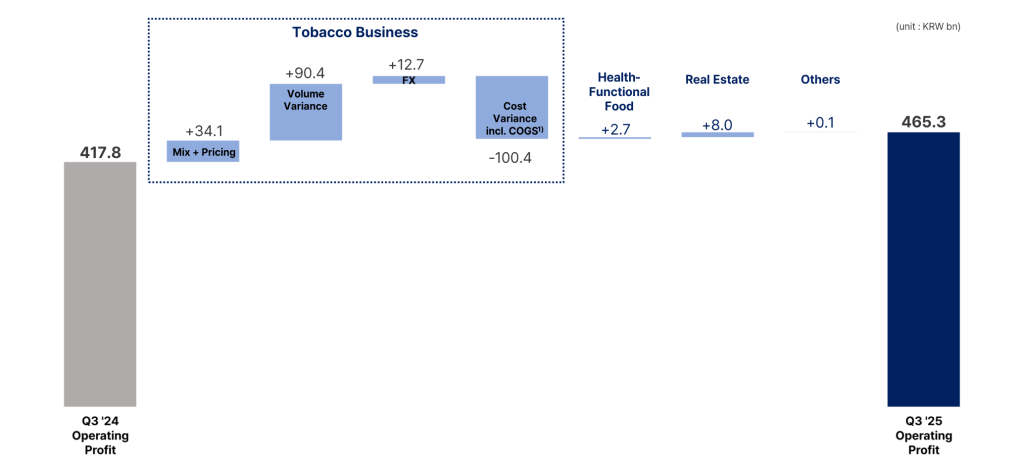
Net Income: ₩418.7 billion (+73.4%); EPS: ₩3,898 (+81.7%)
FY25 Guidance: Raised to double-digit revenue and operating profit growth
Results: Tobacco Division
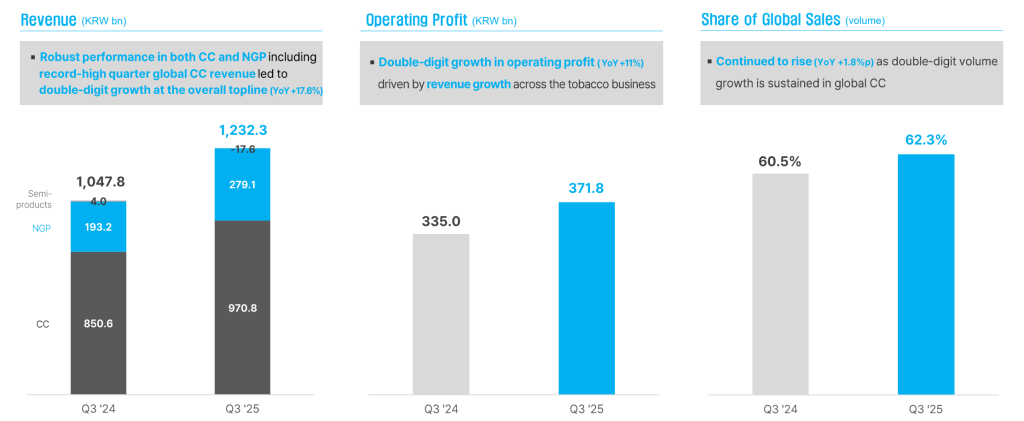
Key announcement highlights for Q3 2025 (tobacco business only):
– Revenue +17.6% to ₩1,232 billion; Operating Profit +11% to ₩371.8 billion => Margin down from 32% to 30.2% (-1.8pp), driven by the increasing weight of international business with lower margin compared to domestic
– Overall volume +9.6% to 33.15Bn sticks (cigarettes +9.2% to 29.11Bn sticks)
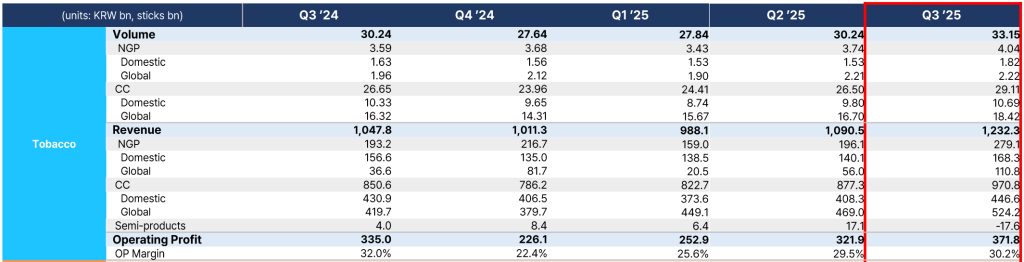
– NGP revenue weight in total tobacco: up from 18.4% to 21.1% (impacted by the device supply distruption in the beginning of 2025)
– International (ex-Korea) volume weight: 62.3% of the total (+1.8pp)
– Cigarettes – Korea (36.2% weight in tobacco revenue): volume up +3.5% to 10.69Bn sticks while the market volume is up +1.3%, driven advanced demand from the Chuseok holiday. KT&G SoM up +1.5pp to 68.9% in Q3 2025 (YTD SoM: 68.1%). Revenue up +3.6% => pricing/mix flattish (+0.1%)
– Cigarettes – International (42.5% weight in tobacco revenue): +12.9% volume growth (to 18.42Bn sticks). Revenue up +24.9%, driven by strong pricing and improved product mix in addition to the volume growth. Quarterly revenue above ₩500 billion for the first time
Results: NGP Segment
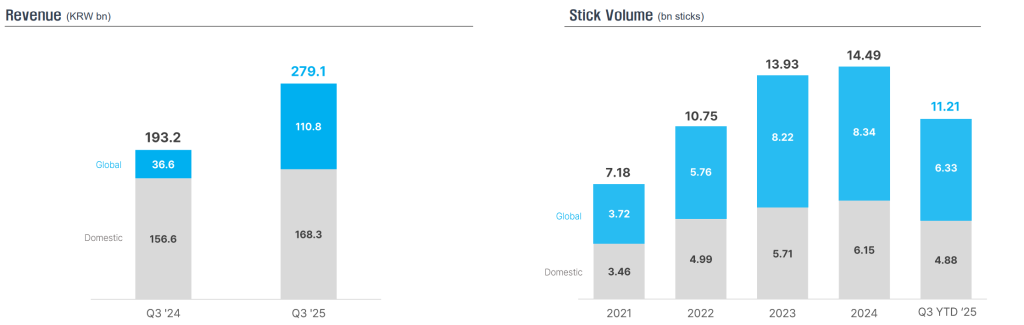
– Overall NGP volume: +12.5% to 4.04Bn sticks in Q3 2025
– NGP – Korea (13.7% weight in tobacco revenue): Leadership is maintained with 45.8% SoS (unchanged) in YTD25 through new product launches and despite fierce competition (e.g. more aggressive promotions offered by PMI, BAT and JT). Volume is up +11.7% to 1.82Bn sticks, revenue is up +7.5%. NGP Penetration: 22.6% of the total market YTD25 (+1.6pp)
– NGP – International (9% weight in tobacco revenue, Global Partnership with Philip Morris International): Revenue is up +203% driven by the launch of upgraded lil Solid in Russia and device inventory replenishment postponed from H1 2025 (due to device supply disruption). Volume is up +13.3% (to 2.22Bn sticks)
Others divisions:
– Health-Functional Food: Revenue down -11.3% to ₩359.8 billion due to the subdued consumer sentiment and price pressure as well as the portfolio realignment towards channels/products with higher margin; Operating profit up +3.9% to ₩71.5billion
– Real Estate: Revenue up +48.3% to ₩146.1 billion as construction progresses on development projects (i.e. leading to higher revenue recognition); Operating profit up +63% to ₩20.7billion
Summary:
KT&G delivered an impressive 11%-12% revenue and operating profit growth in Q3 2025, mostly thanks to the great volume/pricing/revenue performance of the international cigarette division as well as the increased lil device shipment to PMI. Presssure on the domestic tobacco subsided in the quarter as the market share gains and timing of shipments provided support to the volume. Nevertheless, we will continue to keep an eye on the acceleration in the underlying cigarette demand decline and intensifying competition in NGPs. The Global Partnership with Philip Morris International is still a concern despite a revenue surge driven by the device shipment. Consumable volume growth (13.3%) is better than the previous quarters and slightly ahead of the global category growth; nevertheless, lil revenue in South Korea alone in 2.4x its international revenue in YTD25.
Just below the ₩140,000 mark (all-time high: ₩149,400), KT&G now trades at 14x FY25 EPS of ₩9,800. A further re-rating to 20x is possible and a share price of ₩200,000 are within, depending on the stabilization of the South Korean tobacco market, continuation of successful international expansion with cigarettes and better volume/revenue delivery from the Global Partnership with Philip Morris International (i.e. lil outside South Korea).
References:

