


Release date: February 6, 2025 (NYSE, before the bell)
Key Business Metrics: Q4 20241
Revenue: up +7.3% to $9.71 billion (vs. $9.44 billion expected, $9.05 billion in Q4 2023)
Adjusted diluted EPS: up +14.0% to $1.55 (vs. $1.50 expected, $1.36 in Q4 2023)
Total volume: up +2.9% to 193.1 billion (heated tobacco volume: +5.1% to 35.7 billion; oral nicotine volume: +22.0% to 4.6 billion; cigarette volume: +1.1% to 152.8 billion)
Smoke-free weight: 40% by revenue, ~42% by gross profit, 20.9% by volume
Smoke-free business (SFB): More than 40 billion quarterly shipment for the first time. Available in 95 markets. 38.6 million users (up by +5.3 million vs. December 2023)

Key Business Metrics: FY24
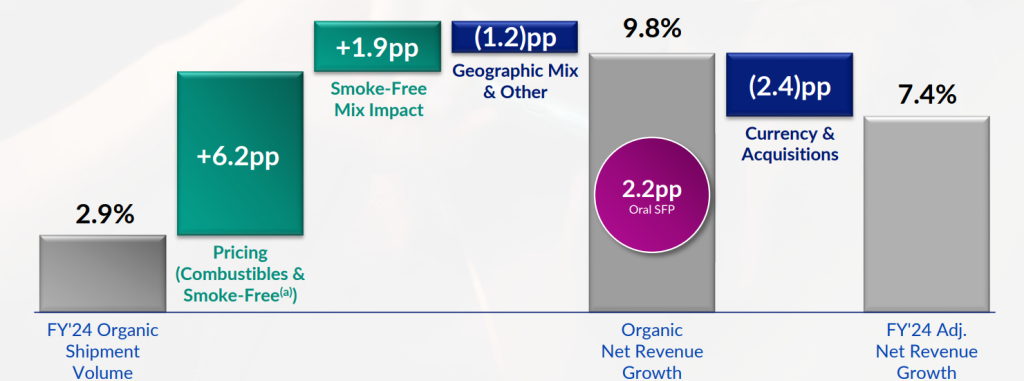
Revenue: up +9.8% on an organic basis to $37.9 billion (vs. $35.25 Bn in FY23; latest guidance: net organic revenue growth of +9.5%)
Adjusted EPS: up +9.3% to $6.57 and +15.6% to $6.95, ex-FX (vs. $6.01 in FY23; latest guidance: $6.85-$6.91, representing a growth of 14%-15%)
Total volume: up +2.9% to 774 billion (heated tobacco volume: +11.6% to 139.7 billion; oral nicotine volume: +24.6% to 17.4 billion; cigarette volume: +0.6% to 616.8 billion); fourth consecutive year of total volume growth
Smoke-free weight: 39% by revenue, 39.5% by gross profit, 20.3% by volume

Key Highlights
– International industry volume, ex-China & US, increased by +1.5% to 2.6 trillion units (cigarettes & HnB)
Heated Tobacco: Over 75% of global category volume share
– IQOS as the second largest nicotine brand in markets where present (+0.7pp share in Q4 2024)
– In-market sales (IMS) volume up +12.6% in FY24 with an acceleration to ~14% in H2 2024 and to ~13% in Q4 2024
– Japan: ILUMA i fuels IQOS growth with adj. IMS up by ~13% in both Q4 2024 and FY24 (9th consecutive quarter of double-digit growth). IQOS SoM is up by +3.1pp to 30.6% in Q4 2024. Overall HnB category above 50% of total nicotine offtake share in 10 major cities and 5 prefectures in Dec 2024
– Europe: IQOS SoM by +0.9pp to 10.6% in Q4 2024. Adj. IMS up by +9.4% in FY24 with an acceleration to ~11% in H2 2024 and to ~10% in Q4 2024. Strong double-digit growth in many markets, including Spain, Bulgaria, Romania, Greece, and Germany. IQOS offtake share above 40% in Budapest, 30% in Rome, 15% in Belgrade and approaching to 10% in London, Vienna and Madrid
– Strong IQOS growth in key cities across the globe, including Riyadh, Kuala Lumpur, Jakarta, and Mexico City.
E-vapor: VEEV is now a top-3 pod (closed system) brand in 13 European markets (holding the #1 position in 5 markets, including Italy, Romania, Czechia, Slovakia and Finland). FY24 shipment of 1.7 billion units (2.7x FY23 volume).
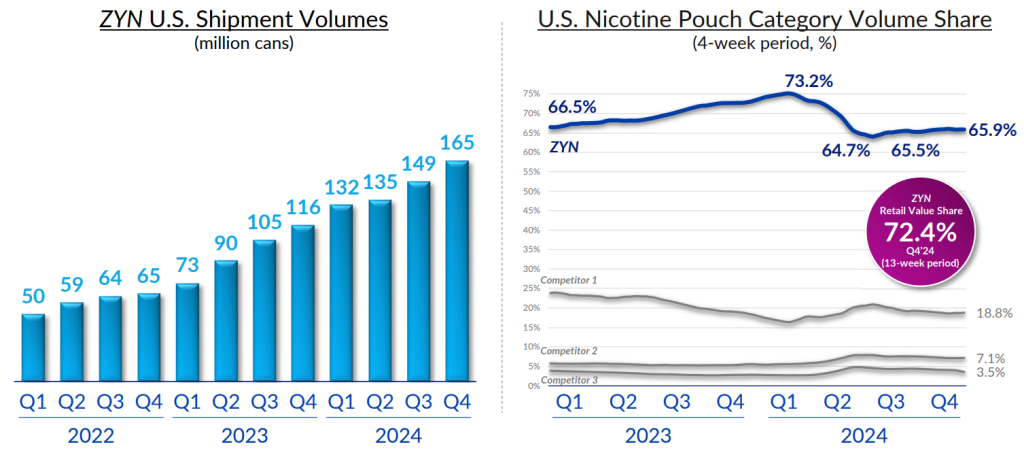
Oral Nicotine: FY24 shipment volume up +28% in cans (+25% in pouches). Q4 shipment volume up by +25% in cans (+22% in pouches), fueled by ZYN growth in the USA.165 million cans of ZYN shipped in Q4 2024, representing growth of +42%. Nicotine pouch volume more than doubled outside the USA, with notable contributions from Pakistan, South Africa, the UK and Mexico. PMI’s nicotine pouches s are now available in 37 markets, including recent launches in Italy, Romania and Thailand.
Combustibles: FY24 revenue up +4.0% (+5.9% on an organic basis), predominantly driven by strong pricing. Q4 revenue up +6.0% (+6.2% on an organic basis), driven by high single-digit pricing and growing industry volumes in markets where smoke-free products are not allowed (e.g. Turkey, India, Brazil and Vietnam). Market share gains by Marlboro and global brands portfolio.
Other Highlights
– IQOS ‘Be The First’ campaign continues in Austin, USA
– Canadian Settlement: PMI’s Canadian affiliate, Rothmans, Benson & Hedges (RBH) filed an objection to approval of the proposed settlement plan. If the Court approves the plan as proposed and it is subsequently implemented, RBH is likely to remain deconsolidated in PMI financial statements under U.S. GAAP – even if the payment of certain dividends from RBH to PMI is possible in the future depending on the final settlement plan. Moreover, PMI concluded that the estimated fair value of its investment in RBH was lower than its carrying value and recorded a non-cash impairment charge of $2.3 billion in 2024, with an adverse impact on reported Q4 2024 EPS of $1.49.
– Following the sale of Vectura, remaining units of Vectura Fertin Pharma will be reported under the Europe region as of Q1 2025
FY25 Guidance
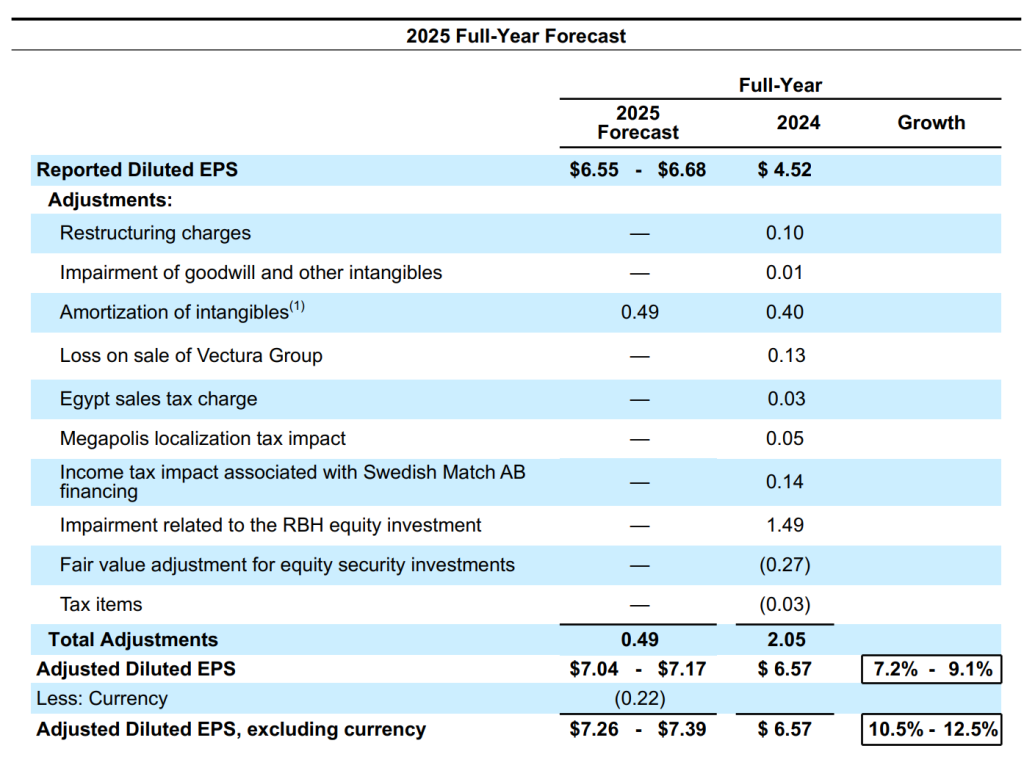
– Reported diluted EPS: in a range of $6.55 to $6.68, at prevailing FX, vs. $4.52 in 2024
– Adj. diluted EPS: in a range of $7.04 to $7.17, representing an increase of 7.2% to 9.1% vs. $6.57 in 2024 ($0.49 adjustment in 2025)
– Adj. diluted EPS, ex-FX: in a range of $7.26 to $7.39, representing an increase of 10.5% to 12.5% vs. $6.57 in 2024 ($0.22 adverse FX in 2025)
FY25 Assumptions
– International industry volume, ex-China & US: down ~1% (cigarettes & HnB combined)
– PMI volume: up +2%, driven by smoke-free products volume growth of 12%-14%
– Adj. HnB IMS volume: up +10%-12% (similar level to 2024; with HnB shipment growth rate broadly in line)
– U.S. nicotine pouch shipment volume: 780 to 820 million cans, representing a growth of 34%-41%
– Organic net revenue: up +6% to +8%
– Organic operating income: up +10.5% to +12.5%
– Amortization of acquired intangibles: $0.49 per share (IQOS take-back from Altria)
– Effective tax rate: ~22.5% to 23.5%
– Operating cash flow: ~ US$11 billion at prevailing FX with CAPEX of ~US$1.5 billion (including further investments in ZYN capacity in the U.S.)
– Net debt to adj. EBITDA ratio: further improvement towards the target ratio of around 2x by the end of 2026 (no share repurchases in 2025)
– Q1 2025 Adj. diluted EPS: $1.58 to $1.63 (including 4 cents adverse FX)
Summary
PMI’s financial delivery remained very strong in Q4 2024 and throughout FY24. Overall, net revenue growth of +9.8% on an organic basis in FY24 revalidates PMI’s industry-leading operational performance: organic volume growth (up +2.9% in FY24) coupled with strong pricing and favorable product mix (i.e. transition to smoke-free products with higher net unit revenue), partially held back by the geographical mix (i.e. cigarette volume weight shifting to emerging markets) and unfavorable FX (i.e. US$ strength against €, JPY and emerging market currencies).
References:

