


Bottom-line results & Volume progression1
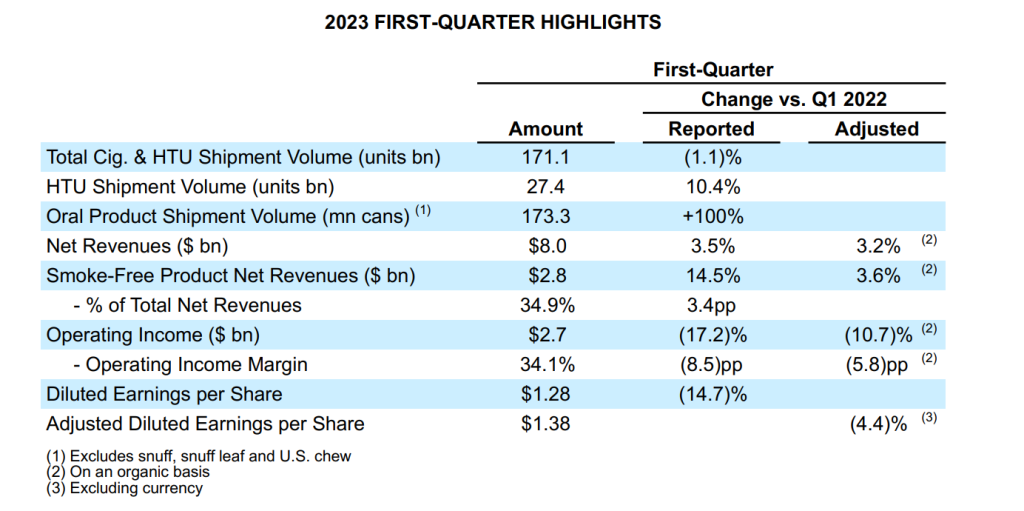
Revenue: up +3.2% to $8.02Bn in Q1 2023 (expected $8.11Bn)
Adjusted diluted EPS: down -4.4% to $1.38 in Q1 2023 (expected $1.34)
Total volume: down -1.1% to 171.1Bn units in Q1 2023 (HnB volume: +10.4% to 27.4Bn; +16% adj.)
Smoke-free revenue: $2.8Bn => 34.9% of total revenue (2025 target: 50%)
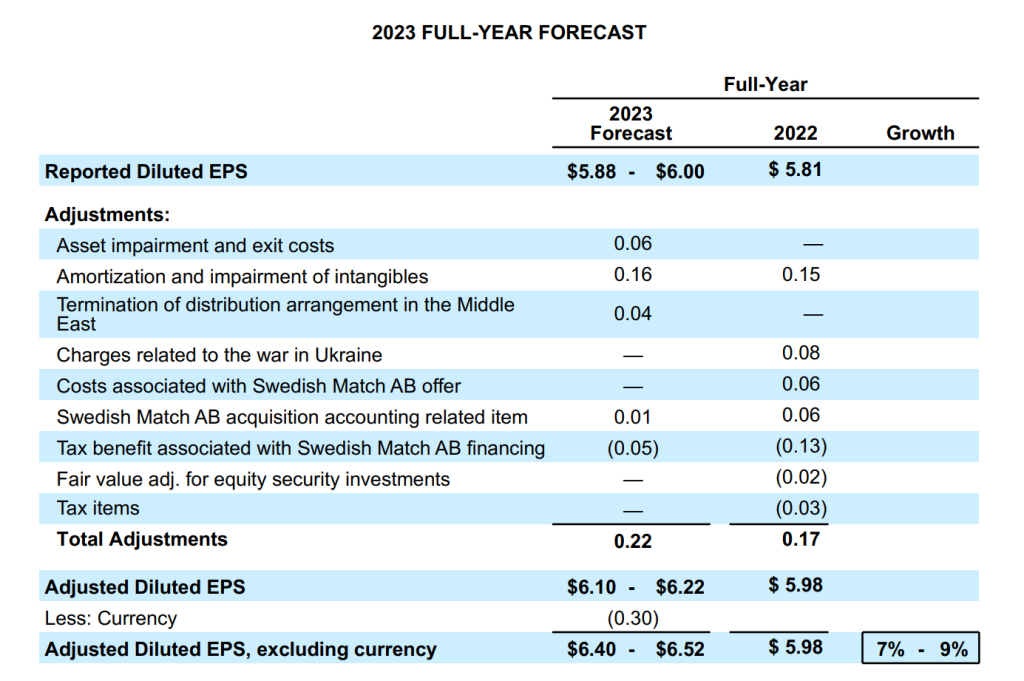
FY23 Guidance: Re-affirms net revenue growth of 7-8.5% and adj. EPS growth of 7-9%
Key highlights
– ZYN shipment in the US: 73.2 Mn cans (+46.7% reported; well over 30% adj.)
– Total oral tobacco volume: 173.3Mn cans (nicotine pouches: 81.3Mn cans; 47% of the total)
– Initiated a project to fully outsource the e-vapor manufacturing. Adjusting the VEEV e-vapor portfolio/approach with intention to commercialize VEEV in select markets (emphasis on profitability)
– Wellness & Healthcare: $86Mn net revenue and $24Mn adj. operating loss (reflecting R&D investments)
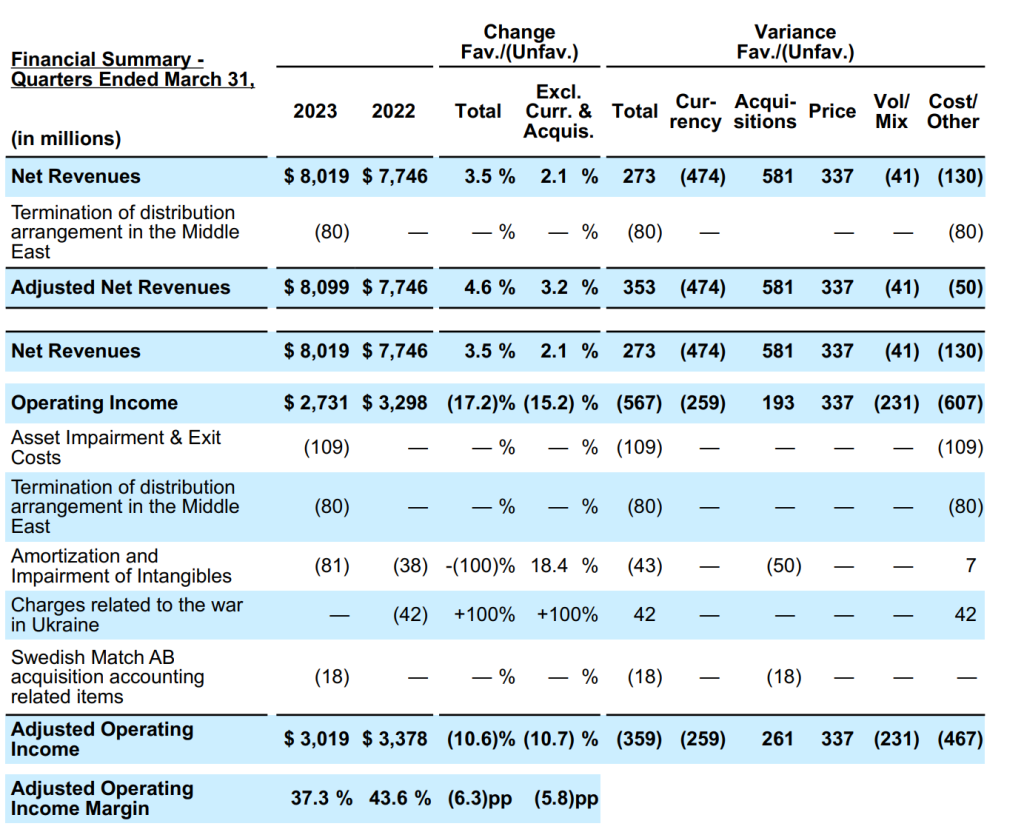
Operating Income: margin pressures
Adj. operating income margin down 5.8% points (on organic basis) due to:
– inflationary cost pressures (notably related to input costs and energy prices)
– transitory supply chain costs impact associated with the ILUMA roll-out
– general inflationary pressures on operating costs
– phasing of certain investments and other costs
Re-iterates that top/bottom-line delivery will improve throughout the year

FY23 Guidance
FY23 Revenue growth: +7%-8.5% (organic)
FY23 Adj. EPS (ex-FX) growth: a projected increase of 7%-9% to to $6.40-$6.52 v.s adj. diluted EPS of $5.98 in 2022
FY23 Adj. EPS: $0.15 lower than before (adverse currency impact now seen as $0.30 due to the weakness of Yen, Ruble and the Egyptian pound)
Q2 2023 Revenue: high single-digit (vs. +3.2% in Q1)
Q2 2023 EPS: $1.42-$1.47, including an unfavorable FX impact of $0.13/share
Total PMI volume: flat to +1%, despite 1-2% industry volume decline (ex-China&US)
HnB volume: 125-130Bn (acceleration in growth vs. 2022); Q2 HnB volume: 30-32Bn
Cigarette volume: a decline of 2.5% to 3.5%
Adj. operating margin: 0.5%-1.5% decline
Wellness & Healthcare revenues of $300Mn with an operating loss of $150Mn
Incremental net interest costs: $200Mn (vs. 2022), reflecting higher borrowing costs on refinanced debt
Operating cash flow: $10-11 Bn (no share repurchases due to the Swedish Match acquisition)
Our takeaway
Top-class management, execution & results vis-a-vis the industry peers. 5.8% points decline in the adj. operating margin decline is a bit of a shocker, but not unexpected. Moreover, PMI re-iterates that top/bottom-line delivery will improve throughout the year. Most importantly, two crown jewels of PMI, IQOS & Zyn, continue to demonstrate a stellar performance.
PMI shares rallied ~13% from the March low leading up to the Q1 2023 release. A short-term pullback won’t be unexpected (- on the basis of operating margin pressures). Nevertheless, we continue to like PM which is on the way to a new all-time high (ATH). The timing of the new ATH could coincide with the IQOS launch in the US. Meanwhile, any major pullback is a buying opportunity for the LT investors.
References:

