


Reynolds Reinvented: 150 Years of Tobacco, Transformation, and Corporate Reinvention
R.J. Reynolds Tobacco Company’s story is at once quintessentially American and quietly emblematic of the broader transitions in twentieth- and twenty-first-century commerce: a small, family-founded manufacturing operation that grew into a national icon and then navigated the social, regulatory, and market upheavals that have reshaped an entire industry. Founded in 1875 in the railroad town of Winston (now Winston-Salem), North Carolina, Richard Joshua Reynolds began by making chewing tobacco in a modest building known to locals as the “Little Red Factory.” That modest start – 150,000 pounds of chewing tobacco produced in the first year – would, over the next century and a half, evolve into a business that defined cigarette marketing, created household brands, survived moral and legal firestorms, and repeatedly reinvented its corporate form to preserve value for shareholders and adapt to changing consumer preferences.

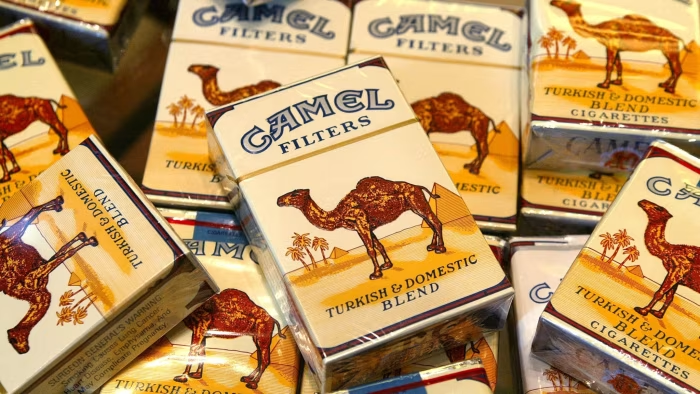
From a manufacturing standpoint, the scale and speed of Reynolds’s early growth were instructive about the company’s core capabilities: industrial organization, logistics, and above all marketing. By the early 1900s, Reynolds had consolidated many regional competitors in Winston-Salem and was producing chewing and smoking tobaccos at volumes that positioned the company for national expansion. The most consequential strategic move came in 1913 when RJ Reynolds introduced the Camel cigarette, an innovation in product design and mass marketing. Camel combined a unique blend – Turkish and domestic tobaccos – and pioneered a campaign that created national anticipation and consumer demand. Advertising stunts and national campaigns delivered rapid adoption: by the early 1920s Camel had become one of the most widely sold cigarettes in the United States. Camel signaled not only a product success but a new playbook for consumer packaged goods in nicotine: build a recognizable brand, invest heavily in above-the-line marketing, and scale manufacturing to meet national demand.
For decades, Reynolds’s strength was its portfolio of brands and its capacity to adapt those brands to shifting tastes and distribution systems. Over the twentieth century the company added and nurtured a set of products – Camel, Prince Albert (pipe tobacco), and later cigarette brands such as Winston, Salem, as well as other names – that collectively gave it the flexibility to compete in different segments and price points. Operational expansion accompanied brand development: the company built large, modern manufacturing facilities and centralized administrative campuses that anchored Winston-Salem’s economic geography. Those investments underpinned Reynolds’s market power and made it a capital-intensive, asset-heavy firm whose fortunes intertwined with labor markets, real estate, and civic institutions in its home region.
The second half of the twentieth century, however, presented existential threats that required Reynolds to shift from a simple focus on production and marketing to a more sophisticated mix of legal, regulatory, and corporate responses. Public health research, beginning in the 1950s and hardening into the 1960s and 1970s, systematically linked cigarette smoking to elevated health risks. That evidence, and the social and political responses it triggered, transformed the marketplace: advertising faced new constraints, product placement in public spaces constricted, and litigation exposing tobacco companies to large liabilities became a perennial strategic issue. Reynolds, like its competitors, invested heavily in regulatory affairs and public relations, while continuing to defend and extract value from its core cigarette franchise. The firm’s response was not merely defensive; in product and portfolio terms, it used brand segmentation, price ladders, and innovation in product formats to defend share. Over time, the rising legal and social costs of cigarettes also incentivized strategic diversification – both within nicotine and into adjacent packaged-goods assets.
That broader diversification is visible in one of the most consequential corporate transformations in Reynolds’ history: the merger with Nabisco to create RJR Nabisco in 1985, followed by the headline-grabbing leveraged buyout in the late 1980s. The 1985 combination of a tobacco powerhouse and a packaged-foods icon was, on its face, a classic conglomerate move aimed at smoothing earnings volatility, creating scale in distribution and procurement, and providing corporate finance flexibility. What followed tested the limits of corporate governance and revealed the extremes of 1980s dealmaking. In 1988 a protracted bidding contest culminated in a massive leveraged buyout – orchestrated by financial firms – that remains one of the emblematic financial events of that decade. The drama surrounding the takeover, captured by journalists and financial historians, showed how a company with deep operational roots could become the object of aggressive financial engineering, and how managerial incentives and market structures can interact to produce outsized transactions. The LBO and its aftermath reshaped ownership, governance, and the allocation of the company’s assets, with implications for employees, local communities, and the broader market for corporate control.

Reynolds’s post-LBO decades were defined by two parallel threads: first, the need to manage legacy liabilities and regulatory exposure, and second, the imperative to adapt the product portfolio to a market where combustible cigarettes were increasingly stigmatized and regulated. The 1990s and the 2000s were years in which the industry consolidated, litigated, and experimented. In 1999, amid litigation concerns and shifting corporate structures, the tobacco business was separated from much of the food and snack operations and re-emerged under different corporate umbrellas. The space of ownership and brand stewardship became complex, as companies bought and sold brands, spun off divisions, and responded to shareholder and legal pressures. For Reynolds and its successors, the logic was clear: protect core cash flows while crafting governance structures that limited exposure to the most damaging liabilities associated with the tobacco business, and seek new growth avenues in alternate nicotine products.
But the most consequential pivot in the twenty-first century has been strategic rather than purely financial: the company’s deliberate movement away from relying solely on combustible cigarettes toward a portfolio that includes smoke-free nicotine alternatives – vaping devices, heated tobacco products, and smokeless nicotine pouches. This reorientation reflects multiple forces converging at once. Consumers, especially younger cohorts, have reduced their cigarette consumption and shown strong interest in perceived lower-risk nicotine delivery systems. Regulators have tightened restrictions on advertising and flavoring. Investors and large multinational tobacco owners have signaled that long-term growth will be found in lower-risk alternatives because of both regulatory and demand trends. Reynolds, ultimately part of the bigger Reynolds American family and (since 2017) a U.S. subsidiary of British American Tobacco (BAT), has repositioned investment, M&A, and R&D priorities to capture that migration.
This repositioning has a technological and marketing dimension. Today, the company places emphasis on product formats that deliver nicotine without combustion: pouches with calibrated nicotine release, battery-powered inhalation devices, and heat-not-burn platforms that heat tobacco to release nicotine without open flame. Each format brings its own regulatory pathway, scientific questions, and marketing challenges. From a business perspective, these products often command higher margins at scale and offer a pathway to reduce the structural decline in combustible cigarette volume. Yet the transition is neither simple nor assured. Regulators in different markets treat these products differently; public health communities scrutinize claims of reduced harm; and consumers’ acceptance varies by region and cohort. For Reynolds, success demands aligning scientific evidence, regulatory approvals, and consumer trust while leveraging distribution and brand strength.
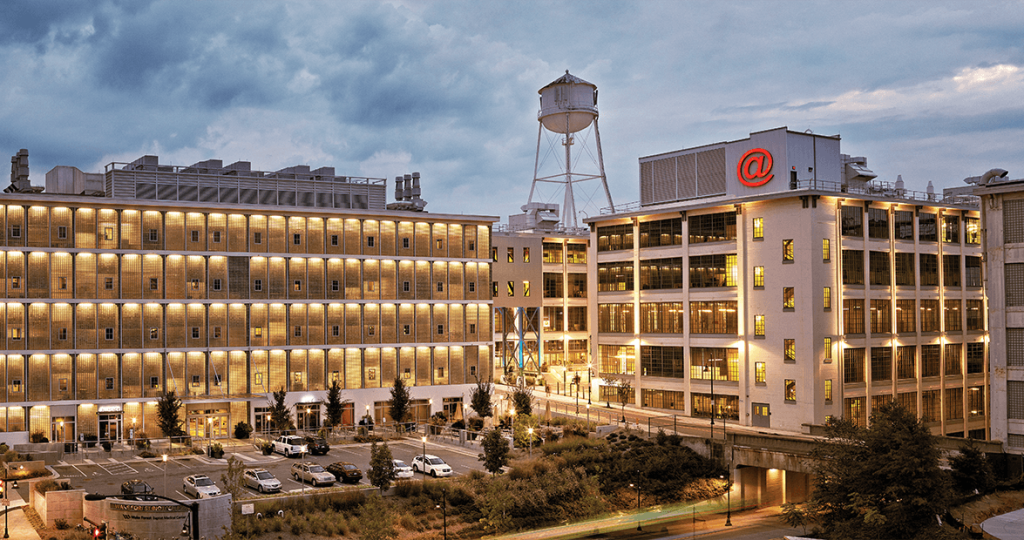
Beyond product strategy, Reynolds’ history illustrates how major corporations manage legacy civic relationships as their businesses transform. For a century R.J. Reynolds was not simply an employer but a civic institution in Winston-Salem: its factories shaped the urban landscape, its philanthropy touched cultural and educational institutions, and its real estate and employment patterns were central to regional economic identity. As manufacturing footprint consolidated and regulatory headwinds mounted, the company’s civic role evolved into a different kind of presence – one that supports redevelopment, historic preservation, and corporate philanthropy while navigating the reputational consequences of being a tobacco company in an era of growing public health concern. The donation and repurposing of physical assets, such as the 220-acre Whitaker Park complex, illustrate how industrial legacies can be retooled for contemporary urban economies even as the underlying product remains controversial.
Financially, Reynolds’s resilience has depended on the quality of its brands and the robustness of its operational model. Cigarettes remain an extraordinarily cash-generative product for the industry: per-unit margins are high, distribution networks are deep, and price increases often pass through to consumers. The company’s challenge has been to convert that cash flow into investments that will sustain revenue longer term as cigarette volumes trend down. The mergers, spin-offs, and ownership changes of the 1980s and 1990s can be seen through this lens: corporate finance moves intended to preserve shareholder value in a shifting market. The acquisition by BAT in 2017, which placed Reynolds American within a global tobacco conglomerate, underscores the industry’s contemporary logic: global scale, cross-market product platforms, and centralized R&D offer the most plausible route to monetize smoke-free product portfolios at scale.
There are organizational lessons in Reynolds’s arc that transcend the tobacco sector. First, powerful brands and deep customer relationships buy time – time to pivot, to litigate, and to invest in new capabilities. Reynolds used those advantages to underwrite costly legal defenses, to sustain R&D in product alternatives, and to invest in marketing experiments. Second, organizations built around a single product or technology must design deliberate strategies for portfolio renewal; Reynolds’s shift to smoke-free alternatives shows how incumbents can leverage distribution and brand to introduce different product architectures. Third, corporate governance matters: the dramatic events of the 1980s, including the RJR Nabisco LBO, remind managers and investors that incentives, transparency, and the structure of deals can have enduring consequences for employees, communities, and long-term competitiveness.
As Reynolds celebrates its sesquicentennial, the company’s future is best read as a question about how successfully it can execute a multi-dimensional transformation: from a legacy tobacco manufacturer to a diversified nicotine company that can sustain revenues in an environment of declining cigarette prevalence. Success will depend on three interconnected capabilities. First, scientific and product credibility: Reynolds must support robust evidence around reduced harm where claims are made and navigate the complex scientific dialogue on nicotine delivery and public health. Second, regulatory navigation: the company must secure approvals, shape policy debates, and conform to heterogeneous regulatory regimes across jurisdictions. Third, consumer migration: the firm must persuade millions of adult smokers that alternative products meet their needs while avoiding youth uptake and reputational damage. Achieving all three is a high bar, but it is the logical path for preserving the economic value accumulated over 150 years.

The Reynolds story also poses broader questions for investors, regulators, and public health stakeholders. For investors, the transition presents a classic risk-reward calculus: to what extent do alternative nicotine products offset secular declines in cigarette volumes, and what multiple should the market assign to a tobacco company with credible smoke-free options? For regulators, the central problem is designing rules that protect public health – limiting youth initiation and reducing population harm – without closing off potentially reduced-risk alternatives to adult smokers. For public health advocates, Reynolds’s pivot is both a caution and an opportunity; if alternatives genuinely reduce harm for individuals who would otherwise smoke, they could have positive effects at scale, but those gains depend entirely on disciplined marketing, tight controls on youth appeal, and robust independent evaluation. These competing priorities make Reynolds a bellwether: how a major incumbent navigates them will influence industry norms and regulatory frameworks for years to come.
Looking back over 150 years, it is tempting to reduce Reynolds’s history to a few headlines – the founding in 1875, the breakout success of Camel in 1913, the RJR Nabisco era and the leveraged buyout, and the contemporary pivot to smoke-free nicotine products. Those moments matter because they reveal the company’s capacity to invent, to scale, to adapt corporate structures, and to confront external pressures. But the more revealing throughline is the firm’s repeated ability to reorganize its economic engine: industrializing production in the late nineteenth century, creating nationally resonant brands in the early twentieth, restructuring corporate ownership in the late twentieth, and now retooling product architecture in the early twenty-first. In each epoch the company has relied on a combination of marketing insight, operational competence, and strategic financial maneuvers. The form and morality of the product have changed in public esteem, but the underlying business problem – how to create and sustain value amid shifting consumer preferences and regulatory constraints – has stayed the same.

If history is a guide, Reynolds’s next chapters will be written not only in Winston-Salem boardrooms but in laboratories, regulatory agencies, and the marketplaces of reduced-risk products. The company has the brand equity and distribution muscle to remain a major industry actor; the question is whether it can translate those advantages into durable leadership in a nicotine ecosystem that prizes science, regulatory clearance, and public trust. For students of corporate strategy, Reynolds provides a compact case study in long-run adaptation: how a firm with a singular product heritage can repeatedly reinvent itself without shedding the economic core that has built its wealth. Whether that process will satisfy public health goals or merely prolong the commercial life of nicotine as a mass commodity is a political and ethical question as much as it is a business one. What is clear is that Reynolds’s 150-year narrative – rooted in a little red factory on Depot Street — remains a live experiment in corporate reinvention, and one whose outcomes will matter to investors, regulators, and communities for years to come.

