


Top-line & Bottom-line results1
Adjusted: at constant currencies
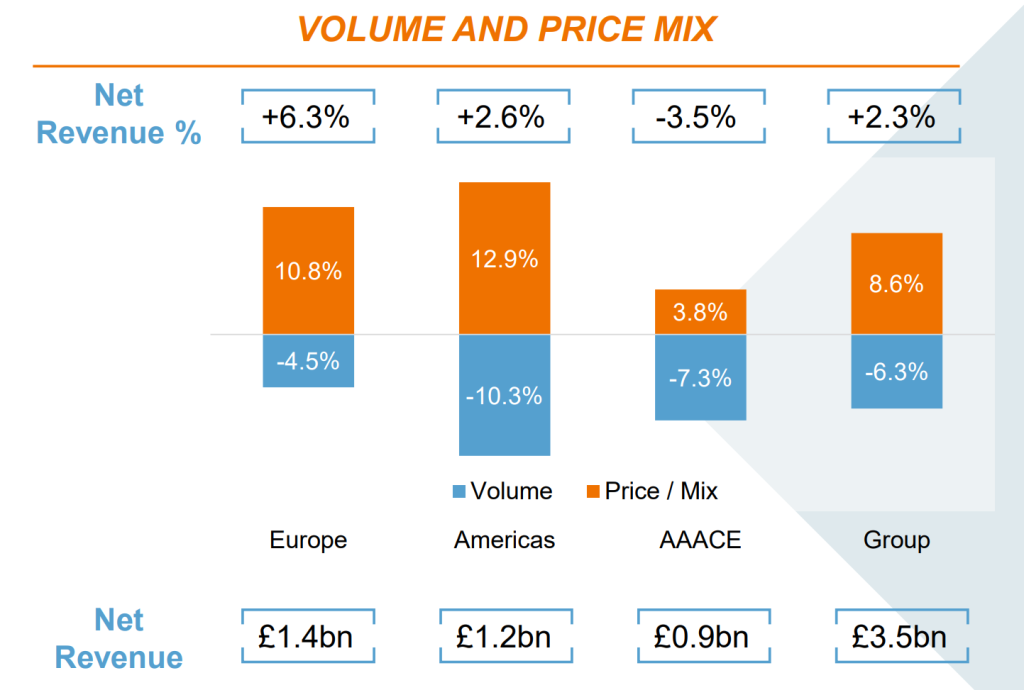
– Volume: -6.3% (to 89.9Bn sticks), reflecting the wider industry decline in the markets where Imperial Brands is present (“established footprint”)
– Strong tobacco pricing (+8.6%) more than offsetting volume declines
– Revenue: +2.8% (NGP revenue: +16.8%, driven by scale-up in launch markets and product innovation) => the strongest organic growth in more than ten years
– Operating Profit: +2.8%
– EPS: +7.7% (operating profit growth and reduced share count, more than offsetting higher finance costs and a higher tax rate)
– Interim Dividend: +4.0% to 44.0p
– On track to meet FY24 guidance

Highlights – Traditional Products:
– Aggregate SoM in five priority markets maintained (through continued investment in brand equity and sales force initiatives) despite strong pricing
– SoM gains in USA (+5 bps), Spain (+50 bps) and Australia (+10 bps) offset declines in Germany (-25 bps) and UK (-40 bps)
– Encouraging improvement in German SoM trend -25 bps vs HY23 and FY23 -80 bps
– (Combustible) Industry volume decline in top-5 markets: Australia: -25.3%, UK: -15.2%, US (cigars): -9%; US (cigarettes): -8.7%, Spain: -2.0%, Germany: -1.4%
Highlights – NGPs:
– NGP net revenue weight: 7% in Europe (3.9% overall)
– Europe net revenue growth +24% (vs. +16.8% overall)
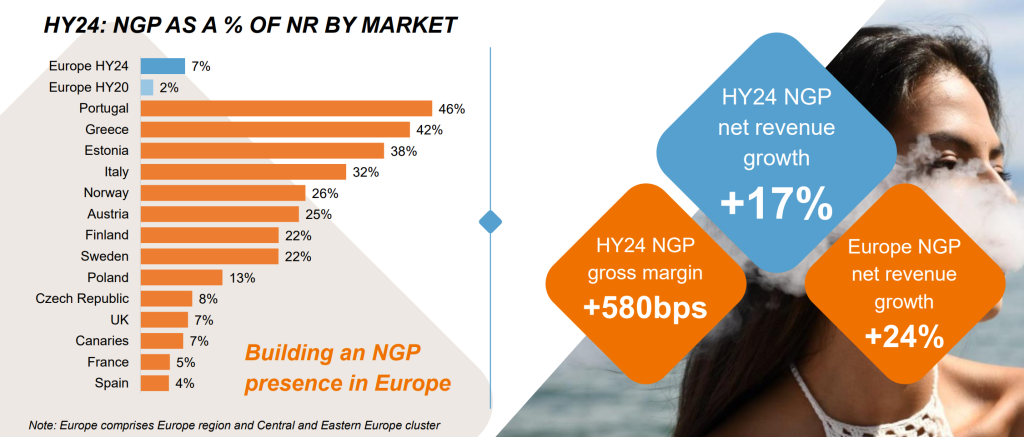
– NGP losses: reduced by +8.9% to £50Mn => improved gross margin (+580pp) and volume growth supporting continued investment in new product launches
– Launched new products in all categories over the past 6 months, including entry into the US oral nicotine market (12 cities) with the new ‘Zone’ brand in Feb 2024 (present in 12.8k stores) and the new blu bar vape launch (with 1,000 puff capacity, removable battery and reduced plastic content)
– Expanded heated product offering for Pulze 2.0 with iSenzia flavored herbal sticks in Europe
– Improved innovation capabilities now include three ‘Sense Hubs’ in Liverpool, Hamburg and Shenzhen (set to adapt to changing consumer preferences and regulatory requirements)
Regional Results:
– AAACE (ex-Americas & Europe) performance impacted by Middle East disruption, Australia market size and a strong basis of comparison (H1 2023)
Finanical Highlights:
– Adj. operating cash conversion of 97% on a 12-month basis (working capital improvements)
– Adj. net debt: £10.1Bn => Adj. net debt to EBITDA broadly flat at 2.5x on a 12-month basis (on track to deliver adjusted net debt to EBITDA of ~2.0x at the year end)
– £604Mn of the FY24 share buyback program (£1.1Bn in total) completed => since starting the buyback in October 2022, 9% of share capital repurchased
– On track to return (at least) £2.4Bn in FY24 and £6Bn on a three-year cumulative basis to shareholders (including buybacks and dividend)
FY24 Guidance: Re-iterated
– Final 2 years of the 5-year strategic plan: mid single-digit operating profit over the FY23-FY25 period
– Low single-digit (1%-3%) tobacco & NGP net revenue growth and close to the middle of the mid-single digit (5%) operating profit growth in FY24
– Strong tobacco pricing and lower NGP losses to support a stronger H2 delivery
– Translation FX headwind of ~2% on FY24 tobacco & NGP net revenue and ~3.0-3.5% on FY24 operating profit and EPS
Our takeaway:
Nothing much to cheer about. Although Imperial confirmed the FY24 revenue and operating profit guidance, volume decline (-6.3%) in combustible tobacco is steeper and NGP revenue growth (+16.8% from a very small base) is slower than expected. Imperial is still employing an outdated modus operandi: price a dying product (combustible tobacco) to extinction. Moreover, we recognize an increasing amount of reference to “established footprint” in Imperial’s communications – which translates as “this is what we have to live with (our destiny)”.
Even if Imperial’s results are not “cheerful”, downside trends & risks are already reflected in the valuation: IMB.L is trading at an undemanding 6.3x P/E multiple (based on the FY24 EPS consensus of £3) with a comfortable debt level (~2x net debt / EBITDA targeted at year-end). Moreover, a large share buyback program (~8% of share capital at the time of the announcement) is in place.
We continue to expect Imperial to range trade around the current levels (£20+/-£2) and at historical lows (in terms of valuation multiples: 6-7.3x EPS). Moreover, periods of upside volatility are also likely; thereby, Imperial Brands is tradable (i.e. short-term stock ownership: 3-6 months). However, until Imperial addresses the “transformational” concerns, “financial engineering” and/or “an investment case built on the strength of current (not future) cash generation” don’t render Imperial Brands investable (i.e. long-term stock ownership: 5-10 years).
References:

