


Guidance & Expectations
EPS (adjusted diluted): $1.42-$1.47, including an unfavorable FX impact of $0.13/share (revised as “towards the top-end” at the DB conference)
Heated Tobacco Volume: 30-32Bn units (revised as 31-32Bn units at the DB conference)
Operating Income Margin: significant sequential improvement, up to 100 bps vs. Q1 2023
Analyst Expectations: $8.7Bn Revenue & $1.48 EPS
What to watch out for? Operating Income Margin.
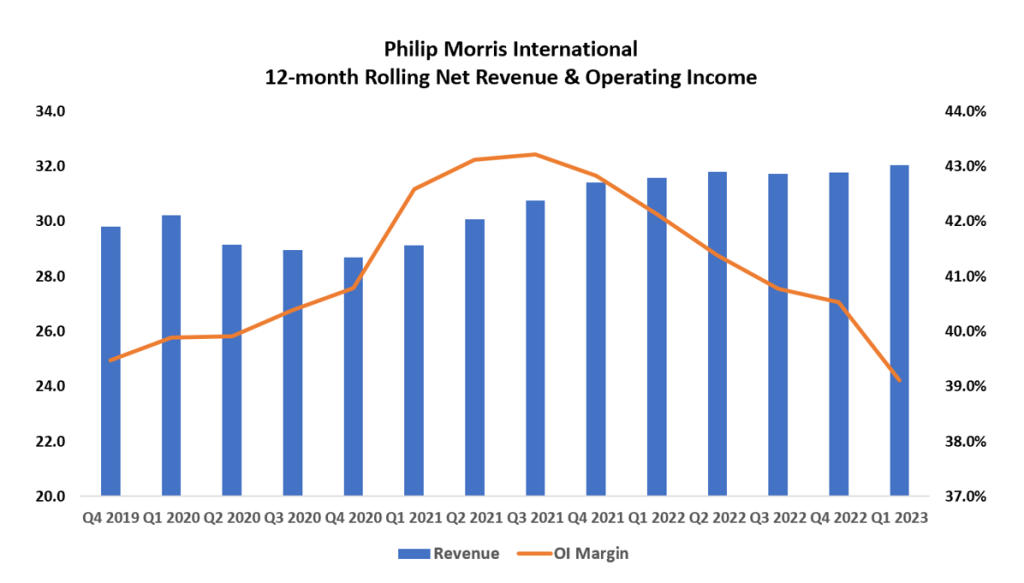
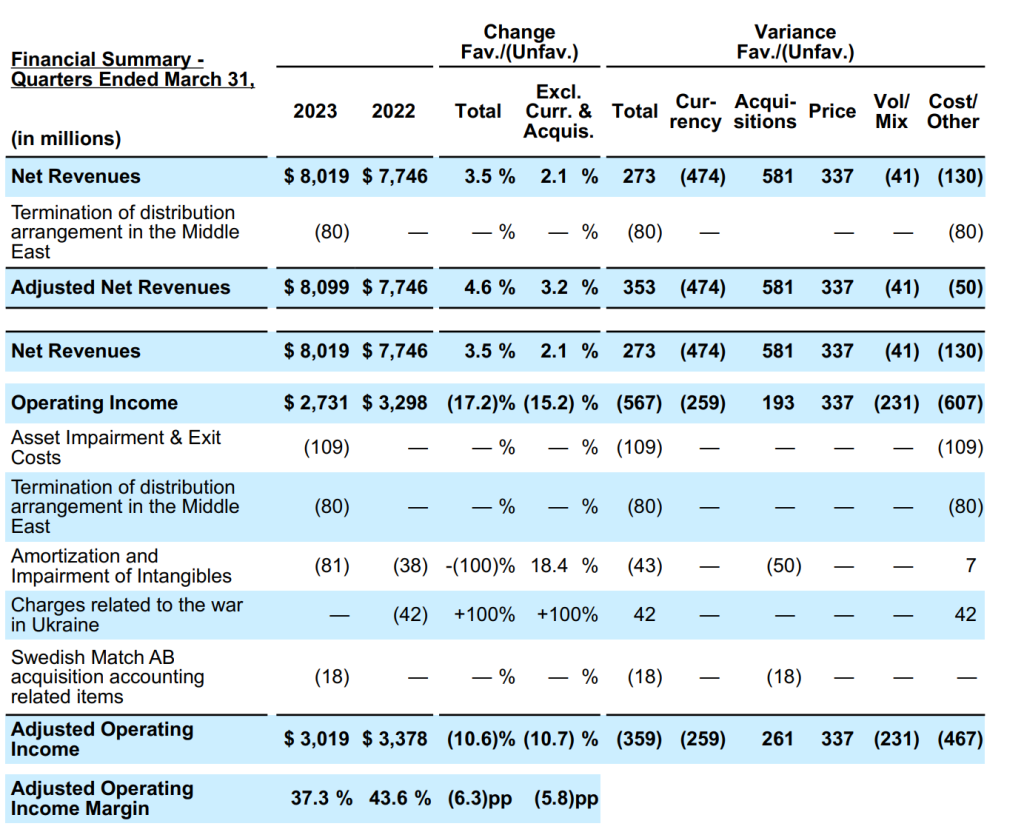
PMI’s operating income margin (12-month rolling) has been declining since Q3 2021. However, the decline reached a shocking level (probably, its apex) when PMI reported 5.8% points (on organic basis) operating income margin decline in Q1 2023 versus Q1 2022. PMI shares lost 4.7% on the day of Q1 2023 earnings release and suffered a 12% pullback (from $101.5 to $89) in the following 5 weeks.
PMI attributed the margin decline to
– inflationary cost pressures (notably related to input costs and energy prices)
– transitory supply chain costs impact associated with the ILUMA roll-out
– general inflationary pressures on operating costs
– phasing of certain investments and other costs
… and re-iterated that top- and bottom-line delivery will improve throughout the year.

Top-line delivery performance is unquestioned. Excluding the covid period, PMI’s 12-month net revenue has been improving sequentially (even before the Swedish Match acquisition) and topped $32Bn for the first-time in Q1 2023. With $8.7Bn net revenue in sight in Q2 2023, the 12-month total will add up to $32.9Bn.
In terms of operating income margin, 100 bps sequential improvement expectation is already built in. This corresponds to 38.3% OI margin in Q2 2023 – still 2.9% points below Q2 2022. Heading into the earnings release, PMI shares have already rallied more than 10% from the May 2023 low. We believe a OI margin beat and re-assurance on further improvement in the H2 2023 are critical for PMI to lock in the share price gains and stay above $100.
In addition, we will scrutinize the year-on-year IQOS (heated tobacco) and Zyn (modern oral) volume growth as well as the $0.30/share negative FX-impact expected on the FY23 EPS (i.e. whether the prevailing US$ weakness triggers a change in this adjustment line).

