


Key Business Metrics: Q1 20251
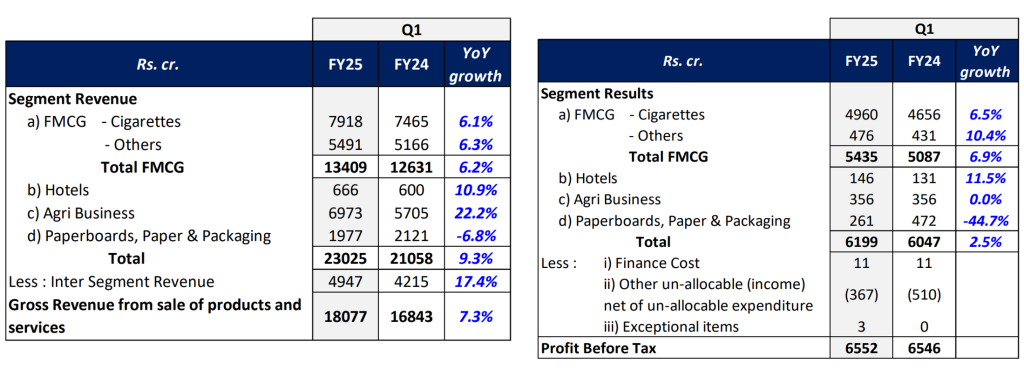
Gross Revenue is up +7.3%, driven mainly by Hotels, value-added agricultural products and leaf tobacco. FMCG segment, both Cigarettes (+6.1%) and Others (+6.3%), delivered resilient performance amid subdued demand conditions. Paper segment (-6.8%) is under pressure largely due to the cheap Chinese supplies in global markets and surge in domestic wood prices
Profit is up marginally: +0.1% before tax, +0.3% after tax
Q1 2025 EPS (diluted): ₹3.93 (flat)
12-month rolling EPS (diluted): ₹16.35 (trading at 30x trailing EPS based on the last closing price of ₹493.7)
FY24 Segment Highlights
Cigarette Segment: (34% weight in gross revenue, 80% weight in operating profit)
Relative stability in taxes and actions by enforcement agencies drive continued volume recovery from illicit trade:
– Gross segment revenue is up +6.1%. Net segment revenue and operating profit are up +7.0% and +6.5%, respectively
– Sequential slow down in growth amidst subdued demand conditions in the overall consumption space (cigarette volume growth estimated as +2.7%)
– Market position reinforced through focused product portfolio & commercial interventions (i.e. differentiated and premium offerings) and agile execution; sequential improvement in Value segment
– Sharp escalation in input costs (leaf & other input materials), largely mitigated through improved mix, strategic cost management and calibrated pricing
Other Segments:
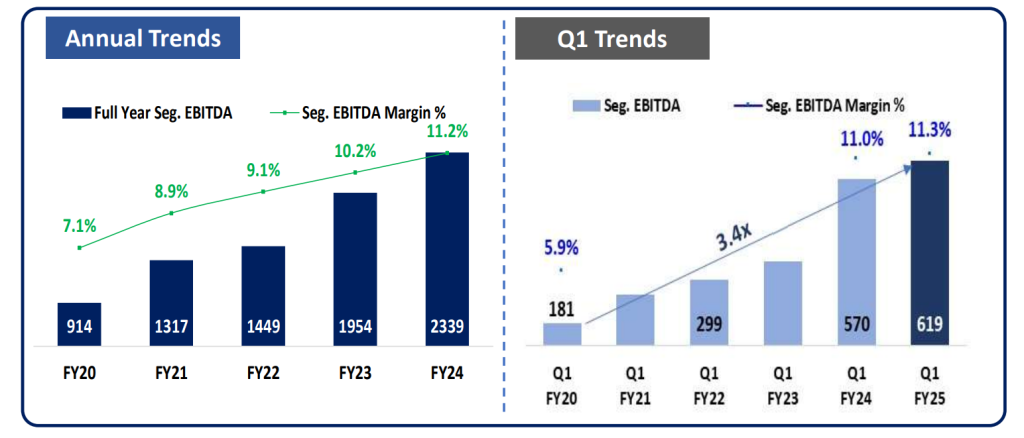
– FMCG (revenue is up +6.3%, operating profit is up +10.4%): margin expansion (+25bps to 11.3%) driven by premiumization, supply chain optimization, pricing actions, digital initiatives and strategic cost management. Extreme heatwave in parts of the country, high competitive intensity (local / regional players) and sequential uptick in prices of certain items adversely impacted the segment while robust growth achieved in Emerging Channels through channel-specific business plans, collaborations, format-based assortments and category-specific sell-out strategies
– Agri Business segment (revenue is up +22.2%, operating profit is flat): negatively impacted by trade restrictions imposed by the Government on agricultural commodities (e.g. stock limits on wheat) as the geopolitical tensions & climate emergencies raise concerns on food security. Strong customer relationships and agile execution in Leaf Tobacco & Value Added Agri products (mainly by Coffee & Spices) continue to drive growth in these categories. Steep increase in green leaf prices and other commodities exert pressure on margins.
– Mysuru factory (to manufacture and export of nicotine & nicotine derivative products conforming to US & EU pharma standards): EU REACH (regulation on “registration, evaluation, authorization and restriction of chemicals”) approvals received, customer trials underway
– Paperboard, Paper & Packaging (revenue is down -6.8%, operating profit is down -44.7%): negatively impacted by low-priced Chinese supplies in global markets and muted domestic demand. Surge in domestic wood prices and ocean freight weighed on margins. Segment performance includes the impact of shutdown / stabilization related costs pertaining to the capacity augmentation projects completed during the quarter.
Summary:
Despite delivering a top-line growth in line with the expectations, ITC misses the profit estimates. Subdued demand conditions in the overall consumption (FMCG) space, increasing input costs as well as the circumstantial challenges in non-FMCG segments adversely affect the bottom-line delivery.
Nevertheless, absence of a tax hike in the FY25 Union Budget is likely to fuel cigarette volume claw-back from illicit trade and could help ITC deliver 3%-4% cigarette volume growth in the upcoming quarters. An amelioration in cigarette performance (80% weight in operating profit in Q1 2025), coupled with strengthening rural consumption, is expected to drive sequential improvement in ITC’s bottom-line delivery in the rest of FY25.
References:

