


Q2 2024 Results1
Revenue: ₩1.42Tn (+6.6% year-on-year)
EBITDA: ₩383.1Bn (+25.4%); EBITDA Margin: 26.9% (+4.0pp)
Operating Profit: ₩321.5Bn (+30.6%)
Net Income: ₩318.0Bn (+57.5%); EPS: ₩2,754 (+59.5%)
Shareholder returns: Interim dividend of ₩1,200 will be paid in Aug 2024. Total FY24 dividend will be more than ₩5,200 (FY23 dividend). Total 5.3% of outstanding shares to be re-purchased & cancelled in 2024. New “Corporate Value-up Plan” will be published in H2 2024.
Results: Tobacco Division
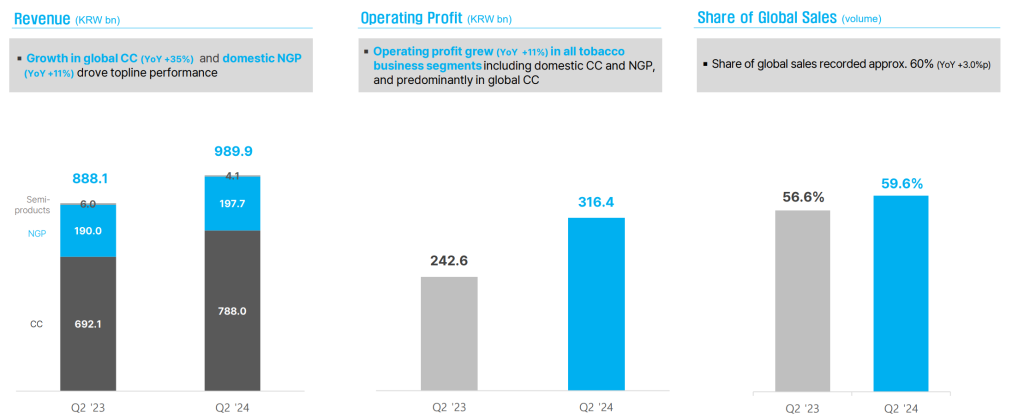
Key announcement highlights for Q2 2024 (tobacco business only):
– Revenue +11.5% to ₩989.9Bn; Operating Profit +30.4% to ₩316.4Bn => Margin up from 27.3% to 32%
– Cigarette volume up +8.9% to 25.64Bn sticks, driven by +16.2% growth in the international markets
– NGP revenue weight in total tobacco: down from 21.4% to 20%
– International (ex-Korea) revenue: 59.6% of the total (+3.0pp)
– Conventional – Korea: -0.4% volume decline to 10.33Bn sticks due to the market contraction and despite the SoM growth (up +1.7pp to 66.9%)
– Conventional – International: Growth Trifecta (volume – revenue – profit) and record-high quarterly revenue. +16.2% volume growth (to 15.31Bn sticks) coupled with +35.2% revenue growth and +139.1% operating profit growth. All key regions contributing to growth
Results: NGP Segment
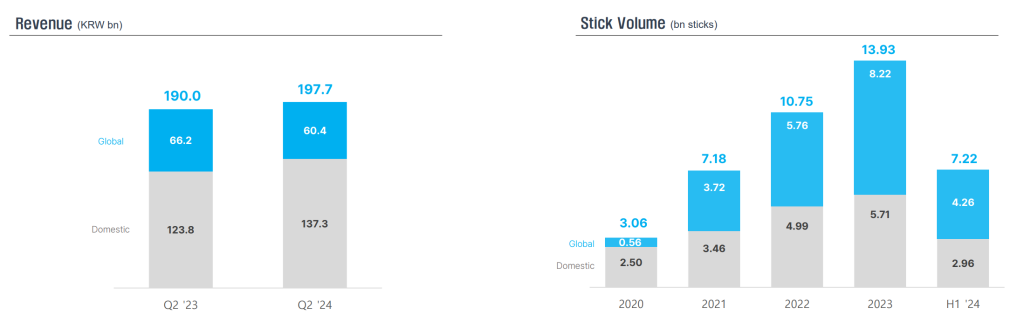
– Overall NGP volume: +1.9% to 3.68Bn sticks in Q2 2024 (vs. +9.9% in Q1 2024)
– Overall NGP revenue: +4.1% in Q2 2024 (Korea: +10.9%, international: -8.8%)
– NGP – Korea: Leadership is maintained with SoS is flattish around 45.8% (+0.1pp on sequential basis), supported by competitive advantage in devices and new consumable variant launches in a fiercely competitive environment (e.g. more aggressive promotions offered by PMI and BAT). Volume is up +7.7% (to 1.42Bn sticks), revenue is up +10.9%.
– NGP – International (Global Partnership with PMI): Volume is down -1.8%. Revenue is down -8.8% due to the device inventory adjustment “in preparation for new platform launch” and lower consumable volume. Operating profits expand as sales of NGP sticks, the main source of profit in the business, continues to grow => volume growth (+5.7% in H1 2024) is significantly below the target communicated during the extension of the global partnership agreement with PMI (i.e. “20% annual growth aimed in NGPs over the next 15 years”). Moreover, lower-than-expected international NGP volume growth resurfaces the concerns about “heated tobacco growth slowdown”.
Summary:
KT&G’s Q2 2024 results are in a complete contrast to the Q1 2024 results. International cigarettes, supported by the domestic NGP segment and Health-Functional Food segment in China, fueled KT&G to deliver +6.6% revenue growth (vs. -7.7% decline in Q1 2024). Likewise, operating profit swung from -25.2% decline to +30.6% growth on a sequential basis.
Following KT&G’s Q1 2024 earnings release, we noted that: “It seems like KT&G was vested more in the election of its new CEO – than properly managing its business – in Q1 2024. Results are weak for the key growth businesses (heated tobacco and international cigarettes) and catastrophic for the others. We believe the Market will offer minimal patience to the newly elected (highly contested) CEO; thereby, it is crucial for KT&G to deliver meaningful margin and operating profit improvement in the rest of FY24”. KT&G delivered a turnaround that is quicker and better than the wildest expectations.
There is only one sore spot in the results: NGP International. The Q2 2024 volume decline is hidden in the earnings release and weakness is solely attributed to the new platform launch preparation. In the upcoming coming quarters, we will continue to keep an eye on two points: (1) the financial return from the PMI partnership, (2) global heated tobacco slow-down.
KT&G has taken a strong step in Q2 2024 in proving that its can grow its volume and revenue base without sacrificing the profitability. The early success will also strengthen the market confidence in the new CEO. If KT&G continues to deliver in the rest of FY24, a valuation re-rating (“multiple expansion” for a proven growth business) could be in the cards – which would take KT&G to the same league as PMI and Japan Tobacco (P/E>15).
References:

