


Another dividend hike
Altria increased its quarterly Dividend by 4.3% to $0.98/share on August 24, 2023. The new annualized dividend rate is $3.92 per share, representing a yield of 9.1% based on the closing stock price of Aug 23 and making Altria the the top dividend paying tobacco company (- slightly ahead of BAT’s 9.0% yield). The complete list of dividend paying tobacco stocks with more than 5% annualized yield is available on our website.
A remarkable track record
Altria’s 4.3% dividend hike is the 58th increase in the past 54 years. Moreover, Altria now pays 18% more annual dividend than the peak payment made before Kraft and PMI spin-offs ($3.32 in 2006 or $3.44 annualized in 2007 before the Kraft spin-off). An Altria investor in 2006 would be receiving $11.2 dividend per share today assuming that he has held on to his shares throughout all the subsequent spin-offs and mergers: Altria dividend ($3.92/share) + PMI dividend ($5.08/share) + 89% of the Mondelez dividend ($1.51/share) + ~44% of the Kraft&Heinz dividend ($0.70/share). And this excludes the $16.5/share special cash dividend received by the Kraft shareholders in 2015 during the merger with Heinz.

Future?
Past performance is no guarantee of future results and there are a few things to pay attention in Altria’s future earnings & dividend progression:
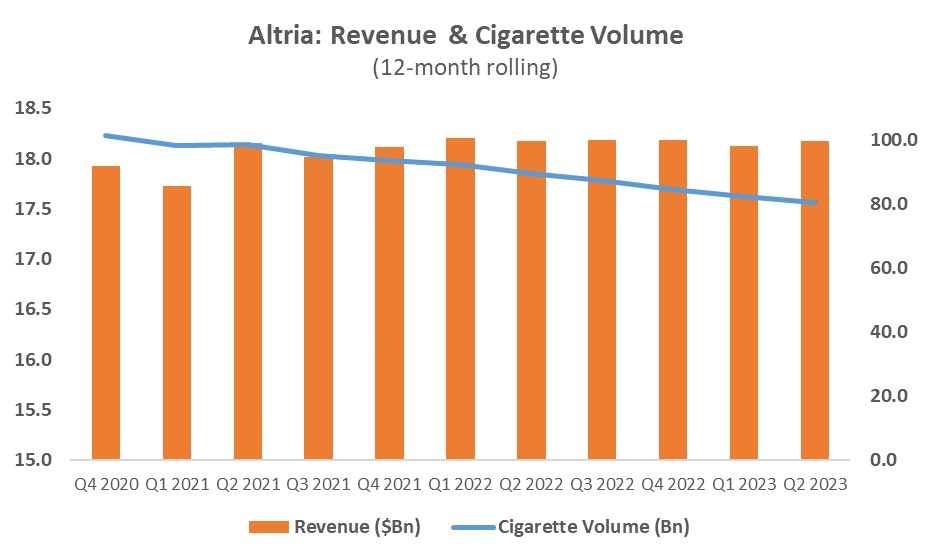
(1) Altria’s core business (US combustibles: 87.6% of its revenue and 86.3% of its adjusted operating profit in H1 2023) is facing a volume pressure unlike any other time before. Since Q2 2021 (in two years), Altria’s 12-month rolling cigarette volume is down almost 20Bn/-20%. Accordingly, Altria’s 12-months rolling combustible revenue is flat at $18.1Bn (+/-$0.1Bn) in this period. Altria will have to extract more profit from a stagnant revenue base – especially when it is also forced to do major NGP catch-up investment.
(2) Altria’s EPS growth declined from 10+% p.a. to mid-single digit (2019-22). Furthermore, Altria’s FY23 EPS guidance (i.e. 1% to 4% growth from $4.84 in FY22: midpoint 2.5%) is even below the mid-single digit norm (4%-6%), mainly due to the planned investments behind the commercialization of NJOY ACE. Fast decline in cigarette volumes coupled with NGP catch-up investment may cause Altria to deliver low-single digit (or even negative) EPS growth in 2024 and beyond.

(3) The annual dividend growth rate is already down from 9.5% (in the first 10 years after the spin-offs) to 4+% (in the last 5 years). Since 2010, Altria’s objective has been a dividend payout ratio target of ~80% of adjusted diluted EPS. However, considering the bleak EPS growth outlook, Altria was likely to deliver low-single digit (1%-3%) or even no dividend increase in 2024 and beyond – if they were to stick with the 80% anchor. The little slack they have in the payout ratio is almost used up with the 2023 hike (i.e. 4.3% dividend increase despite 2.5% EPS growth, moving up the ratio from 77.7% to 79%). Thereby, Altria Management was forced to decouple the earnings and dividend growth by abolishing the 80% anchor – before the market starts speculating on an eventual dividend cut.

Altria announced a new progressive dividend policy that avoids “potential earnings variability affecting the dividend payout” by targeting a mid-single digit dividend growth annually1. Obviously, the earnings variability, to which Altria refers, is to the downside. Otherwise, in 2018, when the EPS grew by 17.7%, Altria did not hesitate to raise its dividend by a record amount of 21.2%.
Abolishing the 80% anchor provides Altria with more flexibility in deciding on its dividend payout. However, a mid-single digit dividend growth target will cause the payout ratio to increase if Altria cannot grow its earnings at the same speed. Our expectation: Altria’s payout ratio will increase 2-3% p.a. in 2024 and beyond. If Altria reports negative adjusted EPS growth in 2025 and beyond (a plausible, but not base-case scenario), payout ratio may reach 100% in 2029.
Altria may have gained time to avoid a dividend cut by abolishing the 80% anchor. However, as long as Altria doesn’t has a proven/working strategy to break out of the ailing US cigarette business (i.e. transformation to RRP/NGPs and/or expansion to new categories/geographies), an eventual dividend cut seems unavoidable. On a positive note, Altria’s Management recognizes the challenges and their new-found RRP/NGP focus is undeniable. We like that Altria now goes above and beyond what is expected: testing a new RRP/NGP product online in Sweden (3D-challenge: new product, new geography, new channel). Is it too little too late? Time will tell.
References:

