


Background
Scandinavian Tobacco Group (STG) is the world’s 11th largest publicly traded tobacco company by revenue. STG became a pure-play cigar & pipe tobacco manufacturer, following the acquisition of its cigarette & snus business (“House of Prince”) by BAT in 2008. With operations mainly in Europe & the USA, STG owns well-known brands like Macanudo, La Gloria Cubana, Panter, Signature, La Paz, Café Crème, Cohiba, Partagas and Captain Black. Since 2022, STG is exploring opportunities to enter the Next Generations Products (NGP) category in order to complement its core cigar & pipe tobacco range (portfolio diversification) and to re-ignite revenue growth (“Growth Enablers”).
Q4 2023 & FY23 Results (March 5, 2024)1
“Growth comes at a cost”: Growth investments putting pressure on the margins, EPS and FCF (both FY23 Actuals and FY24 Guidance)
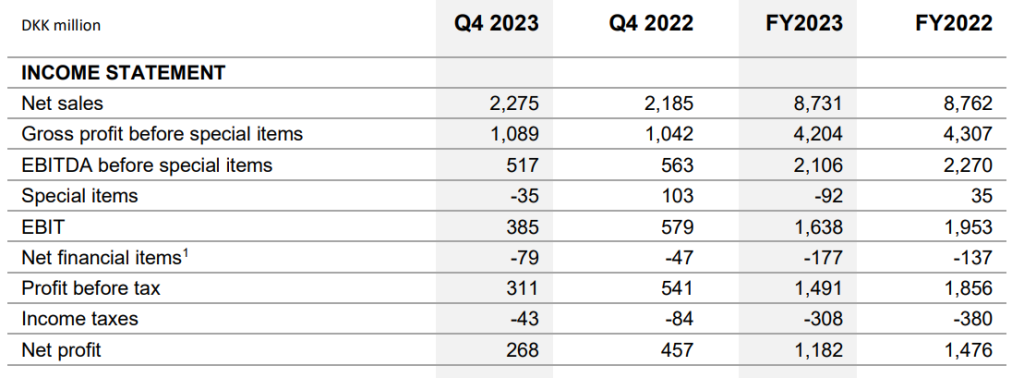
Q4 2023. Net sales: kr.2.3Bn (+5% on organic basis); EBITDA margin: 22.7% (-3.1pp vs. Q4 2022; impacted by increased investments and cost inflation); adj. EPS: kr.3.6 (vs. kr.4.4 in Q4 2022)
– Organic growth in net sales was driven by the Growth Enablers and improved performance in the machine-rolled cigar business in Europe <= two main drivers of the increased investments
– Growth Enablers: international sales of handmade cigars (outside of the US), retail stores and Next Generation Products (NGPs; including distribution of third-party products)
FY23. Net sales: kr.8.7Bn (+0.3% on organic basis); EBITDA margin: 24.1% (-1.8pp); FCF (before acquisitions): kr.1.05Bn (down kr.0.2Bn); adj. EPS: kr.14.4
– Net sales from the Growth Enablers: accounted for close to 10% of net sales in Q4 2023 (compared with 5% in Q4 2022 and 8% in Q3 2023)
FY24 Guidance
– Net sales: kr.8.8-9.1Bn (FY23: kr.8.7Bn; +3% growth based on the mid-point); all three commercial divisions delivering sales growth (highest growth in Europe Branded driven by increasing sales of NGPs and pricing in the core categories)
– EBITDA margin in the range of 22-24% (FY23: 24.1%); negatively impacted by the increased investments in the Growth Enablers, cost inflation and mix deterioration partly offset by pricing and cost optimization
– FCF: kr. 0.8-1.0Bn (negatively impacted by up to kr.300Mn in special investments)
– Adjusted EPS: kr.12.5-14.5 (FY23: kr.14.4) => down by 6% based on the mid-point
Key announcement highlights
– Leverage ratio: 1.9x (vs. 2.1x at the end of Q3 2023)
– Capital Allocation: dividend increased by 2% to kr.8.40 (in addition to the kr.850Mn ongoing share buy-back program)
– STG’s Ambition: Grow the size of the business through acquisitions, geographical expansion and NGPs
– STG completed the acquisition of the Alec Bradley cigar business in March 2023 and XQS International’s NGP (pouch) business in May 2023
– Cigars – USA: Consumption of handmade cigars has still not stabilized following the strong growth during the pandemic, whereas the performance for machine-rolled cigars improved during Q4 2023. Two new retail cigar Superstores opened in 2023 (both located in Texas), bringing the total number of Superstores in the US to 9. Additional openings expected in 2024
– Cigars – International: Sales of handmade cigars continue to deliver double-digit growth. Further expansion of consumer touch-points planned
– NGPs: Roll-out to additional markets planned => XQS (nicotine pouches), STRÖM (non-tobacco, nicotine pouches launched in Sweden in 2022) and !act (a non-tobacco, non-nicotine pouches launched in Denmark in 2023)
“Both the top-line and bottom-line under pressure”
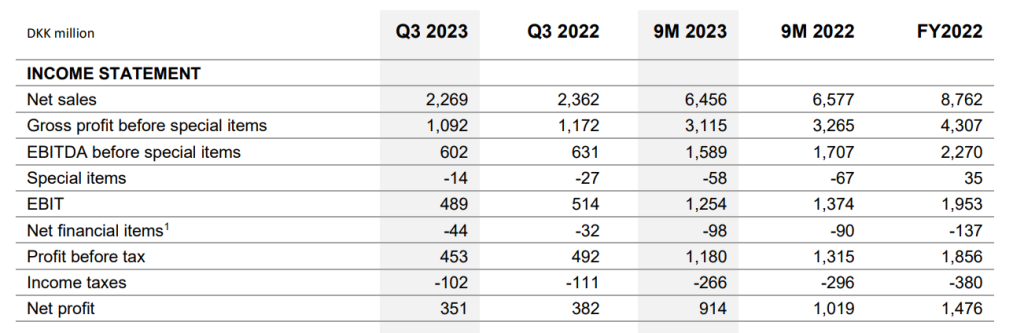
Both net revenue (-3.9% reported; -1.1% organic) and EBITDA (-4.6% reported, before special items) are under pressure, mainly due to softer cigar volumes (partly offset by pricing), trade inventory adjustments in the US and persistent market share decline in Europe.
Key announcement highlights:
– Increasing sales from Growth Enablers (accounting 8% of total sales): retail stores (now 9 Superstores in the US), NGPs (including online sales of ZYN in the US) and international sales of handmade cigars (YTD net sales growth of 25+%)
– 3 NGPs: Versa, the hemp product in the US (2021); STRÖM, non-tobacco, nicotine pouch in Sweden (2022); !act, non-tobacco, non-nicotine pouch in Denmark (2023)
– Double-digit net sales growth from XQS nicotine pouches (acquired in May 2023, primarily sold in Sweden)
– Still assessing NGP roll-out to additional markets and whether the STG’s presence in the NGP categories is viable and profitable in the mid to long term
– Adjusted EPS: kr.4.1 (vs. kr.4.4 in Q3 2022)
– New share buy-back program of a total value of up to kr.850Mn running to the end of Feb 2025.
– FY23 guidance remains unchanged (see below)
Q2 2023 Results4
“Both the top-line and bottom-line under pressure”
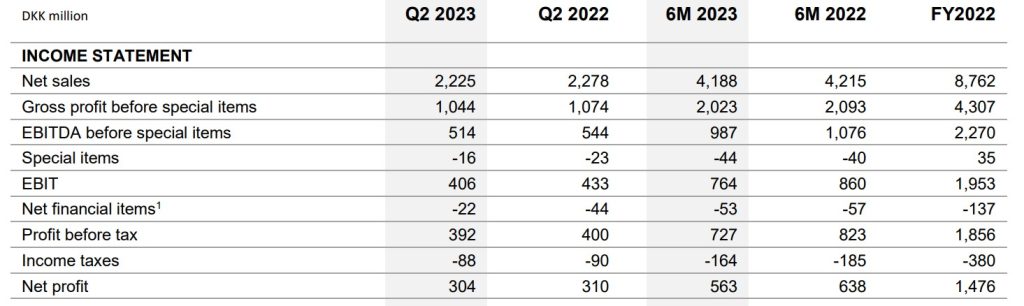
Both net revenue (-2.3% reported; -1.8% organic) and EBITDA (-5.5% reported, before special items; -2.9% organic) are under pressure, mainly due to trade inventory adjustments, unfavorable market share progression in Europe and delayed store openings in the US.
FY23 Guidance
– Net sales: kr.8.7-9.0Bn (initial guidance: kr.9.0-9.3Bn)
– EBITDA margin: 23.5-24.5% (initial: 24-25%)
– Free cash flow: kr.1.1-1.3Bn (initial: kr.1.2-1.4Bn)
– Adjusted EPS: kr.14.0-16.0 (initial: kr.14.5-16.5)
NGP Initiatives
STG is actively exploring the opportunities in NGP/RRP and Beyond Nicotine categories. In May 2023, STG acquired (substantially) all assets of XQS – a company active in smoke-free products (nicotine pouches), primarily in Sweden. In 2022, XQS reported kr50Mn net sales (with a low single-digit EBITDA margin) and 3Mn cans sales volume. Moreover, in April 2023, STG launched !act, a caffeine pouch product without tobacco/nicotine, in Denmark. STG considers roll-out of XQS and !act to additional markets.
However, STG also notes that they are “assessing whether their presence in the NGPs is viable and profitable in the mid- to long-term”.


References:

