


Ahead of the Q1 2025 Earnings release
Release date: April 23, 2025 (before the opening bell)
Revenue: $9.14 billion expected (+4% vs. $8.79 billion in Q1 2024)
EPS: $1.61 expected (+7.3% vs. $1.50 in Q1 2024)
Latest guidance – EPS: $1.58 to $1.63 (including ¢4 adverse FX)
Ahead of the earnings, the unanimous expectation is the continuation of PMI’s industry-leading, strong financial delivery (revenue +9.8%, adjusted EPS+9.3%, volume +2.9% in FY24). Sell-side analysts are rushing to increase their price targets before the Q1 2025 release. Adjustments since the begining of April 2025: Citigroup $180 ($163), JP Morgan $165 ($160), Stifel $168 ($160), UBS $130 ($120) and Deutsche Bank $170 ($142). PMI trades at around $160 (- just below the all-time high of $163.1).
Q1 2025 Results
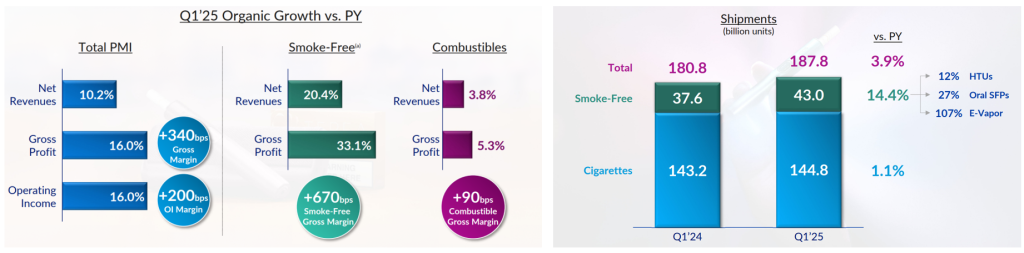
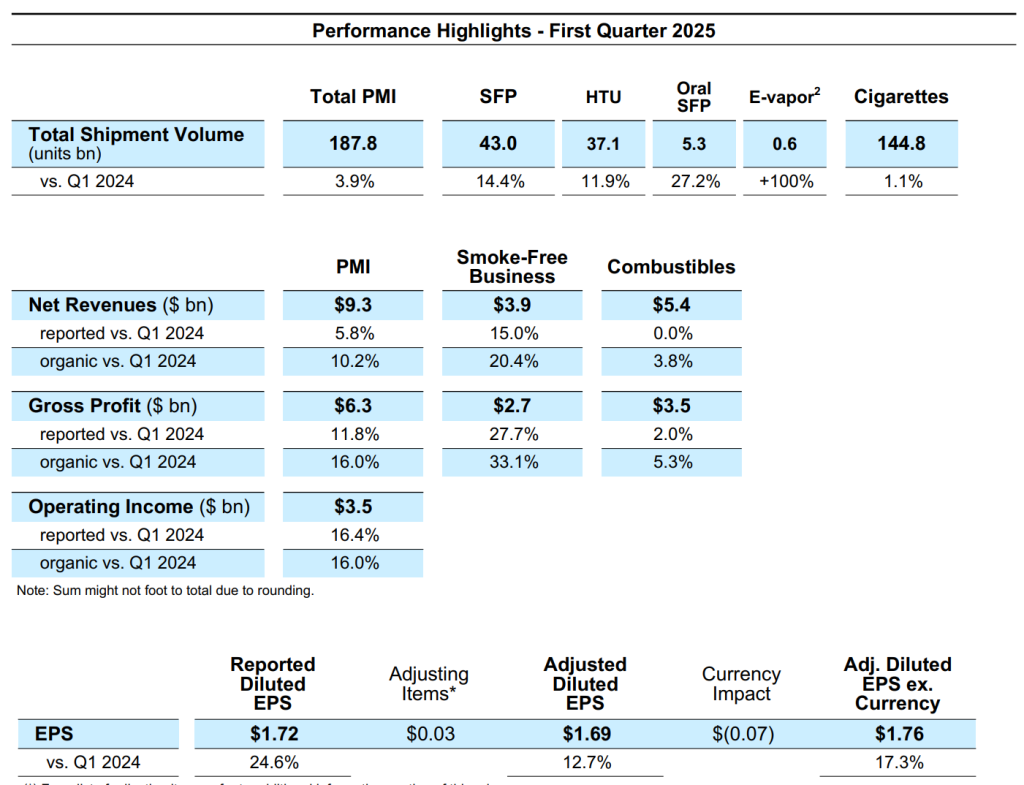
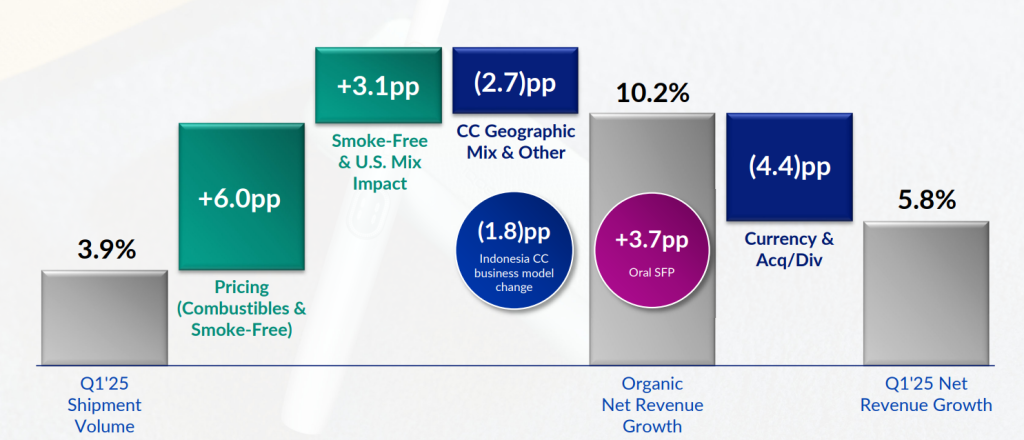
Adjusted Net Revenue: up +5.8% to $9.3Bn (vs. $9.14Bn expected; +10.2% organic basis; favorable pricing, mainly driven by combustibles, and favorable volume/mix, mainly driven by higher smoke-free volume, partially offset by unfavorable cigarette mix)
Adjusted EPS: up +12.7% to $1.69 (vs. $1.61 expected; +17.3% ex-FX)
Adjusted Operating Income: up +12.8% to $3.79 billion (+16% on an organic basis)
Adjusted Operating Income margin: 40.7% (up +2.5pp vs. Q1 2024; up +2.0pp on an organic basis)
Total volume: up +3.9% to 187.8 billion (Heated tobacco volume: +11.9% to 37.1 billion; oral nicotine volume: +27.2% to 5.3 billion; e-vapor volume +107% to 0.6 billion; cigarette volume: +1.1% to 144.8 billion)
Smoke-free weight: 42% by revenue; 22.9% by volume
Smoke-free business (SFB)
– Accounts for 42% of total net revenues and 44% of total gross profit in Q1 2025
– Shipment volume up +14.4%, net revenue up +15.0% (20.4% on an organic basis), gross profit up +27.7% (33.1% on on organic basis)
– Smoke-free products (SFPs) are in 95 markets; multicategory smoke-free portfolio deployed in 46 markets (30 markets with 2 SFPs, 16 markets with 3 SFPs)
– Heated tobacco (IQOS): IQOS as the second largest nicotine franchise in markets where present (share up +1.0pp to cross over 9%); heat-not-burn (HnB)category volume share of 77%. HnB in-market sales (IMS) volume up +9.4%. In Japan, IMS up +9.3%. IQOS market share increased by +3.0pp to a record 32.2%. In March 2025, the overall HnB category exceeded 50% of total nicotine offtake share in 13 major cities and 8 prefectures. In Europe, IQOS market share increased by 1.2pp reaching a record 11.4%. Adjusted IMS up +7.4%. Double-digit growth in many markets, including at least high-teens growth in Spain, Germany, Bulgaria and Greece, strongly outweighing the impact of the EU characterizing flavor ban, notably in Italy. IQOS HnB offtake share exceeded 30% in six key cities, including Budapest, Athens and Rome. Outside Europe and Japan, strong IMS growth in key cities across the globe, including Jakarta, Seoul and Mexico City.
– E-vapor (VEEV): Shipment volume more than doubled, driven by Europe, and further gross margin expansion
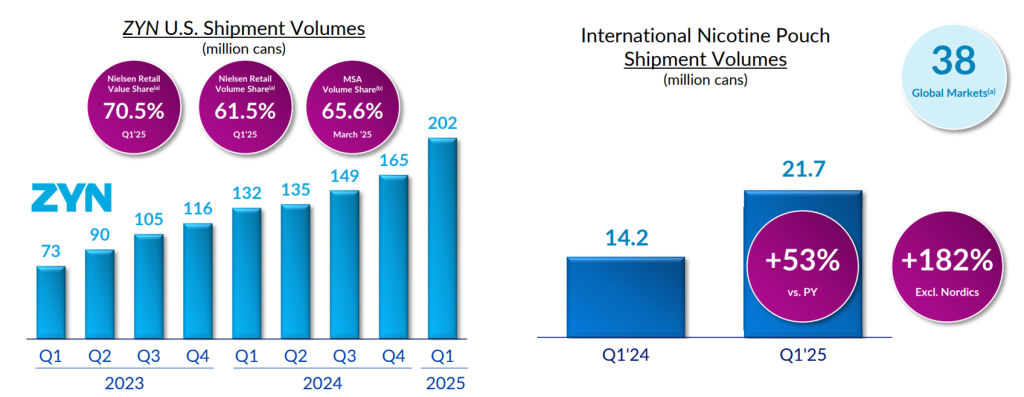
– Modern oral nicotine (ZYN): SFP: Shipment volume up by +27.2% in pouches (up +31.0% in cans), fueled by ZYN nicotine pouch growth in the U.S. (+53.8% to 202.4 million cans). Production capacity increased ahead of schedule in late-March, enabling some initial replenishment of distributor inventories. Demand remains strong. Full supply normalization targeted in Q3 2025. Outside the U.S., nicotine pouch volume in cans up by +53%, with momentum in a number of emerging markets, such as Pakistan and South Africa, as well as recent national launches across Europe, including the UK, Poland and Italy. Global Travel Retail business (including airports) also continues to be an important growth driver.
Combustibles
– Volume growth coupled with strong pricing, partly offset by negative geographic mix, resulted
in flat net revenues (up +3.8% on an organic basis) and another quarter of robust gross profit performance with growth of 2.0% (up +5.3% on an organic basis)
– Global brands portfolio, driven by Marlboro, achieved further market share gains and overall cigarette category share increased by 0.4pp to 24.8%
– Decided not to pursue a sale or separation of the U.S. cigar business at this time
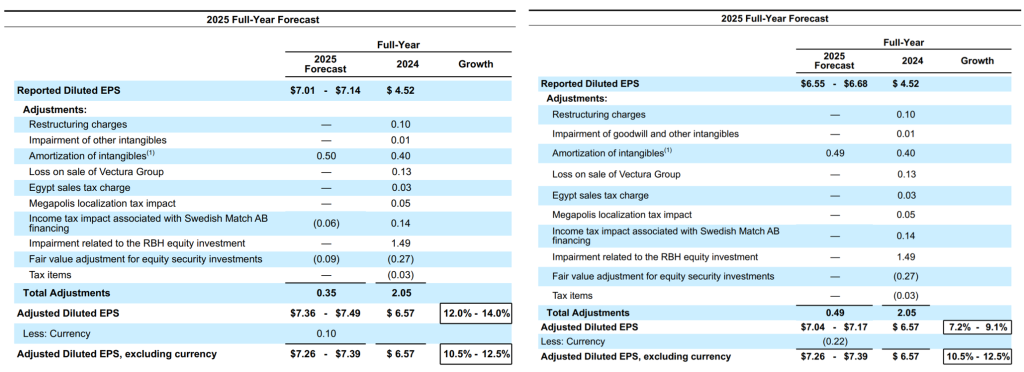
FY25 Guidance: $0.32 increase based on favorable FX
– Reported diluted EPS: in a range of $7.01 to $7.14 (increased up $0.46)
– Negative Adjustments: $0.35 per share (reduced $0.14 from $0.49 per share)
– Adjusted EPS: in a range of $7.36 to $7.49, representing a projected growth of 12.0% to 14.0% (increased by $0.32, previously: 7.2%-9.1% growth)
– FX impact: revised from $0.22 unfavorable to $0.10 favorable
– Adjusted EPS, at constant FX: in a range of $7.26 to $7.39, representing a projected growth of 10.5% to 12.5% (no change)
– Guidance excludes restructuring charges expected to be incurred in Q2 2025 with respect to manufacturing footprint optimization in Germany: pre-tax impact to be around €200 million ($230 million)
FY25 Assumptions
– International industry (ex-China&US) volume decline: ~1%
– PMI volume growth: +2% driven by smoke-free products volume growth of 12% to 14%
– Heated tobacco volume growth: 10% to 12%
– U.S. nicotine pouch shipment volume: 800 to 840 million cans, representing growth of 38% to 45% (increased by 20 million cans, previously: 780 to 820 million cans, representing a growth of 34%-41%)
– Net revenue growth: 6% to 8% on an organic basis
– Organic operating income growth: 10.5% to 12.5%
– Amortization of acquired intangibles: $0.50 per share, including the amortization of IQOS commercialization rights in the U.S.
– Effective tax rate: 22.5% to 23.5%
– Operating cash flow: more than $11 billion, including the German tax surcharge and U.S. Tax Cuts & Jobs Act payments of $1 billion (previously: around $11 billion)
– CAPEX: $1.5 billion, including further investments in ZYN capacity in the U.S.
– Leverage: further improvement towards the target ratio of around 2x by the end of 2026 (no share repurchases)
– No dividend income from the Canadian affiliate, RBH
– Q2 2025 EPS: $1.80 to $1.85, including a favorable FX impact of 6 cents
Summary
As it was the case throughout FY24, PMI’s financial delivery remained very strong also in Q1 2025. Overall, net revenue growth of +10.2% on an organic basis in Q1 2025 revalidates PMI’s industry-leading operational performance: organic volume growth (+3.9pp in Q1 2024) coupled with strong pricing (+6.0pp) and favorable product mix (+3.1pp; transition to smoke-free products with higher net unit revenue and increasing U.S. revenue), partially held back by the geographical mix (-2.7pp; cigarette volume weight shifting to emerging markets).
Moreover, thanks to the recent weakness in US$ (especially, against € and JPY), PMI’s projected currency variance on FY25 EPS swings from an unfavorable $0.22 (initial foreceast; February 6, 2025) to a favorable $0.10 – positive FX variance is a first for PMI in a long time.

