


Ahead of the Q2 2025 Earnings release
Release date: July 22, 2025 (before the opening bell)
Revenue: $10.32 billion expected (+9% vs. $9.47 billion in Q2 2024)
EPS: $1.86 expected (+17% vs. $1.59 in Q2 2024)
Latest guidance – Q2 2025 EPS: $1.80 to $1.85 (including ¢6 favorable FX)
Ahead of the earnings, the unanimous expectation is the continuation of PMI’s industry-leading, strong financial delivery (organic revenue +10.2%, adjusted EPS+12.7%, volume +3.9% in Q1 2025). Sell-side analysts are rushing to increase their price targets before the Q2 2025 release. Adjustments since the begining of July 2025: Goldman Sachs $200 ($190), UBS $181 ($170), Citigroup $200 ($188), JP Morgan $190 ($175), Barclays $225 ($200) and Jefferies $220 (initiated). PMI trades at around $180 (- just below the all-time high of $186.7).
Q2 2025 Results
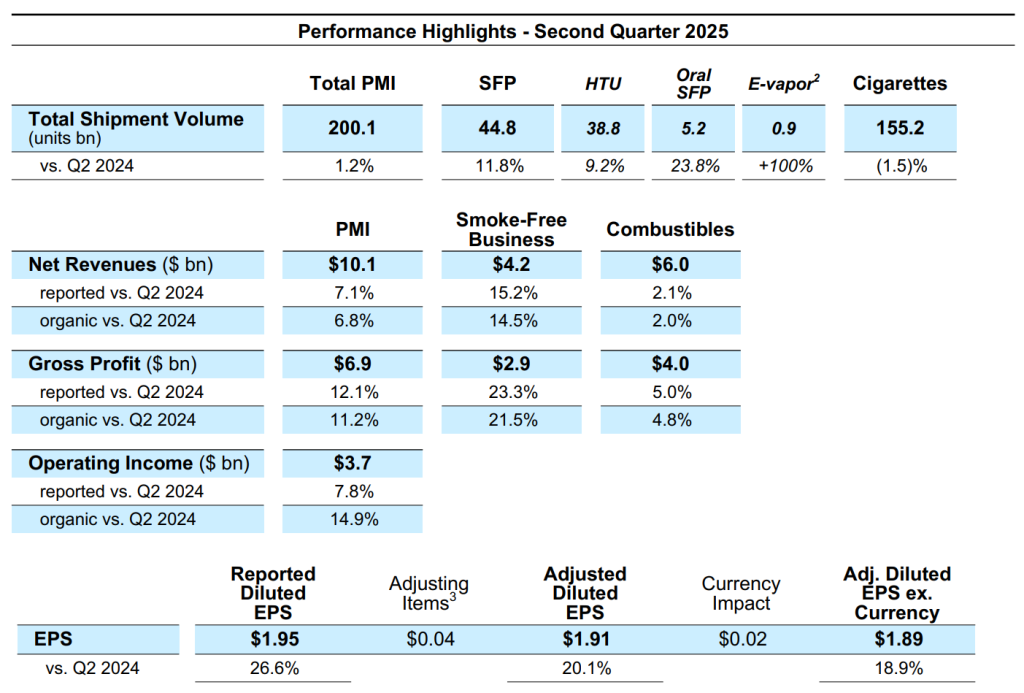
Adjusted Net Revenue: up +7.1% to $10.14Bn (vs. $10.32Bn expected; +6.8% organic basis; favorable pricing, mainly driven by combustibles, and favorable volume/mix, mainly driven by higher smoke-free volume, partially offset by unfavorable cigarette mix)
Adjusted EPS: up +20.1% to $1.91 (vs. $1.86 expected; +18.9% ex-FX)
Adjusted Operating Income: up +16.1% to $4.25 billion (+14.9% on an organic basis)
Adjusted Operating Income margin: 41.9% (up +3.3pp vs. Q2 2024; up +3.0pp on an organic basis)
Total volume: up +1.2% to 200.1 billion (Heated tobacco volume: +9.2% to 38.8 billion; oral nicotine volume: +23.8% to 5.2 billion; e-vapor volume +100% to 0.9billion; cigarette volume: -1.5% to 155.2 billion)
Smoke-free weight: 41% by revenue; 22.4% by volume
Smoke-free business (SFB)
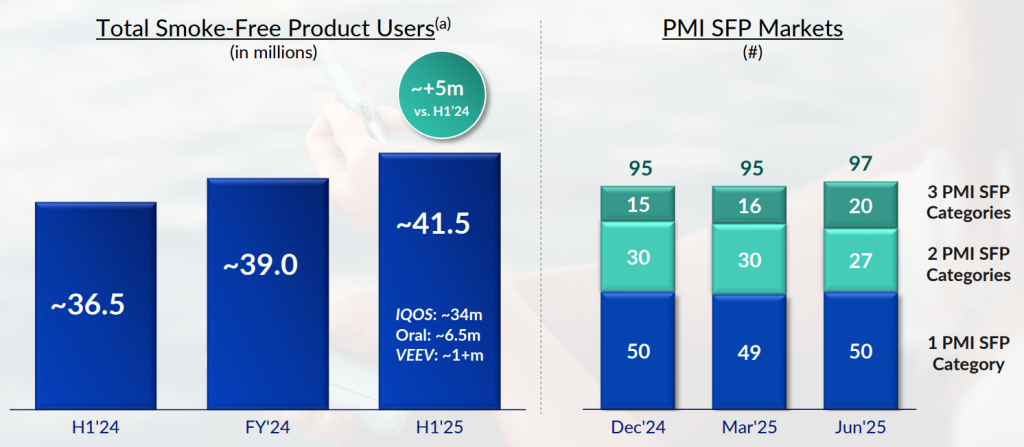
– Accounts for 41% of total net revenues (up by 2.9pp vs. Q2 2024) and over 42% of total gross profit (up by 3.8pp vs. Q2 2024). Smoke-free products are now available in 97 markets, nearly half of which have at least two of flagship brands (IQOS, ZYN and VEEV) available for sale and 20 of which have all three
– 41.5 million smoke-free users: 34 million IQOS + 6.5 million oral tobacco/nicotine + 1 million VEEV (what about dual users?)
– Smoke-free shipment volume up by 11.8%, net revenue up by 15.2% (14.5% organically) and
gross profit up by 23.3% (21.5% organically)
– Heated tobacco (IQOS): More than US$3 billion in quarterly net revenue. Second largest nicotine brand in markets where present (+1.0pp share gain, reaching 9.2% share). 76% global category volume share. Heated tobacco in-market sales (IMS) volume growth reaccelerated back to double-digit growth of 11.4%, driven by commercial initiatives, and notable improvement in Europe as the impact of the characterizing flavor ban subsides in affected markets. Japan: 10 million users in Japan. IQOS market share up by 2.3pp to 31.7% with both TEREA and SENTIA further strengthening their #1 and #3 positions despite increased competitive activity. IMS up +7.8% against a strong prior year comparator, which included the introduction of ILUMA i. Europe: IMS growth reaccelerated to 9.1%, with Italy a notable strong performer as well as broad-based growth across markets including Germany, Greece, Romania, Bulgaria and Spain. Continued roll-out of ILUMA i and expansion of the consumables portfolio, including the further roll-out of DELIA and new variants of tobacco-free LEVIA. IQOS HTU adjusted market share increased by 1.2pp to 10.9%, with offtake share exceeding 20% in key cities of 12 markets. Rest of the World: Strong adjusted IMS growth continued and offtake share increased in key cities across the globe, including Jakarta, Mexico City, Tunis, Riyadh, Kuala Lumpur, and Seoul. A broader roll-out of BONDS by IQOS commenced in Indonesia
– E-vapor (VEEV): Now available in 42 markets. Shipment volumes more than doubled, driven by Europe. Within the closed pods segment, VEEV holds the #1 position in 6 European markets, including Greece and Italy. Recently launched VEEV inPrime, which offers superior consumer experience and an optimized pod cost.
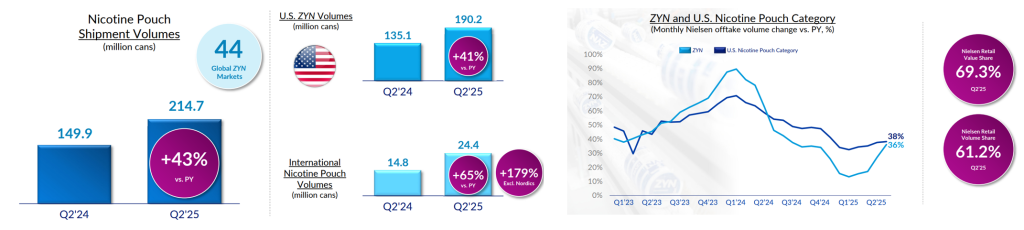
– Modern oral nicotine (ZYN): Now available in 44 markets. Nicotine pouch volume more than doubled outside the U.S. and Nordics. USA: Shipment up +41% to 190 million cans [note: this is lower than expected]. Offtake growth accelerated to 26% in Q2 2025 and 36% in June 2025. Restocking effectively completed in H1 2025, with the estimated impact slightly lower than initially expected.
Combustibles
– Volume decline as expected. Net revenue up +2.1% (up +2.0% organically), fueled by strong pricing, partly offset by negative mix dynamics. Gross profit up +5.0% (up +4.8% organically)
– Marlboro continues to gain market share, achieving its highest quarterly market share since the 2008 spin-off. Overall cigarette category share broadly stable.
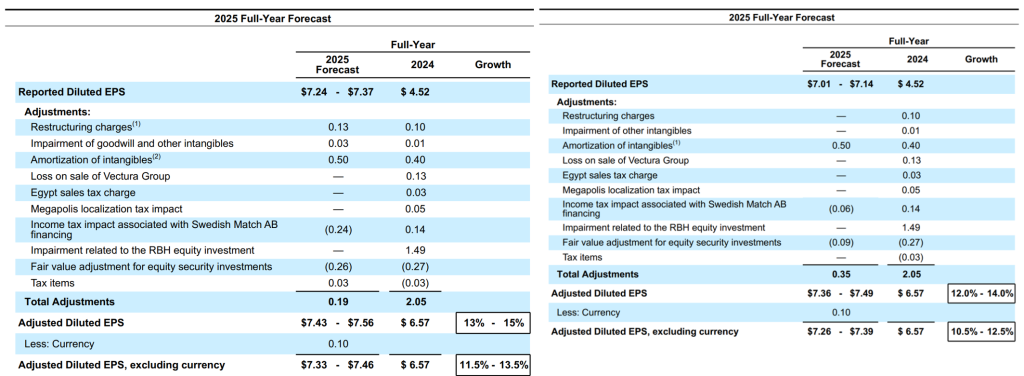
FY25 Guidance: raised by $0.07 (from 12%-14% to 13%-15%)
– Reported diluted EPS: in a range of $7.24 to $7.37 (vs. $4.52 in 2024)
– Adjusted EPS: in a range of $7.43 to $7.56, excluding a total adjustment of $0.19 per share and representing a growth rate of 13% to 15% (vs. $6.57 in 2024)
– Adjusted EPS, at constant FX: in a range of $7.33 to $7.46, excluding a total favorable FX of $0.10 per share and representing a growth rate of 11.5% to 13.5% (vs. $6.57 in 2024)
FY25 Assumptions
– International industry (ex-China&US) volume decline: ~1% (no change)
– PMI volume growth: +1% (before: +2%) driven by smoke-free products volume growth of 12% to 14% and offsetting cigarette volume decline of around 2%.
– Heated tobacco volume growth: 10% to 12%
– U.S. nicotine pouch shipment volume: 800 to 840 million cans, representing growth of 38% to 45% (no change)
– Net revenue growth: 6% to 8% on an organic basis
– Organic operating income growth: 11% to 12.5 (before: 10.5% to 12.5%)
– Amortization of acquired intangibles: $0.50 per share, including the amortization of IQOS commercialization rights in the U.S.
– Effective tax rate: 22% to 23% (before: 22.5% to 23.5%)
– Operating cash flow: $11.5 billion (before: more than $11 billion)
– CAPEX: $1.6 billion, almost entirely due to investments supporting the smoke-free business (before: $1.5 billion)
– Leverage: further improvement towards the target ratio of around 2x by the end of 2026 (no share repurchases)
– No dividend income from the Canadian affiliate, RBH
– Q3 2025 EPS: $2.08 to $2.13, including a favorable FX impact of 5 cents
Summary
PMI’s financial delivery remained strong in Q2 2025: overall, +1.2% volume, +6.8% net revenue and +14.9% operating income growth, on an organic basis, are industry-leading figures. Although ZYN USA shipments are slightly below expected, PMI kept its FY25 target of 800-840 million cans. Heated tobacco growth is at the border of single-digit and double-digit range as expected. The main negative suprise is weaker than expected combustible volume, which led the FY25 volume growth guidance to lowered to +1% from +2%.
However, trading at historic record multiples, expectations from PMI results were unrealistically inflated heading into the Q2 2025 Results. Moreover, although ZYN USA has only 6.5% weight in PMI’s revenue, it has a very large impact on its equity value. Market would not like even the slighest sense of weakness. Despite solid results, a significant sell-off in PMI shares could be expected – which would offer an entry point for long-term investors.

