


Key Business Metrics: Q1 20261
– New reporting structure: Standalone (core businesses) vs. Consolidated (including ITC Infotech India Limited, Surya Nepal Private Limited and ITC Hotels Limited)
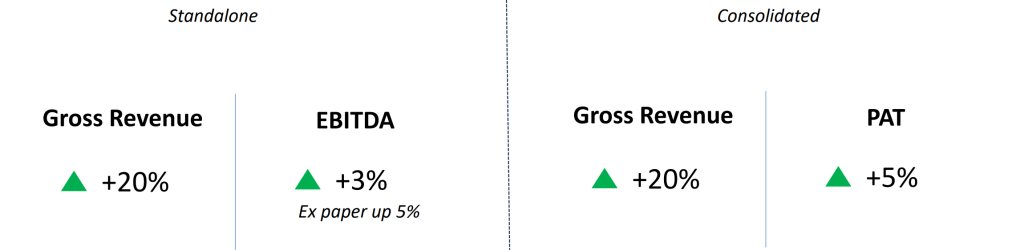
– Gross Revenue is up +20% driven by Cigarettes, Agri Business and FMCG (ex-Notebooks)
– EBITDA is up +3% (ex-Paper is up +5%); Profit before tax: +1.9%
– Q1 2026 EPS (basic): ₹3.93 (up +1.8%)
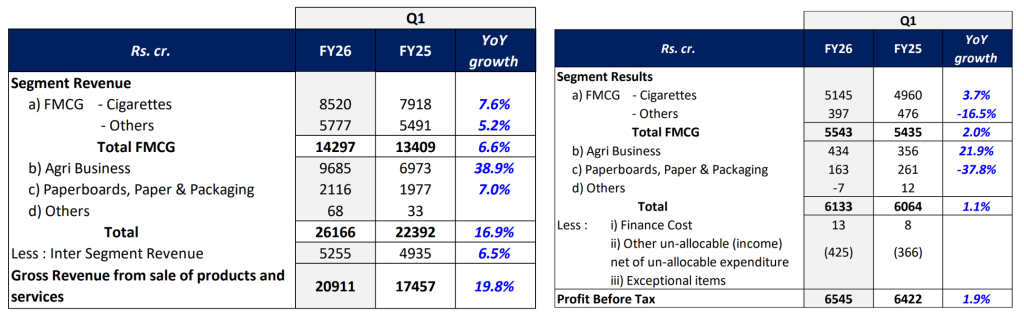
Q1 2026 Segment Highlights
Cigarette Segment: (32.6% weight in gross revenue, 83.9% weight in operating profit)
– Net segment revenue and operating profit are up +7.6% (net of Excise Duty/NCCD on sales: +7.7%) and +3.7%, respectively
– Tax stability supporting volume recovery from illicit trade. Market position reinforced through focused product portfolio & commercial interventions. Premium segment & new innovations continue to gain robust traction
– Consumption of high-cost leaf inventory weighs on margins; partly mitigated through improved product mix and cost management interventions. Moderation in leaf tobacco procurement prices witnessed in current crop cycle
– Union Budget 2025: Amendments to Central Goods and Services Tax (CGST) Act that enable a Track & Trace mechanism to strengthen the efforts to control illicit trade
Other Segments:
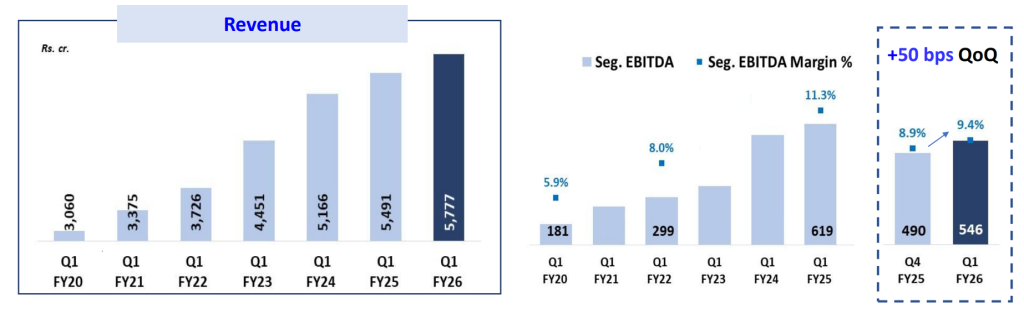
– FMCG (revenue is up +5.2%, operating profit is down -16.5%): Pick up in growth momentum; up +8.6% ex-Notebooks. Notebook segment continues to operate under deflationary conditions due to low-priced paper imports & price pressure imposed by local/regional competitiors. Premium portfolio & New Generation channels sustain high growth trajectory. Digital-first & Organic portfolio reaches ₹1,000 crore annual run rate. Segment EBITDA margin up +50 bps to 9.4% on sequential basis. Input prices of major commodities remain elevated; impact mitigated through focused cost management initiatives, premiumisation & calibrated pricing actions. Trade & marketing investments sustained at competitive levels to support growth and market position.
– Agri Business segment (revenue is up +38.9%, operating profit is up +21.9%): Strong growth in tobacco leaf exports (crop development expertise, good product quality & strong customer relationships). Focus on scaling up Value-added agriculture portfolio: 2.2x in revenue in 4 years. Strategic sourcing support for Foods & Cigarettes Businesses. Progressive scale up in exports of Nicotine & Nicotine derivate products from the Mysuru factory
– Paperboard, Paper & Packaging (revenue is up +7%, operating profit is down -37.8%): Negatively impacted by low-priced Chinese & Indonesian supplies in global markets. Wood prices remain elevated. Sustainable paperboards / packaging solutions portfolio continues to grow fast; over 3x in revenue in 4 years.
Summary:
Subdued demand conditions in the overall consumption (FMCG) space, increasing input costs (leaf, wood etc.) as well as the circumstantial factors have been putting pressure on ITC’s profitability and share price performance in the past 12-18 months. Most recently, ITC shares are stuck in a narrow range, above the key ₹400 level and more than 15% below its all-time high (₹528 print; ₹499 adjusted for the ITC Hotels spin-off). The ₹400 level has served as a strong support on the downside as the investors wait for the business environment to improve and/or ITC Management’s interventions to pay off.
Q1 2026 Results could been seen as an early sign of turnaround. The most noteworthy development is the 50bps sequential improvement in FMCG EBITDA margin to 9.4% – altough it is still well below the 11.3% reported in Q1 2025. Cigarette segment is perfroming well; however, profit growth still lags the revenue growth. Explosive growth in Agricultural Business rendered this segment the biggest revenue contributor to the ITC Results in Q1 2026; however, the low profitability of the business limits the impact of the segment’s explosive growth on the consolidated bottom-line. Paper segment continues to be under pressure with no signs of an improvement in profitability.
We will have to wait & see to what extent the market will be convinced with the turnaround. In any case, we assume ₹400 will continue to serve as a strong support on the downside and there are more reasons to believe that the bottom is in for the ITC shares.
References:

