


Q2 2025 Results1
“Solid financial delivery, driven by the international cigarette division”
Revenue: ₩1.55 trillion (+8.7% year-on-year) => record-high first half revenue, surpassing ₩3 trillion for the first-time, driven by international cigarette segment and higher real estate development income
EBITDA: ₩421 billion (+9.7%)
EBITDA Margin: 27.2% (+0.3pp)
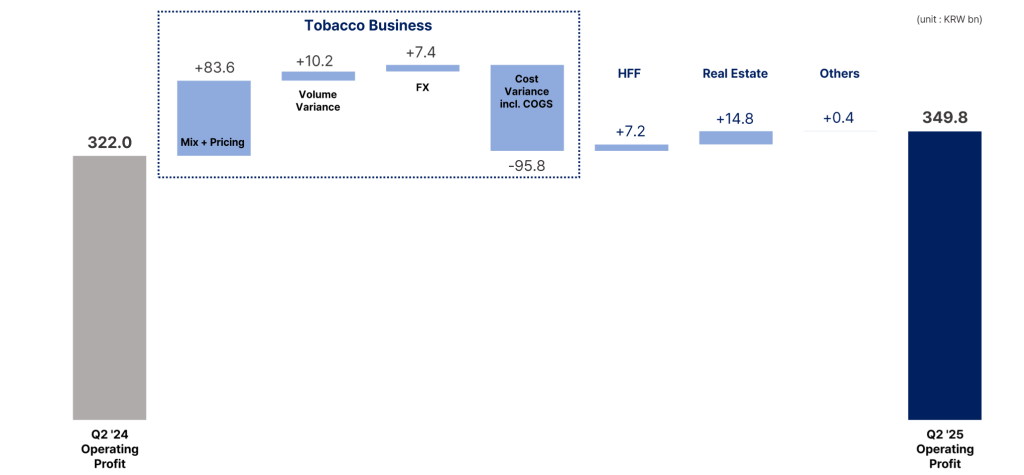
Operating Profit: ₩349.8 billion (+8.6%)
Net Income: ₩143.5 billion (-54.1%)
EPS: ₩1,328 (-51.1%)
Results: Tobacco Division
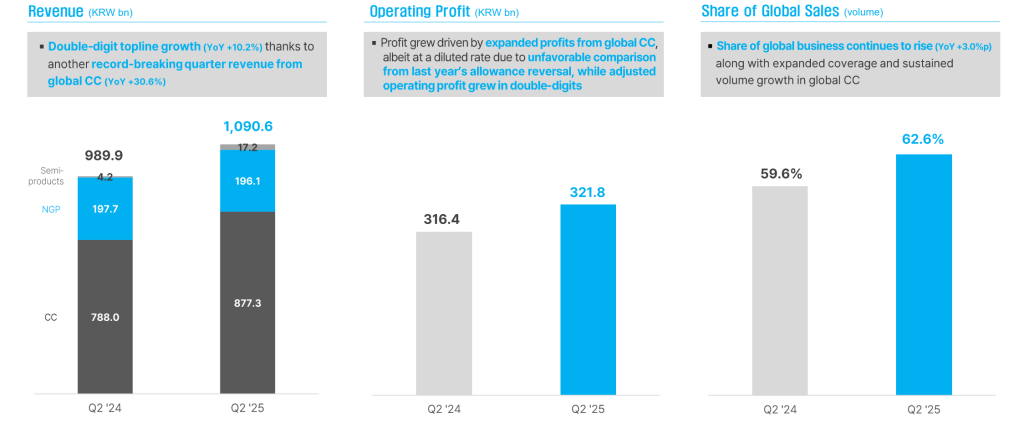
Key announcement highlights for Q2 2025 (tobacco business only):
– Revenue +10.2% to ₩1,091 billion; Operating Profit +1.7% to ₩321.8 billion => Margin down from 32% to 29.5% (-2.5pp); reported figures affected from the allowance reversal in Q2 2024; adjusted operating profit up double-digits
– Overall volume +3.2% to 30.27Bn sticks (cigarettes +3.4% to 26.5Bn sticks)
– NGP revenue weight in total tobacco: down from 20% to 18% (impacted by the device supply distruption in the beginning of 2025)
– International (ex-Korea) revenue: 62.6% of the total (+3.2pp)
– Cigarettes – Korea (37.4% weight in tobacco revenue): -5.1% volume decline to 9.8Bn sticks due to the market contraction (-4.8%). KT&G SoM in H1 2025 up +0.9pp to 67.6% vs. FY24. Revenue down -4.8% with pricing only partially offsetting volume decline
– Cigarettes – International (44.2% weight in tobacco revenue): +9.1% volume growth (to 16.7Bn sticks). Revenue up +30.6%, driven by strong pricing and improved product mix in addition to the volume growth. Record quarterly revenue and volume
Results: NGP Segment
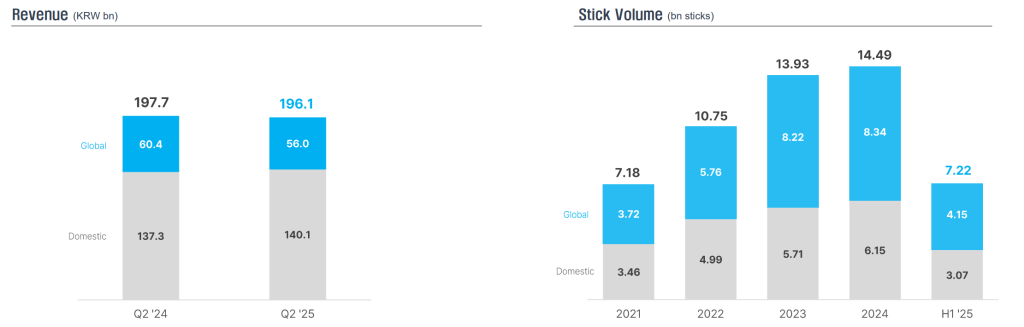
– Overall NGP volume: +2.4% to 3.77Bn sticks in Q2 2025
– NGP – Korea (12.9% weight in tobacco revenue): Leadership is maintained with 45.8% SoS (+0.1pp) in H1 2025 despite fierce competition (e.g. more aggressive promotions offered by PMI and BAT) and device supply disruption. Volume is flat (to 1.53Bn sticks), revenue is up +2%. NGP Penetration: 22.8% of the total market in H1 2025 (+1.7pp)
– NGP – International (2.9% weight in tobacco revenue, Global Partnership with Philip Morris International): Revenue is down -7.3% lower due to the impact from device supply disruption. Volume is up +5.6% (to 2.24Bn sticks)
Others divisions:
– Health-Functional Food: Revenue down -16.8% to ₩220.6 billion due to the portfolio realignment towards channels/products with higher margin; Operating profit up from a loss of ₩1billion to a profit of ₩6.2billion
– Real Estate: Revenue up +78.5 to ₩143.7 billion as construction progresses on development projects; Operating profit up x6 to ₩17.7billion
Capital Allocation:
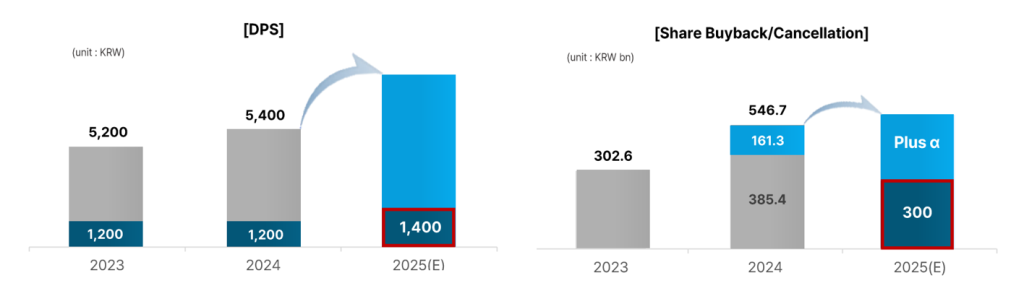
– Interim dividend increased by ₩200 to ₩1,400
– ₩300 billion worth of shares to be cancelled immidiately after re-purchase in 2025; 53% progress in the ₩1,300 billion 2024-27 share repurchase plan; Additional share repurchases in 2025 via divesting non-core assets
Summary:
KT&G delivered an impressive ~9% revenue and operating profit growth in Q1 2025, mostly thanks to the great volume/pricing/revenue performance of the international cigarette division. Domestic tobacco business is under pressure due to the acceleration in cigarette volume decline and intensifying competition in NGPs; nevertheless, KT&G’s market share performance is solid. The Global Partnership with Philip Morris International is still a concern despite +5.6% volume growth in consumables. Lil revenue in South Korea alone in 2.5x its international revenue.
Just below the ₩150,00 mark and at all-time highs, KT&G now trades at 15.5x FY25 EPS of ₩9,460. A further re-rating to 20x is possible, but dependent on the stabilization of the South Korean tobacco market, continuation of successful international expansion with cigarettes and better volume/revenue delivery from the Global Partnership with Philip Morris International (i.e. lil outside South Korea).
References:

