


Revenue: ¥947.2Bn (versus ¥901Bn expected)
EPS: ¥109 (versus ¥92.9 expected)
Starting from Q3 2025, the Pharmaceutical business is classified as discontinued operations
Top-line & Bottom-line Results – Tobacco Segment Only1
(Excluding Pharmaceuticals and Processed Food Segments. Tobacco Segment has a 92.5% weight in revenue and 100+% weight in adjusted operating companies income in Q3 2025. Adjusted figures, at constant currencies)
Revenue: +18.3% in Q3 2025, driven by a strong price/mix contribution from all clusters, volume growth in EMA (including the Vector Group volume) and RRP revenue growth (+42.6%)
Operating profit: +31.1% in Q3 2025, driven by core revenue growth and partially offset by higher investments towards heated tobacco and higher supply chain costs
Total Volume: +4.9% (up +4.0% when adjusted for inventory movements); Combustible volume: +4.2%; RRP volume: +40.1% (heated tobacco volume: +53.4%)
RRP weight – Q3 2025: 2.45% by volume and 4.05% by revenue (2.2% and 3.6%, respectively, in Q2 2025)

RRPs: Ploom (heated tobacco)
– Japan: Category reached 46.1% of the total tobacco industry size (on shipment basis). JT’s RRP volume (including hybrid products) increased by +27% and category share grew by +2.3ppt to reach 15.9% in YTD 2025. JT’s heated tobacco volume grew by +35% and category share grew by +2.7ppt to reach 14% in YTD2025 (category share in Q3 2025: 15.5%)
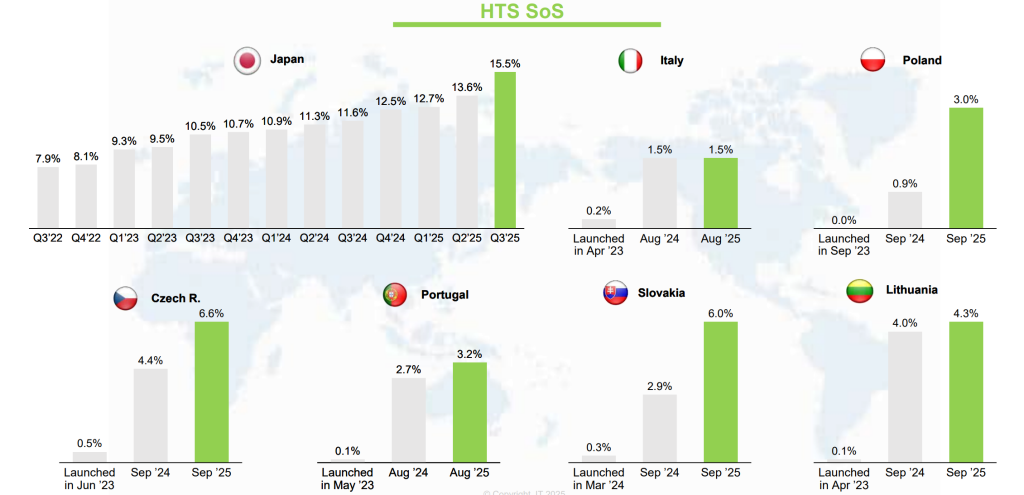
– Ploom’s category share in Italy (largest heated tobacco market in the EU) is flat at 1.5%. In other EU markets, Ploom attained 3.0% to 6.6% category share in 18-30 months after launch.
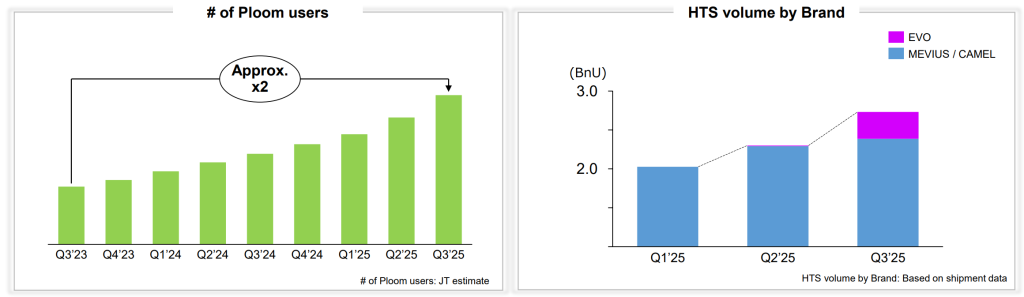
– Ploom AURA: Strong performance in Japan since the launch in May 2025. At the end of October, Ploom AURA is available in 8 markets with the aim to expand to ~15 markets by end of 2025. Ploom AURA drives faster Ploom user growth with higher new customer acquisition ratio compared to previous models. Premium Ploom AURA sticks, EVO, further accelerating heated tobacco volume growth
– Number of Ploom users almost doubled in two years
Regional Overview: Volume, Core Revenue (CR), Adjusted Operating Profit (AOP)
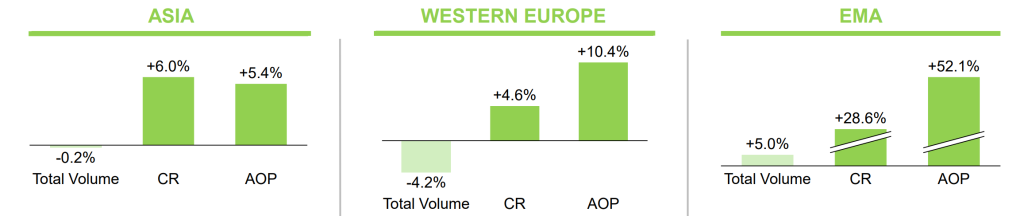
– Asia: Positive Price/mix contribution, notably from Bangladesh, Japan and the Philippines, partially offset by a negative volume variance, mainly in the Philippines and Taiwan. Strong RRP volume growth (+27.7%) mostly offsets the lower combustible volume (-2.2%), driven by industry volume contraction, notably in Japan and Taiwan. Market share gains in Bangladesh, Singapore, South Korea and Taiwan.
– Western Europe: Positive price/mix contribution, mainly in the Benelux, France, Italy, Portugal, Spain, Sweden and the UK, partially offset a negative volume variance, mainly in the Benelux, France and the UK. Volume decline (-4.2%) driven by industry volume contraction, primarily in Belgium, France, Netherlands and the UK. RRP volume up by +10.2%. Market share gains in Austria, France, Germany, Ireland, Italy, Lithuania, Netherlands, Portugal, Spain, Sweden, Switzerland and the UK
– EMA: Strong positive price/mix contribution, notably in Global Travel Retail, Jordan, Kazakhstan, Poland, Romania, Russia and Turkey, and favorable volume variance, mainly from the Vector Group inclusion, Global Travel Retail and Turkey. RRP volume up by +49.7%, notably driven by the Czech Republic, Kazakhstan, Poland, Slovakia and Global Travel Retail. Market share gains across the cluster, including in Algeria, Azerbaijan, Canada, the Czech Republic, Hungary, Iran, Kazakhstan, Lebanon, Montenegro, Poland, Romania, Serbia, the Slovak Republic, South Africa, Turkey and the USA.
– US Market (including Vector): Continued growth of LD (+25.6%), capturing consumers in the growing value segment. Combustibles market share up to 8.3% (+6.2pp), driven by LD and the continued momentum of Montego
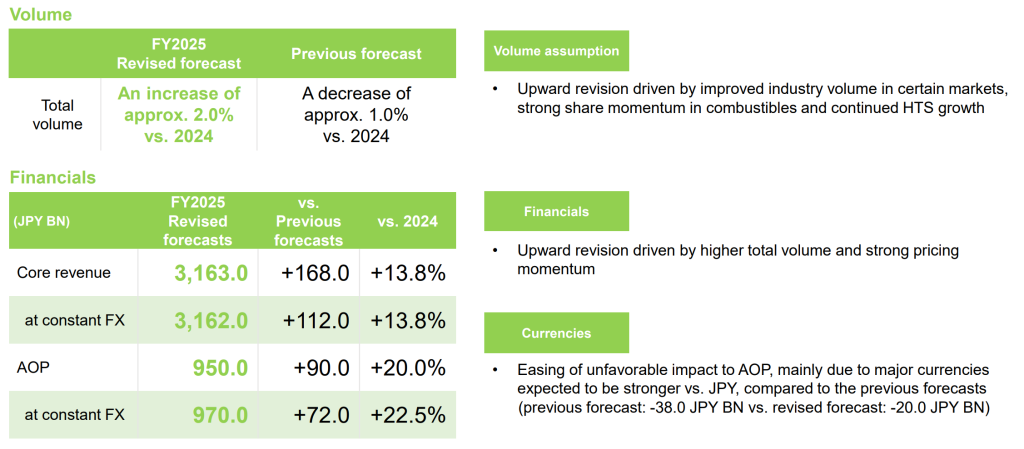
FY25 Guidance
– Core revenue and operating profit guidance increased by +13.8% and +22.5%, respectively, at constant FX
– Upward revision driven by improved industry volume in certain markets, share gains in combustibles, continued heated tobacco growth and strong pricing
Summary:
Overall, strong combustible pricing/mix and contribution from Vector Group helped JT deliver double-digit revenue and operating profit growth in Q3 2025. As noted before, FY25 is set to be an another year of strong growth. JT’s traditional business (combustibles) is in great shape – outperforming the Marlboro-owner, PMI.
On the RRP side, thanks to the geographical expansion of Ploom X and progressive category share gains in Japan, year-on-year volume growth in heated tobacco accelerated to +53.4%. Although there is a perceptible acceleration in the heated tobacco growth, driven by the Ploom AURA and EVO launch, it is yet to be seen whether the progress is in proportion to the outsized ¥650 billion ($4.25Bn investment) over the three-year period from 2025 to 2027, mostly in commercial initiatives. With only 4.1% of its revenue coming from RRPs (compared to 41% for PMI), JT still has a lot to prove in terms of portfolio transformation – or, a large room for future growth, if you prefer to be a relentless optimist.
References:

