


Top-line & Bottom-line results
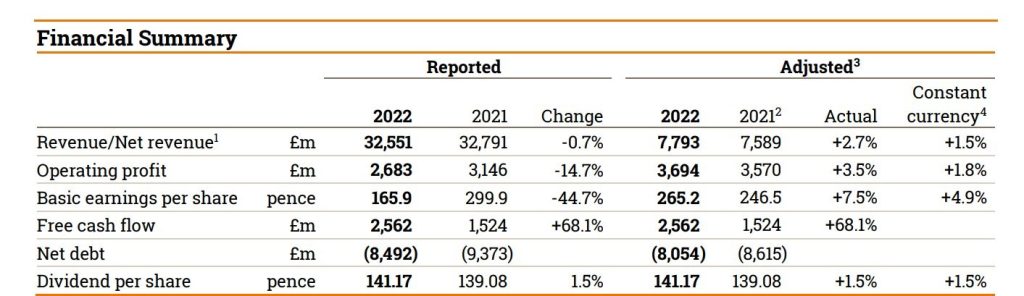
Adjusted, at constant currencies
Net revenue up +1.5% (NGP net revenue up +10.8%)
Operating profit up +1.8%
EPS up +4.9%
Key Highlights
– Aggregate SoM for top-5 combustible markets up 35bps (note: larger competitors are largely funneling their investment to RRP/NGPs)
– 90bps share gain in US combustibles (including the benefit from the KT&G exit); focus on the discount segments (premium value/discount, traditional discount, deep discount); salesforce expanded by 26%
– “Our HnB proposition, Pulze and iD, continued to perform well in our pilot markets of Czechia and Greece” (2.8% and 4.2% category share in Greece and Czechia, despite an extremely out-sized, non-replicable market support)
– Laggard in transformation to NGP/RRPs (alongside with JT and Altria)
| Company | Weight of NGP revenue in total | Data |
| PMI | 30.4% | YTD9 2022 |
| BAT | 10.0% | H1 2022 |
| JT | 3.4% | YTD9 2022 |
| Imperial | 2.5% | FY2022 |
| Altria | 2.2% | YTD9 2022* |
Our take-away
Trading at 7.8x adj. EPS and 6.9x adj. EV/EBITDA. Dividend yield: 6.9%.
Imperial is a “deep value” stock based on cheap valuation metrics and rich dividend yield. However, the long-term business sustainability is a major question mark as
– the (Imperial’s) top markets are reaching a tipping point in terms of transformation from combustibles to NGP/RRPs
– the camps are being formed in the industry to weather the transformation (PMI & Swedish Match, Altria & Japan Tobacco, BAT/Reynolds) and Imperial is left out as a small player.

