


Top-line & Bottom-line results
Adjusted, at constant currencies
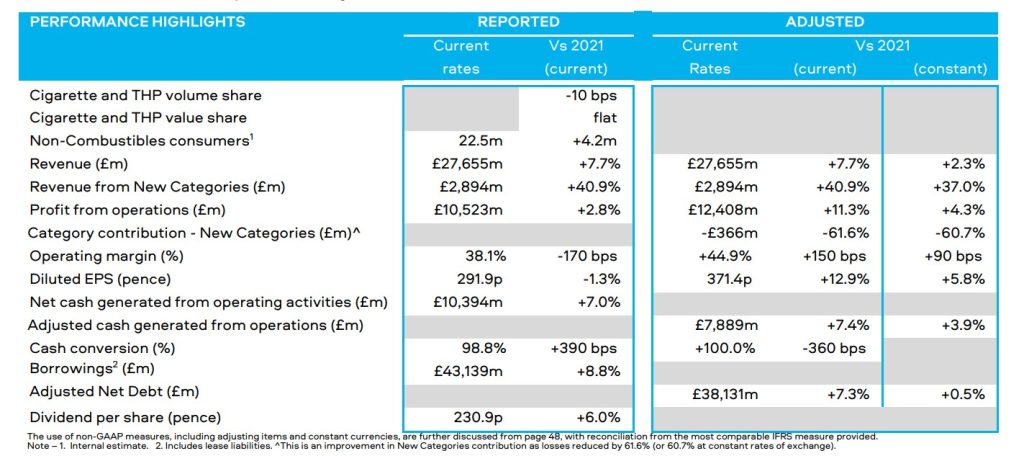
Net revenue up +2.3% (New Category net revenue up +37%)
Operating profit up +4.3%; operating margin +90 bps
EPS up +5.8%
Key Highlights
New Categories (NC):
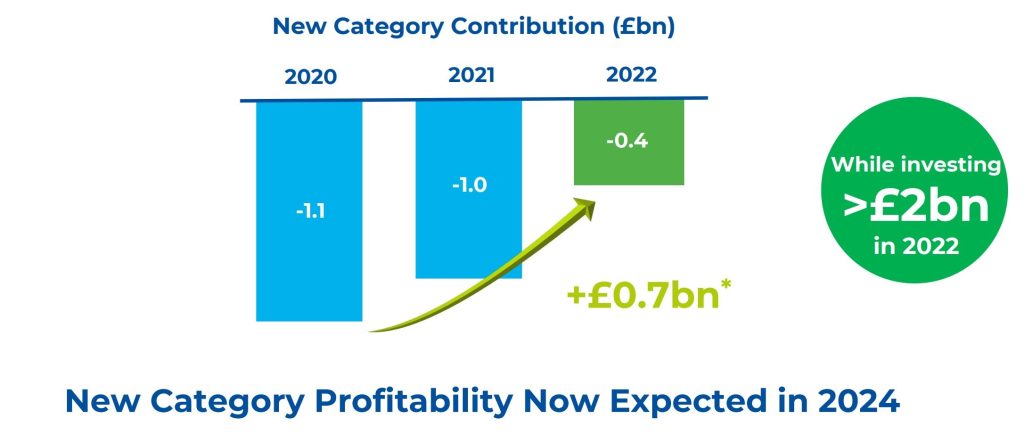
– BAT now expects NC profitability in 2024, one year ahead of plan
– NC revenue: +37% (vapor +44%; heated tobacco +27%; modern oral +46%)
– Weight of NC revenue in total: 14.8% (+2.4pps)
– NC losses reduced by 60.7% to £366Mn in 2022
– Number of non-combustible consumers: +4.2Mn to 22.5Mn
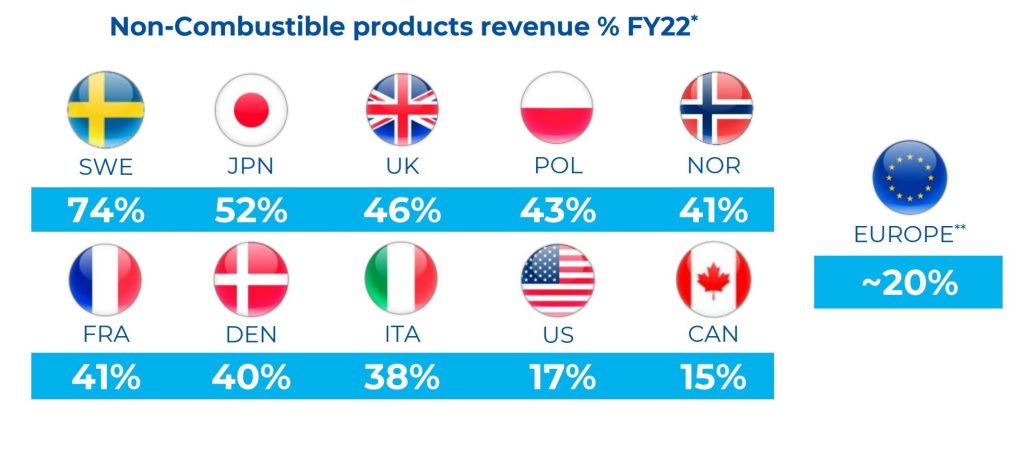
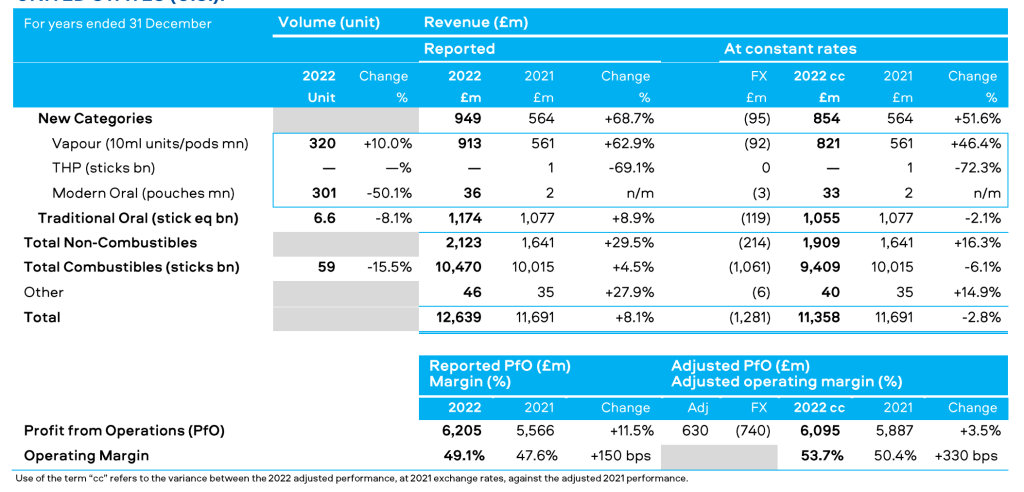
The US Market: (52.4% of total operating profit)
– Combustibles: volume -15.5%; revenue -6.1%
– Operating profit: +3.5% on the back of +330bps margin expansion to 53.7%
– Very poor combustible performance, partially offset by the strong performance of Vuse (volume +10%, revenue +46%)
2023 Guidance
– Global tobacco industry volume: -2%
– Revenue growth: 3-5% (reported growth to be impacted by the transfer of Russia business)
– Adjusted EPS growth: mid-single digit (2% FX headwind, growth to be second half weighted)
– Operating cash flow conversion: above 90%
Our take-away
Trading at 8.3x adj. EPS and 8.7x adj. EV/EBITDA. Dividend yield: 7.5% (based on Feb 8, 2022 closing price: £30.91)
The situation in the key US combustible market is dire: 6.1% revenue and 15.5% volume decline. The progress in NPGs is noteworthy, but it is not easy to prosper financially when half of the business (by operating profit) is not doing well. Nevertheless, we maintain our long-term cautious optimism on BAT.
Our conclusion: More pain ahead before a Better Tomorrow

