


Top-line & Bottom-line results
Adjusted, at constant currencies; Tobacco only – excluding Pharmaceuticals & Processed Food
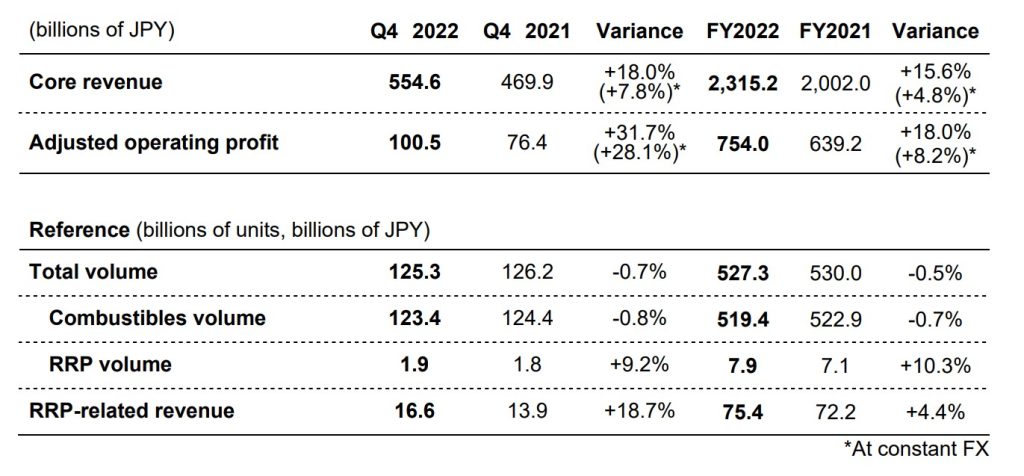
Core revenue: up +4.8% (RRP revenue: up +4.4%)
Operating profit: up +8.2%
Total volume: down -0.5% (combustibles: -0.7%, RRP +10.3%)
Key Highlights
– Re-defines its corporate purpose as: “Creating fulfilling moments. Creating a better future”
– New Strategy: Prioritize Heat-not-Burn (instead of an equal-weighted multi-category approach)
– Accelerate Ploom X roll-out: Deployment in more than 20 markets in the next 2 years
– SoM in Japan: 60.4% in Combustibles vs. 8.2% in Heated tobacco (8 years after first IQOS launch). Heated tobacco now accounts for 34% of the the market
FY23 Guidance:
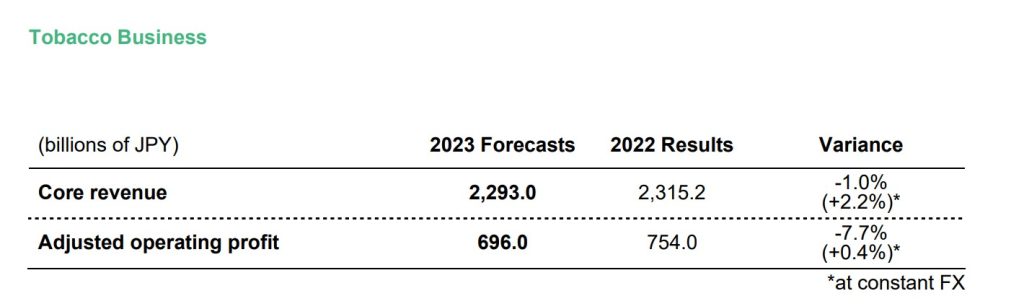
– Revenue: +2.2%
– Operating profit: +0.4%
– Dividend: unchanged at ¥188/share (payout ratio of ~75%)
Mid-/long-term targets re-confirmed:
– mid-to-high single digit operating profit growth
– dividend growth in line with the payout ratio of 75%
– 2028 ambition to reach break-even in RRPs, by achieving a HnB segment share in the mid-teens across the key markets
Our take-away
Trading at 10.7x adj. EPS and 6.5x adj. EV/EBITDA. Dividend yield: 7%.
Japan Tobacco is clearly a laggard in transformation to RRPs (i.e.1.5% weight in volume; 3.3% weight in revenue). Moreover, JT’s RRP growth rate is substantially lower than that of PMI and BAT; major RRP-related investments are yet to hit the JT’s financials. All in all, JT is having hard time delivering its mid-/long-term growth targets (as per the 2023 Guidance). However, in the “League of Laggards: Altria, Imperial, JT”, we still favor JT due its size/scale, higher emerging market exposure and very low indebtedness (net debt: <$1Bn).

