


Bottom-line results & Volume progression1
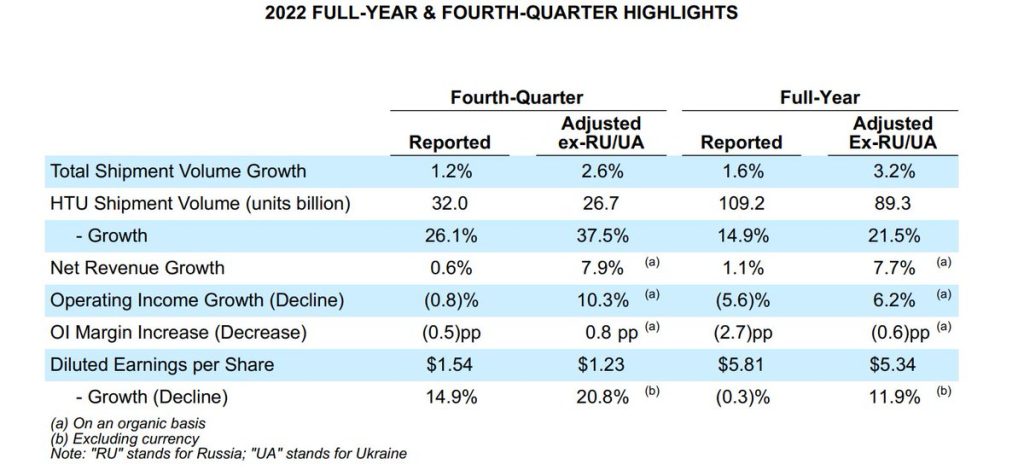
EPS: up +20.8% to $1.23 in Q4; up +11.9% to $5.34 in FY22
Total volume: +2.6% in Q4; 3.2% in FY22 (HnB volume: +37.5% in Q4; +21.5% in FY22)
Adjusted figures: excluding Russia & Ukraine
Operating Income: margin pressures
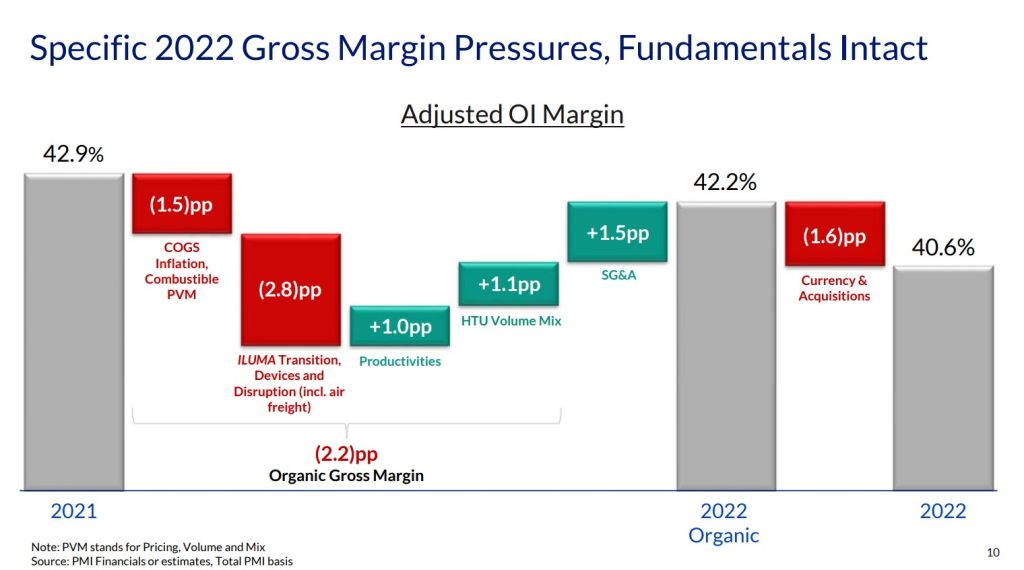
FY22: 0.6% decline on an organic basis
– inflationary cost pressures (notably related to leaf, acetate tow and energy prices); transitory cost impact associated with the ILUMA roll-out; costs due to supply chain disruptions related to the war in Ukraine
– partly offset by the favorable product mix, pricing and operating efficiencies
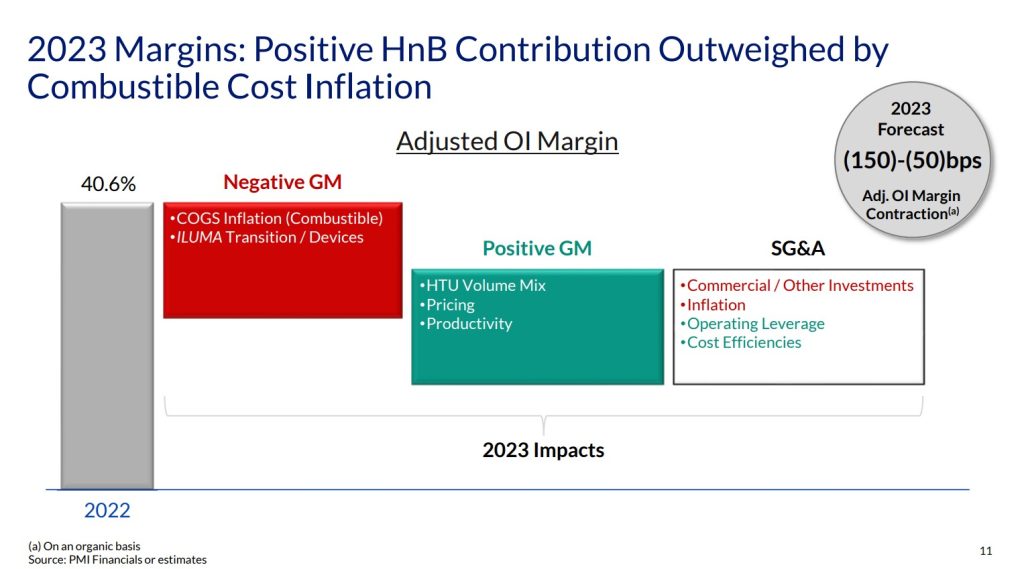
FY23: 0.5%-1.5% decline
– continued inflationary cost pressures and ILUMA roll-out associated transitory costs
– incremental investments to drive future growth: ~$150Mn with a broadly even split between the US and Wellness & Healthcare segments
FY23 Guidance
Russia & Ukraine to be included in 2023 figures (PMI Assets: $2.5Bn in Russia, $0.4Bn in Ukraine)
Revenue growth: +7%-8.5% (organic)
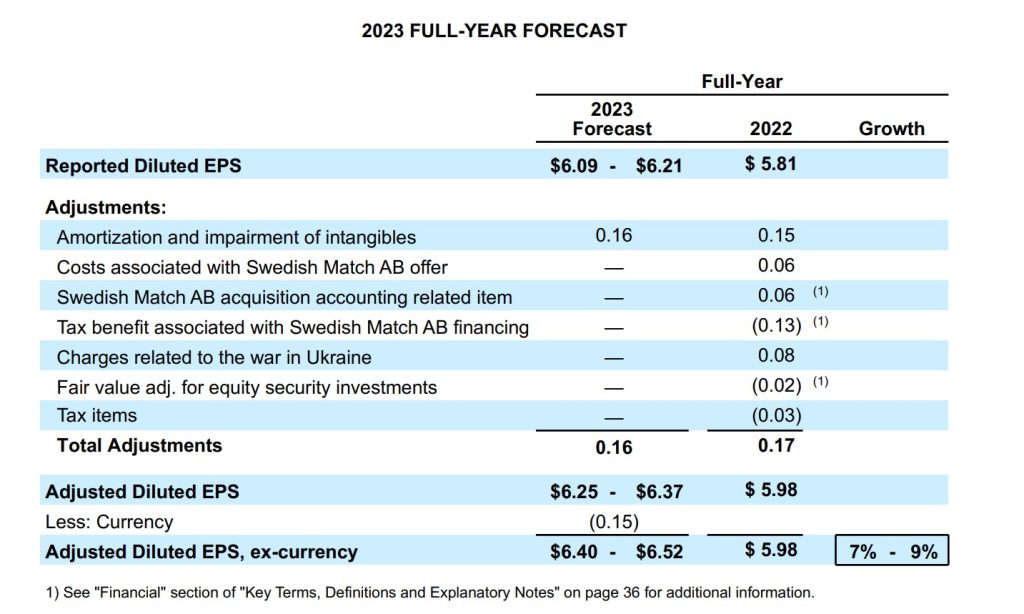
EPS growth: +7%-9% to $6.40-$6.52, despite inflationary pressures and ILUMA deployment expenses (top and bottom-line delivery to be second-half weighted; Q1 EPS: $1.28-1.33)
Total PMI volume: flat to +1%, despite 1-2% industry volume decline (ex-China&US)
HnB shipment volume: 125-130Bn (acceleration in growth vs. 2022); Q1 HnB volume: 26-28Bn
Adj. operating margin: 0.5%-1.5% decline
Wellness & Healthcare revenues of $300Mn with an operating loss of $150Mn
Operating cash flow: $10-11 Bn (no share repurchases due to the Swedish Match acquisition)
Our take-away
Trading at 16.9x adj. EPS and 14.3x adj. EV/EBITDA. Dividend yield: 5% (based on Feb 8, 2023 closing price: $101.3)
Top-class management, execution & results vis-a-vis the industry peers. However, the operating margin and EPS guidance are a touch softer than expected (inflationary pressures, ILUMA expansion expenses and “future growth” investments). 21.5% HnB volume growth (37.5% in Q4) is noteworthy. Zyn & IQOS are the current/future growth engines in the US. We continue to like PM which is on the way to a new all-time high (ATH). The timing of the new ATH could coincide with the IQOS launch in the US. Meanwhile, any pullback is a buying opportunity.
References:

