


Q3 2023 Results1
Despite reporting its highest-ever quarterly revenue (₩1.69Tn; +4% year-on-year) in Q3 2023, KT&G’s operating profit increased only marginally (+0.4% to ₩406.7Bn) due to persistent cost headwinds.
Results: Tobacco Division

Key announcement highlights (for the tobacco business only):
– Revenue +3% to ₩972.7Bn; Operating Profit +0.6% to ₩269.4Bn => Margin down 28.4% to 27.7%
– International (ex-Korea) revenue: now 57.9% of the total (+4.9pp)
– Conventional – Korea: -2.1% volume decline despite SoM growth (to 66.8%) due to strong market contraction (-4.4%)
– Conventional – International: +12.5% volume growth coupled with price/regional mix improvements leading to +38.8% year-on-year revenue growth. Indonesian quarterly volume: 2.7Bn sticks
Results: NGP Segment
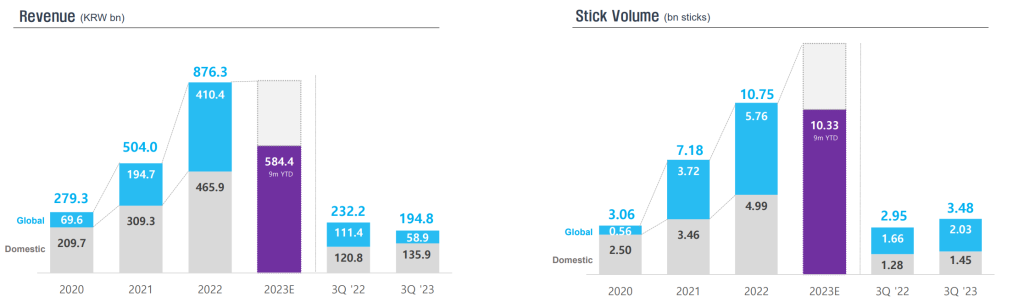
– NGP – Korea: Leadership is maintained, but SoS is down to 45.9% due to fiercer competition with more aggressive promotions and new device launches from competitors (e.g. IQOS ILUMA). Volume is up +13% to 1.45Bn sticks; revenue is up +12.5%.
– NGP – International (Global Partnership with PMI): Revenue is down -47%) due to the excessive amount of devices shipped last year and despite 22% growth in stick volume.
– Overall NGP volume: 10.33Bn in YTD2023.
With 14Bn (estimated) annual volume (12.5% weight in overall volume), KT&G owns the third largest heated tobacco franchise in the Industry (after PMI & BAT).
Q1 2023 Results
For the tobacco business only, excluding KGC (Korea Ginseng Corporation) and Real Estate segments:
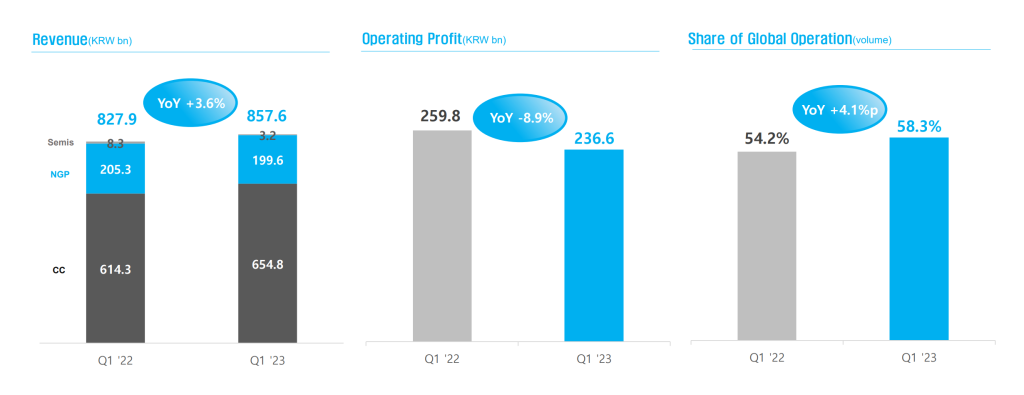
– Total Revenue: up +3.6% to ₩857.6Bn ($673Mn); lifted by the international combustible revenue growth (+17%)
– Share of NGP: 23.3% (down -1.5pp)
– Share of international (ex-Korea): 58.3% (+4.1pp)
– International combustible business: volume up +16% to 13.4Bn stick (half the growth from Indonesia alone)
– Operating Profit: down -8.9% to ₩236.6Bn ($185.6Mn); mainly, due to the COGS inflation
NGP Update
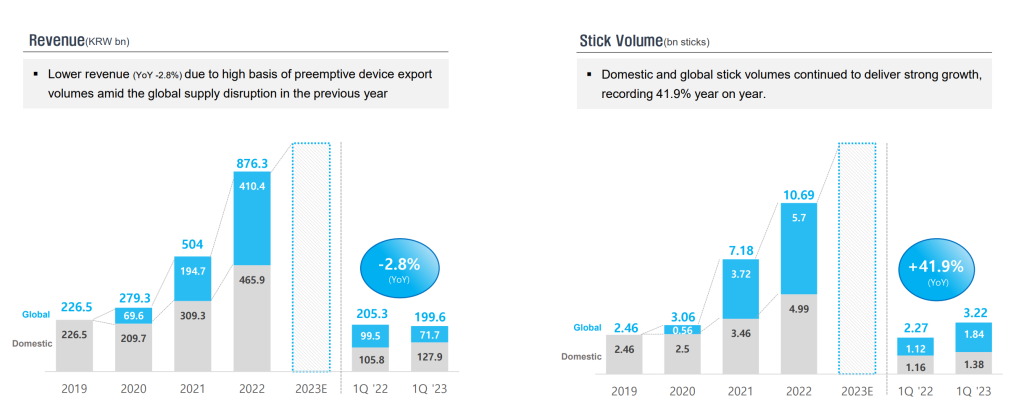
– Revenue: -2.8%; due to preemptive device export volumes amid the global supply disruption in Q1 2022
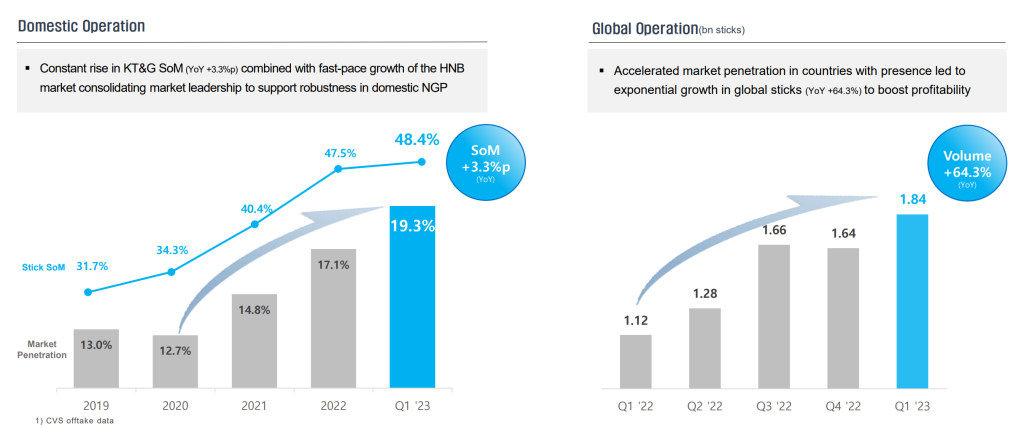
– Volume: +41.9% (international: +64.3%; domestic: +19%)
– Domestic SoS: 48.4% (maintains its market leadership ahead of PMI & IQOS.)
– Domestic NGP penetration: 19.3% (weight in total tobacco/nicotine market)
Recall: In Jan 2023, PMI and KT&G announced the agreement to extend and deepen collaboration for an additional 15-year period as PMI retains the long-term exclusive rights to commercialize KT&G’s innovative smoke-free products outside South Korea.
References:

