


Key Business Metrics1
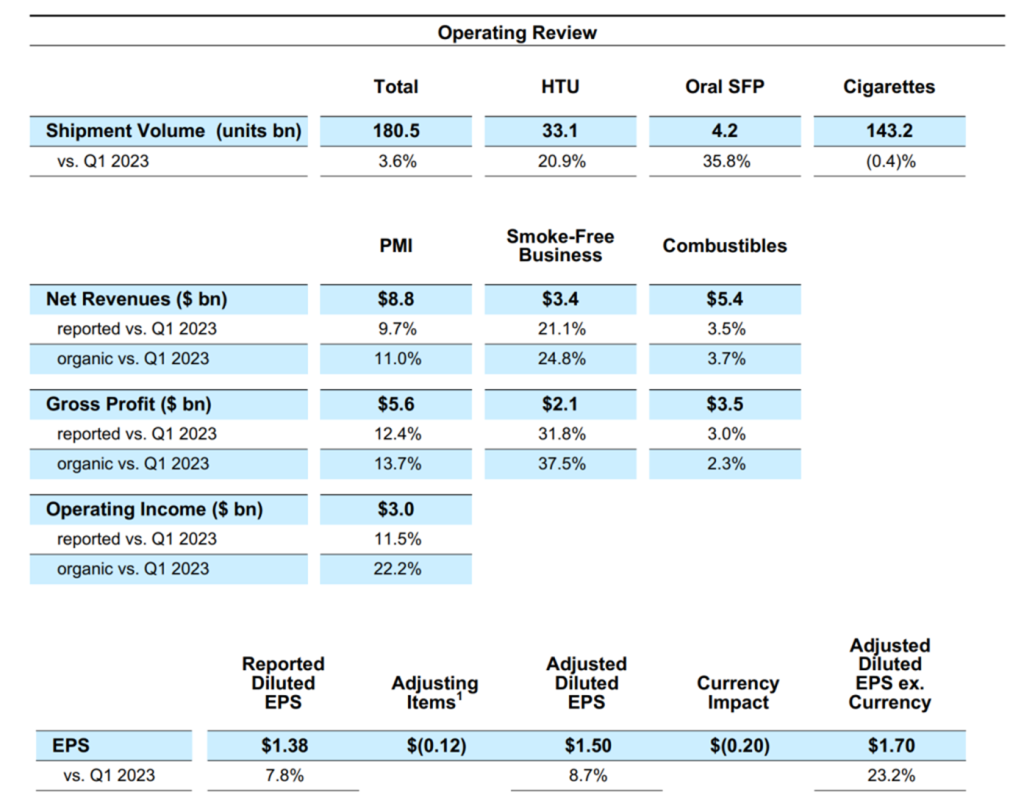
Adjusted net revenue: up +8.6% to $8.79Bn (vs. $8.47Bn expected; +11% ex-FX)
Adjusted diluted EPS: up +8.7% to $1.50 (vs. $1.41 expected; +23.2% ex-FX)
Adjusted operating income margin: 38.2% (up+0.9pp vs. Q1 2023; +3.7pp ex-FX; deceleration in SG&A growth)
Total volume: up +3.6% to 180.5Bn (HnB volume: +20.9% to 33.1Bn; oral nicotine volume: +35.8% to 4.2Bn; cigarette volume: -0.4% to 143.2Bn)
Smoke-free weight: 39% by revenue; 20.7% by volume
Key Highlights
– Combustibles: Net revenues grew by +3.5% (organically by +3.7%), fueled by strong pricing across markets. Category share increased by 0.3pp with Marlboro gaining 0.4pp
– Heated Tobacco (HTP): IQOS as the second largest nicotine brand in markets where present, including the #1 position in 11 markets. HTP adjusted in-market sales (IMS) volume (ex-inventory movements) is up by +12.5%. In Europe, IQOS HTP market share exceeded 10% for the first time with adjusted IMS growth of 9.4% (influenced by the impact from the EU characterizing flavor ban). In Japan, IQOS HTP market share increased by more than 3pp to over 29%, with adjusted IMS growth of 13.3%.
Our read: Q1 IMS growth (+12.5%) is below the “+14% to +16%” range guided. Moreover, the shipment growth (+20.9%) is above the IMS growth which implies an inventory build-up in the markets. PMI explains the situation as: “a net favorable impact of distributor inventory movements for HTP was driven most significantly by additional shipments to Japan in light of disruption to Red Sea shipping routes”. It seems like PMI is not ready [yet] to accept the heated tobacco growth slow-down and lower the FY24 guidance.
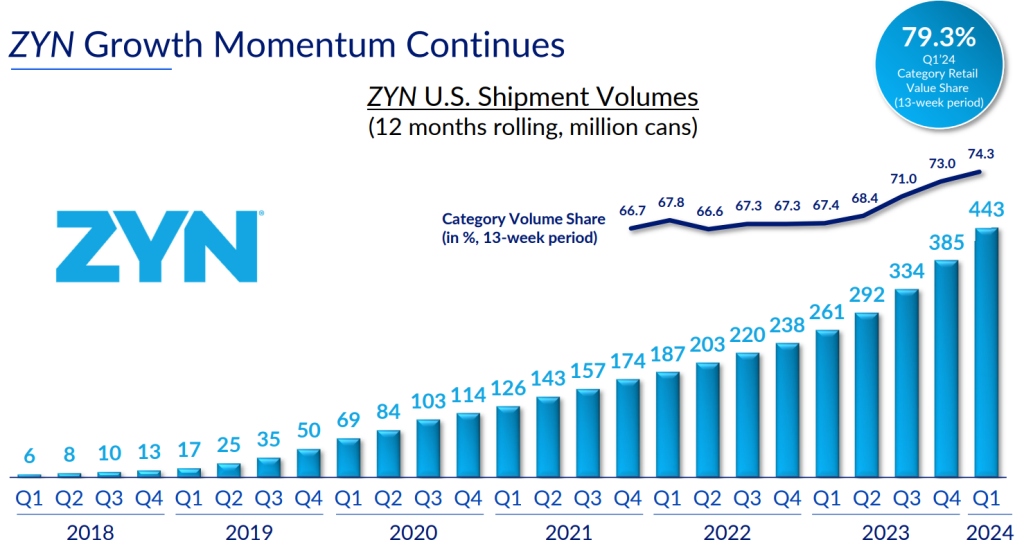
– Oral Tobacco: Shipment volume increased by 40.0% in cans (35.8% in pouches), fueled by ZYN nicotine pouch growth in the US – where shipment volume reached 131.6Mn cans (up +79.7% versus prior year). PMI’s category share in the US increased by +1.3pp sequentially to over 74%.
FY24 Guidance
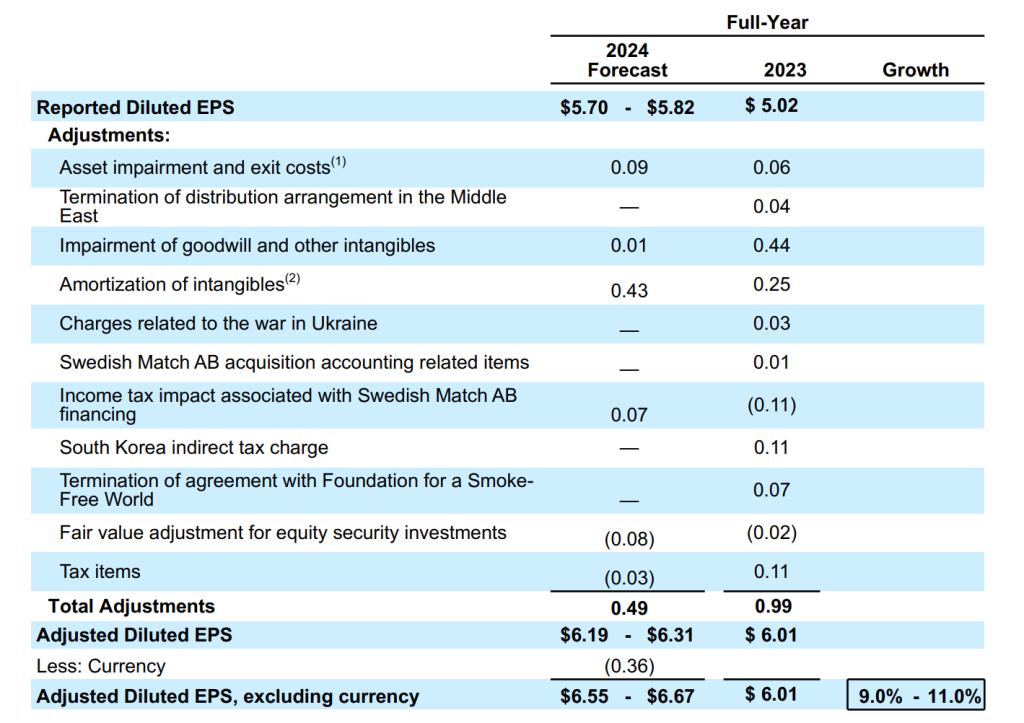
– Reported EPS: in a range of $5.70 to $5.82, vs. $5.02 in FY23 (lowered from $5.90 – $6.02)
– Adjusted EPS: in a range of $6.19 to $6.31, vs. $6.01 in FY23 (one-of adjustments of $0.49 vs. $0.42 previously projected)
– Adjusted EPS, ex-FX: in a range of $6.55 to $6.67, representing a growth of 9.0% to 11.0% vs. $6.01 in FY23 (FX adjustments of $0.36 vs. $0.11 previously projected)
– Q1 2024 unfavorable currency variance: $0.20 (vs. $0.10 previously projected), including a $0.09 impact from the devaluation of the Egyptian pound (EGP) and a transactional impact of $0.06 primarily related to the balance sheet re-measurement of foreign currency payable.
FY24 Assumptions
– International (ex-China & US) industry volume decline for cigarettes & HTPs: -2% to flat
– PMI volume (including oral nicotine): flat to +1%
– HTP volume: more than 140Bn sticks (re-confirmed)
– HTP IMS growth: 14% to 16% (including 2Bn sticks adverse impact from consumer adjustment to the EU characterizing flavor ban)
– ZYN shipment volume in the US: 560Mn cans (increased by +40Mn cans)
– Net organic revenue growth: 7% to 8.5% (increased from “6.5% to 8%”)
– Organic operating income growth: 10% to 12% (increased from “8% to 9.5%”)
– An acceleration in organic smoke-free net revenue and gross profit growth compared to FY23
– Broadly unchanged net revenue (~$300Mn) and adjusted operating loss (~$150Mn) in Wellness & Healthcare segment
– Net financing costs: $1.3 to $1.4Bn (unchanged)
– Operating cash flow: $10 to $11Bn; CAPEX: $1.2Bn, partly reflecting investments in ZYN capacity in the US (unchanged)
– Net debt to EBITDA ratio improvement of 0.3x to 0.5x in pursuit of a ratio of ~2x by the end of 2026 (unchanged)
– Q2 2024 EPS: $1.50 to $1.55, including an estimated adverse FX impact of 14 cents
Other Highlights
– New Segment Structure: PMI updates its segment reporting to include Swedish Match results in the four existing geographical regions (instead of a separate entity). PMI’s Q1 2024 results reflect the new segment structure.
– PMI restructured the sourcing of IQOS products for the US (following the global patent settlement with BAT) and recorded an impairment & exit cost of $121Mn related to this restructuring
– PMI ceased its operations in Venezuela and as a result, recorded an impairment & exit cost of $47Mn
Summary
As always, PMI’s financials are great when adjusted for the currency. Although the FY24 EPS growth guidance (adjusted, ex-FX) is revised up from +7%-9% to +9%-11%, both the reported EPS and adjusted EPS guidance were revised down. The US$ reporting (strength) is not simply a translational issue for PMI: it is both structural and transactional. And the bottom-line is: investors pay US$ to buy PMI shares and want to see the PMI’s figures grow in US$.

Nevertheless, net revenue growth (+8.6%) summarizes PMI’s strong operational performance: organic volume growth (+3.6pp) coupled with strong pricing (+5.5pp) and favorable product mix (+3.1pp; shift to smoke-free products with higher net unit revenue), partially held back by the geographical mix (-1.2pp; shift of volume to emerging markets) and unfavorable FX (-2.4pp).
There are more hints of heated tobacco growth slow-down even if PMI is not yet ready to revise its growth metrics. Moreover, Market could continue to offer PMI the benefit of doubt (i.e. a circumstantial slow-down rather than a structural one). ZYN rocks! Unless brought down by the regulatory and legislative actions, ZYN could compensate for the deteriorating performance of IQOS.
Further Readings:
PMI – Q1 2024 Results: Preview
PMI – 2023 Investor Day: Preview
References:

