


October 2025: Q3 2025 Results1
Smoore’s quarterly revenue increased +27.2% year-on-year (+27.5% sequentially) to ¥4,196.8 million in Q3 2025 – setting a new record high for Smoore. Both corporate client segment (heated tobacco & vapes) and own brand segment contributed to the revenue growth:
– Heated tobacco products: Launch of new heat-not-burn products by strategic client(s) in more markets resulted in a significant increase in product shipments in Q3 2025
– Vaping products: Major countries around the world continued to strengthen the regulation against the non-compliant products. Smoore supported more clients in launching new, compliant products, contributing to sustained revenue growth
– Own-brand: Launch of new flagship products in H1 2025 expanded the consumer base. Smoore continued to strengthen local operations, increase marketing investment tailored to local market characteristics and drive growth in brand market share & revenue.

Smoore’s adjusted profit, excluding share-based payment expenses, increased +4% year-on-year basis (+4.8% sequentially) to ¥444.2 million.
September 2025: U.S. FDA accepts Smoore’s application for the generic equivalent of Breo Ellipta
Transpire Bio, a wholly-owned subsidiary of Smoore International, announced that its Abbreviated New Drug Application (ANDA) for the generic equivalent of Breo Ellipta has been submitted and officially accepted by the U.S. Food and Drug Administration (FDA). If approved, Transpire Bio will benefit from an exclusive market period of 180 days in the United States. Breo Ellipta is used for maintenance treatment of asthma and chronic obstructive pulmonary disease (COPD) in the U.S. and recorded a sales of US$2 billion in 2024. Smoore International aims to deepen its expertise in both medical and electronic vaporization ecosystems, driving continuous technological and application breakthroughs in inhalation formulation and complex generic drug delivery.
August 2025: H1 2025 Results2
– Revenue: up +18.3% to ¥6,013 million; recovery of the vaping business driven by more effective legal
enforcement against non-compliant products in major global markets and the launch of new innovative products
– Selling & distribution expenses: up +31.2% to ¥491 million (“2025 as an investment year”); Profit: down -28% to ¥492 million (down -2.1% if adjusted for non-cash share-based payment expenses)
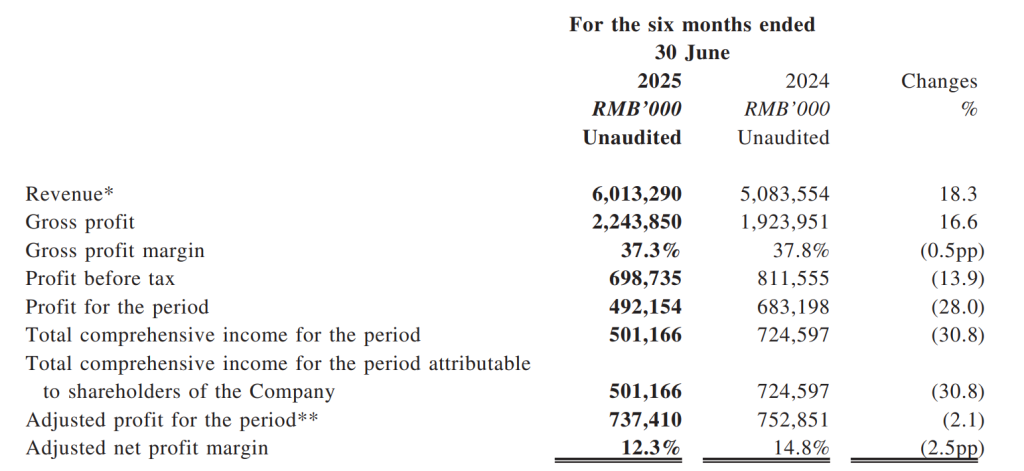
– B2B segment: Revenue up +19.5% to ¥4,739 million (Europe +38%, U.S. +1.5%, China -6.1%); Strengthened enforcement against noncompliant products supports Smoore’s business; Established an R&D center and local sales teams in the U.S.
– Own brand segment (mainly, the VAPORESSO brand): Revenue up +14.1% to ¥1,274 million; expanded channel coverage and enhanced localized operations, resulting in continued market share growth in key region
– Supported BAT in glo HILO launch: collaborated to develop the product, demonstrating superior performance in tobacco-like flavor and reduced preheating time
July 2025: Smoore issues a profit warning for H1 2025
Benefiting from the improved competitiveness of the product portfolio in major global markets, Smoore continued to deliver revenue growth in both own brand business and corporate client business. In H1 2025, Smoore recorded a revenue increase of ~18%, which also resulted in a corresponding increase in gross profit. However, the growth in revenue and gross profit only partially offset the increased expenses during the period. The Group’s profit for the period is expected to be RMB 442.9 million to RMB 541.4 million, representing a decrease of 21% to 35% compared to the same period last year. The main reasons for the decline are listed as:
(1) The accounting impact from the granting of share options and restricted shares under the post-IPO share option scheme and share award scheme in Q4 2024. During the review period, the Group recorded a year-on-year increase of RMB 175.6 million in non-cash share-based payment expenses;
(2) The Group further strengthened its marketing efforts for its self-owned brand products during the period, especially in expanding into overseas markets, resulting in a significant year-on-year increase in distribution and selling expenses;
(3) The Group’s legal service-related expenses also recorded a significant increase compared to the same period last year.
If the non-cash share-based payment expenses are added back, the Group’s adjusted profit for the period is expected to be RMB 688.2 million to RMB 786.7 million, representing a decrease of ~9% to an increase of ~4% compared to the same period last year. Interim H1 2025 results will be published in August 2025.
| (in RMB million) | H1 2025 | H1 2024 | Change (%) |
|---|---|---|---|
| Revenue | 6,013.3 | 5,083.6 | +18% |
| Profit before tax | 628.9 ~ 768.6 | 811.6 | –5% to –23% |
| Profit | 442.9 ~ 541.4 | 683.2 | –21% to –35% |
| Total comprehensive income | 451.0 ~ 551.3 | 724.6 | –24% to –38% |
| Add: Share-based payment expenses | 245.3 | 69.7 | +252% |
| Adjusted profit | 688.2 ~ 786.7 | 752.9 | –9% to +4% |
August 2024: H1 2024 Results3
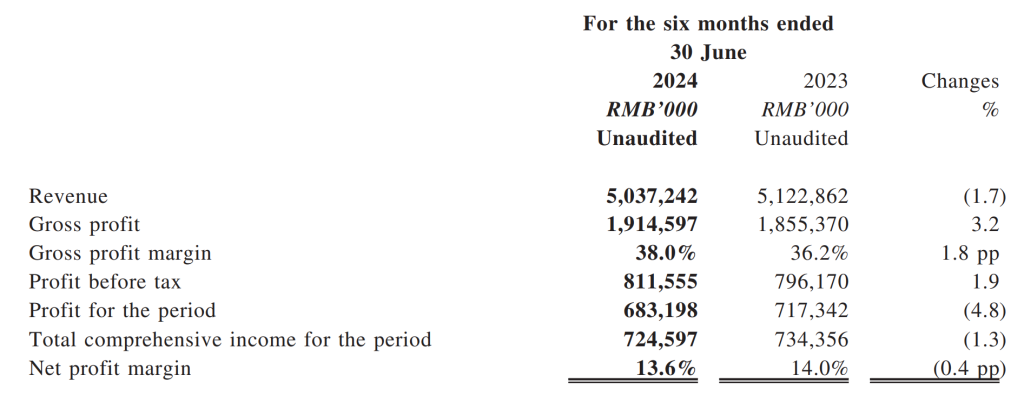
– Revenue: ¥5.04 billion (down -1.7%)
– Gross profit: ¥1.915 billion (up +3.2%; margin expansion from 36.2% to 38%)
– Gross profit margin improvement is mainly attributable to the significant growth in the branded business (higher gross profit margin), cost-efficiency improvements and favorable product mix
– Net profit: ¥0.725 billion (down -1.3%; margin decline from 14% to 13.6%)
– Branded business: Revenue is up +71.9% to ¥1.12 billion. Share in total group revenue is up +9.4pp to 22.1%. Stepped up international market development efforts mainly through digital marketing. VAPORESSO has continued to increase SoM in the open-system segment to become the leading brand in this category.
– Corporate clients: Revenue is down -12.3% to ¥3.92 billion. Share in total group revenue is down to 77.9%. Revenue from the key US market is down -9.8% to ¥1.86 billion (i.e. 36.9% of the total) due to the illicit disposable vapes. Revenue from Europe (& others markets) is down -16% to ¥1.98 billion (i.e. 39.3% of the total) due to reduced demand for disposable vapes as a result of the shifting regulatory landscape (i.e. upcoming disposable vape bans). Revenue from China is up +41.4% to ¥0.88 billion (i.e. 1.7% of the total).
– Sequential improvement in quarterly corporate client revenue (from Q1 2024 to Q2 2024) as a result of improving regulatory enforcement (towards illicit disposable vapes) in the US and strong growth in pod-based products (replacing disposable vapes) in Europe => indication of further revenue recovery in H2 2024.

– Product & Process Development: Improved the level of manufacturing automation optimized the cost structure for BAT’s VUSE product. Launched a number of new closed-system products in the international market to capture the demand shifting from disposable vapes. Established a close cooperation with strategic customers for product and technological service provision in the heat-not-burn category.
– R&D expenses increased by +23.7% to ¥0.76 billion (corresponding to 15.1% of the total group revenue). The increase is driven by the investment in the fields of inhalation therapy and heat-not-burn products.
References:
- https://staticpacific.blob.core.windows.net/press-releases-attachments./3928340/HKEX-EPS_20251012_11876725_0.PDF ↩︎
- https://staticpacific.blob.core.windows.net/press-releases-attachments./3911625/HKEX-EPS_20250820_11803414_0.PDF ↩︎
- https://staticpacific.blob.core.windows.net/press-releases-attachments/2912260/HKEX-EPS_20240819_11329053_0.PDF ↩︎

