


Key Business Metrics1
Adjusted net revenue: up +5.6% to $9.47Bn (vs. $9.18Bn expected; $8.97Bn in Q2 2023)
Adjusted diluted EPS: down -0.6% to $1.59 (vs. $1.57 expected; $1.60 in Q2 2023)
Adjusted operating income margin: 38.6% (down -0.8pp vs. Q2 2023; +1.1pp ex-FX)
Total volume: up +2.8% to 197.3Bn (heated tobacco volume: +13.1% to 35.5Bn; oral nicotine volume: +20% to 4.2Bn; cigarette volume: +0.4% to 157.6Bn)

Smoke-free weight: 38.1% by revenue (vs. 39% in Q1 2024); 20.1% by volume (vs. 20.7% in Q1 2024)
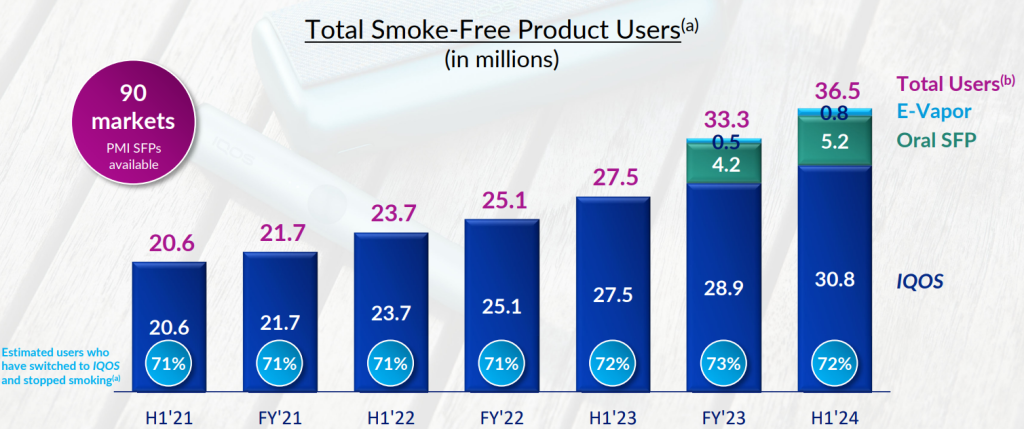
Smoke-free business (SFB): 36.5 million users (up by +3.2 million versus December 2023) in 90 markets. SFB net revenues up by +13.6% (+18.3% on an organic basis) and gross profit up by +15.6% (22.2% on an organic basis)
Key Highlights
– Combustibles: Net revenues up by +1.2% (+4.8% on an organic basis), driven by high single-digit pricing and resilient volume (+0.4%). After seven consecutive quarters of gross margin contraction, profitability recovered in Q2 2024 with an expansion of +40 bps (+50 bps on an organic basis), primarily driven by pricing.
– Heated tobacco (HTP): Total IQOS users at quarter-end were estimated at 30.8 million (up by +1.9 million versus December 2023), including 22.1 million exclusive IQOS users. The increase was broad-based: notable progress in Japan (following the launch of ILUMA i), Europe (especially in Greece, Hungary, Romania, Bulgaria, and Spain), South Korea, and low & middle income markets (especially in Indonesia).
Market share for heated tobacco units (HTU) in IQOS markets was up by +0.7pp to 8.1%. HTU adjusted in-market sales volume was up by +10.2%.
– In Japan, adjusted IMS grew by +12.5% (the 7th consecutive quarter of double-digit growth) and IQOS HTU market share increased by more than +3pp to over 29%. HTU off-take share exceeded 30% for the first time in June 2024. TEREA and SENTIA were the #1 and #3 nicotine brands respectively in the quarter.
– In Europe, IQOS HTU adjusted market share increased by +0.8pp to 9.8% with adjusted IMS growth of +6.8%, which was impacted by the EU characterizing flavor ban, especially in Italy.
– E-vapor: VEEV has taken the #1 position in the closed pod segment in 5 European markets within 12 months of launch. Already 0.8 million e-vapor users.
– Oral Tobacco: Shipment volume increased by +23.5% in cans (+20.0% in pouches), fueled by ZYN nicotine pouch growth in the US, where shipments reached 135.1 million cans, representing growth of +50.3% versus prior year. ZYN, despite supply constraints, performed in-line with the US nicotine pouch category in terms of consumer off-take. PMI targets to achieve 900 million cans product capacity volume in the US in 2025. Outside of the US, nicotine pouch volume grew by over +50% with promising results in a number of new markets, notably Pakistan.
FY24 Guidance
– Reported EPS: in a range of $5.89 to $6.01, vs. $5.02 in FY23 (increased by $0.19)
– Adjusted EPS: in a range of $6.33 to $6.45, vs. $6.01 in FY23 (increased by $0.14; one-of adjustments of $0.44 vs. $0.49 previously projected)
– Adjusted EPS, ex-FX: in a range of $6.67 to $6.79, representing a growth of 11% to 13% vs. $6.01 in FY23 (increased by $0.12; FX adjustments of $0.34 vs. $0.36 previously projected)

FY24 Assumptions
– International (ex-China & US) industry volume decline for cigarettes & HTPs: broadly stable (before: -2% to flat)
– PMI volume (including oral nicotine): +1% to +2% (before: flat to +1%)
– HTP volume: around 140Bn sticks (before: more than 140Bn)
– HTP IMS growth: +13% (before: +14% to +16%, including a slightly more adverse impact from consumer adjustment to the EU characterizing flavor ban)
– ZYN shipment volume in the US: 560-580Mn cans (before: 560Mn cans)
– Net organic revenue growth: 7% to 9% (before: 7% to 8.5%)
– Organic operating income growth: 11% to 13% (before: 10% to 12%)
– An acceleration in organic smoke-free net revenue and gross profit growth compared to FY23
– Broadly unchanged net revenue (~$300Mn) and adjusted operating loss (~$150Mn) in Wellness & Healthcare segment
– Net financing costs: $1.3Bn (before $1.3Bn to $1.4Bn)
– Operating cash flow: $11Bn (before $10Bn to $11Bn); CAPEX: $1.3Bn-$1.4Bn (before $1.2Bn, partly reflecting investments in ZYN capacity in the US)
– Net debt to EBITDA ratio improvement of 0.3x to 0.5x in pursuit of a ratio of ~2x by the end of 2026 (unchanged)
– Q3 2024 EPS: $1.77 to $1.82 (record-high quarterly EPS), including an estimated adverse FX impact of 2 cents
Summary
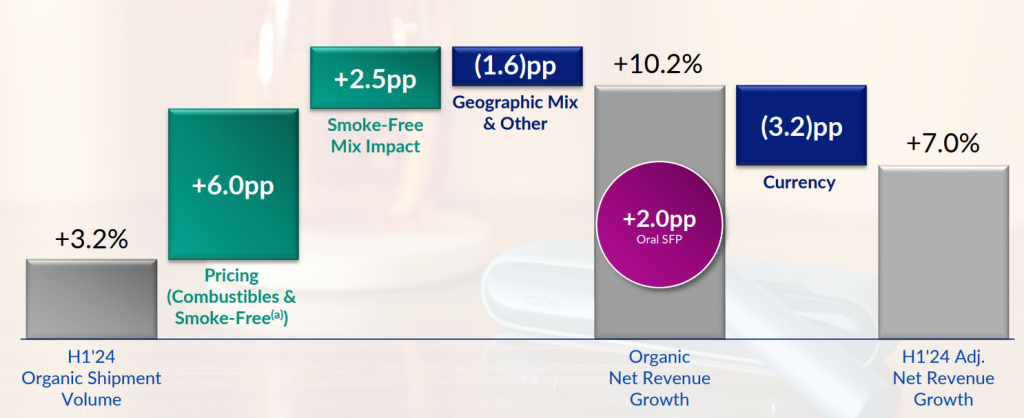
As in Q1 2024, PMI’s financial delivery remained very strong in Q2 2024. Overall, net revenue growth of +7.0% in H1 2024 validates PMI’s industry-leading operational performance: organic volume growth (+3.2pp) coupled with strong pricing (+6.0pp) and favorable product mix (+2.5pp; shift to smoke-free products with higher net unit revenue), partially held back by the geographical mix (-1.6pp; shift of volume to emerging markets) and unfavorable FX (-3.2pp).
However, PMI eventually admitted the slowdown in heated tobacco growth and revised down its growth metrics (from 14%-16% to 13%). This slowdown, coupled with the retail stock-outs faced by ZYN in the US, resulted in a deterioration of momentum in transition to smoke-free.
The key question is: PMI’s results are very strong; but, are they strong enough to push PMI share price above the key $110 level and towards a new ATH ($123)? Market would definitely prefer that PMI’s exceptional Q2 2024 results were delivered based on a weaker combustible performance and a stronger smoke-free performance in terms of product mix. The current mix offers the “smoke-free transformation slowing down” camp a chance to develop arguments in an attempt to reverse the current price momentum (note that the smoke-free’s weight in PMI’s volume and revenue in Q2 2024 declined vs. Q1 2024).
Further Readings:
References:

