


Top-line & Bottom-line Results1
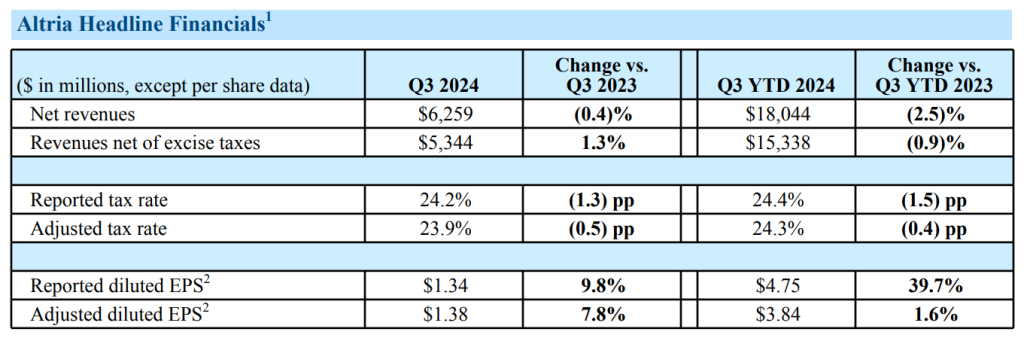
Q3 2024 Revenue: $5.33Bn (exp. $5.33Bn; up +1.3% from $5.28Bn in Q3 2023)
Q3 2024 EPS: $1.38 (exp. $1.35; up +7.8% vs. $1.28 in Q3 2023)
Commentary: Solid operating profit growth behind the resilience of Marlboro and MST brands. Maintained growth momentum by on!
FY24 Guidance:
Re-confirmed. Adjusted diluted EPS in a range of $5.07 to $5.15, representing a growth rate of 2.5% to 4.0% from a base of $4.95 in 2023
Business Segments: Smokable
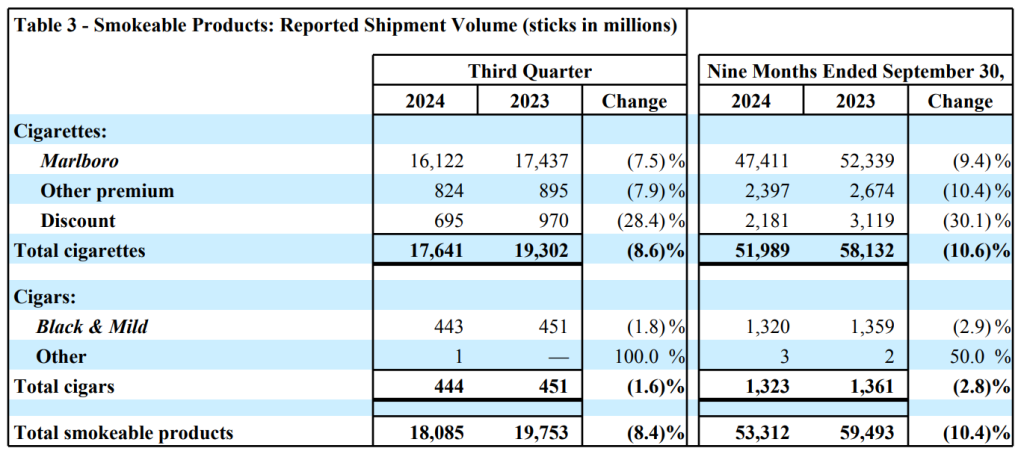
– Cigarette volume down -8.6% in Q3 and -10.6% in YTD24, primarily driven by the industry’s decline rate (impacted by macroeconomic pressures and the growth of illicit e-vapor products), trade inventory movements and retail share losses
– Adjusted for trade movements, Altria’s cigarette volume is down -11.5% in Q3 and -11% in YTD24 (industry volume down -9% in both periods)
– Altria’s smokable SoM is down -0.9pp to 46.1% in YTD24 although Marlboro held up well at 41.9% (down only -0.2pp). Marlboro’s share in the Premium segment is up +0.3pp to 59.3%
– Discount segment’s share is 29.4% (+1.1pp versus the prior year)
Business Segments: Smokeless
– Smokeless volume is up +1.2% in Q3 and down -1.3% in YTD24, primarily driven by retail share losses, partially offset by the industry’s growth rate, trade inventory movements and other factors
– Adjusted for trade movements and calendar differences, Altria’s smokeless volume is down -1% in Q3 and -2.5% in YTD24
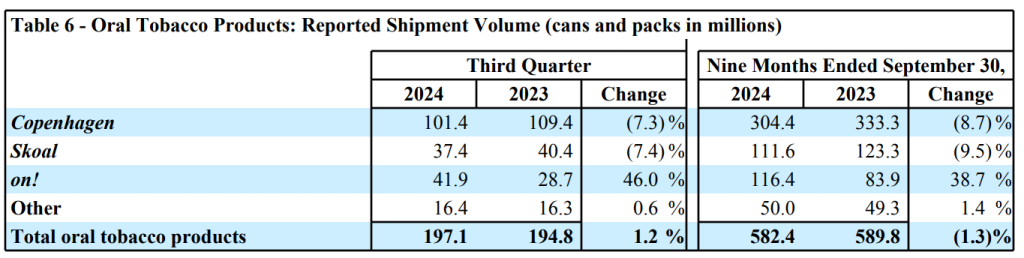
– Total smokeless industry volume increased by +7.5% in YTD24, primarily driven by growth in oral nicotine pouches (e.g. ZYN), partially offset by declines in MST volumes (e.g. Copenhagen, Skoal, Grizzly). As a result, Altria’s smokeless SoM is down -5.6pp to 37.8% in YTD24
– Nicotine pouches – Q3 2024: Category grew to 43.9% of the US oral tobacco market (+11.4pp). on! shipment volume is up +46%, reaching 41.9 million cans (- outperforming ZYN, which is up +41.4%). on!’s share of the nicotine pouch category is 20.3% (-0.9pp). Sequential improvement in on!’s performance with +0.9pp category share gained vs. Q2 2024
– Nicotine pouches – YTD24: Category grew to 41.9% of the US oral tobacco market (+12.4pp). on! shipment volume is up +38.7%, reaching 116.4 million cans. on!’s share of the nicotine pouch category is 19.1% (-3.8pp)
– on! repeat purchasers grew by +40% from 500k in Q3 2023 to 700k in Q3 2024
Business Segments: E-vapor
– NJOY consumables volume: +15.6% to 10.4 million units in Q3 2024 (33.8 million units in YTD24)
– NJOY device volume: +100% to 1.1 million units in Q3 2024 (3.9 million units in YTD24)
– NJOY SoM in the tracked channels: consumable +2.8pp to 6.2% in Q3 2024 (5.3% in YTD24)
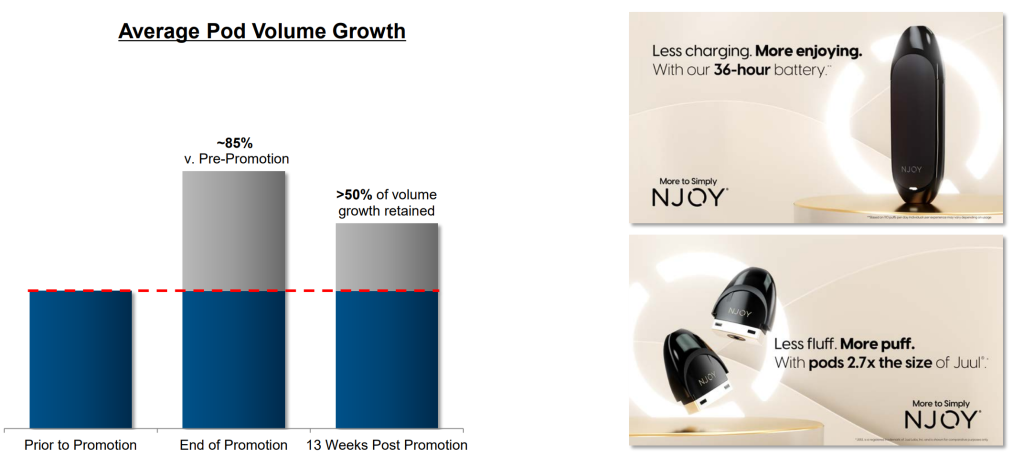
– Consumer retention is high for NJOY: more than half of the promotional volume uplift is retained 13 weeks after the end of promotion. Moreover, NJOY brand equity investments resulted in +20pp in Net Promoter Score (NPS) in YTD24 vs. 2023
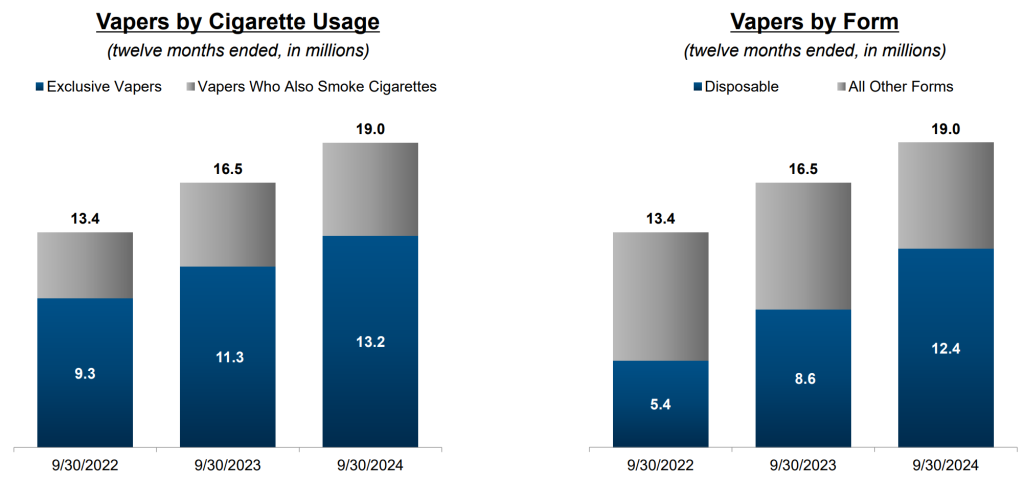
– Illicit disposable products are driving the e-vapor category growth: # of vapers increased by +2.5 million to 19 million year-on-year basis while the number of illicit disposable vape users increased by +3.8 million to 12.4 million (now representing 65% of the total users) => # of users of all other forms (i.e. pod and refillable) declined by 1.3 million
Other Highlights
– Altria calls on the US FDA to clarify its enforcement posture on synthetic nicotine products and reminds that it is illegal to sell a synthetic nicotine product in the US that has not received a market granted order from the FDA by July 2022 according to federal law
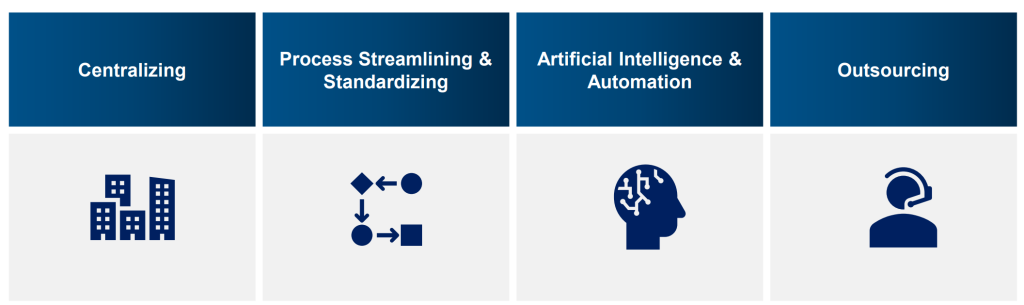
– “Optimize & Accelerate” Initiative: A multi-phase initiative to modernize ways of working and to increase organizational speed, efficiency and effectiveness. To be substantially completed in 12 to 18 months. Accelerated Business Solutions organization to be established to drive efficiency and process improvement in partnership with external service providers. Initial phases of the Initiative will deliver at least $600 million in cumulative cost savings over the next five years – excluding $100 million to $125 million of pre-tax charges and any non-cash impact from pension settlement and curtailment accounting
– NJOY Litigation: Administrative Law Judge extended the deadline for her initial determination to December 6, 2024. Altria developed strategies to keep NJOY ACE on the market or limit sales disruption in the event of certain adverse litigation outcome. Recall that the US International Trade Commission (ITC) Administrative Law Judge (ALJ) provided notice of initial determination in August 2024, supporting JUUL’s patent infringement allegations against Altria’s NJOY. For further details: Patents Wars
– Leverage: 2.1x total debt-to-EBITDA ratio as of Sept 30, 2024 (in line with the close to 2x target range)
Summary
Altria’s +7.8% year-on-year EPS growth in Q3 2024 is beyond the wildest expectation – especially considering that there is no moderation in cigarette volume decline (i.e. -11.5% for Altria and -9% for the Industry in Q3 2024). Altria continues to successfully extract more (money) from less (amount of goods sold) – in a jaw-dropping manner. Marlboro is bleeding heavily, but is not dead yet; we still believe Marlboro has enough gas power to finance Altria’s transformation provided that Altria makes smart investment decisions and achieves a quantum leap in the next 5 years. For further details: Altria: Winds of Change
A point of caution: Altria’s financials are becoming increasingly engineered – from temporary reduction in controllable costs to extra shipping days, from trade inventory movements to tax-loss harvesting, from share count reduction (financed through asset sales) to the timing of payments & fees. A lot needs to be demystified to have good understanding of the core.
In terms of business performance, incremental commercial progress achieved by NJOY and sequential category share gain by on! are the brightest spots. Fast-declining traditional tobacco market, rampant illicit trade in new nicotine products and risk of NJOY importation ban are the major headaches for Altria.
Further Readings:
References:

