


Background
Scandinavian Tobacco Group (STG) is the world’s 15th largest publicly traded tobacco company by market cap. STG became a pure-play cigar & pipe tobacco manufacturer, following the acquisition of its cigarette & snus business (“House of Prince”) by BAT in 2008. With operations mainly in Europe & the USA, STG owns well-known brands like Macanudo, La Gloria Cubana, Panter, Signature, La Paz, Café Crème, Cohiba, Partagas and Captain Black. Since 2022, STG is exploring opportunities to enter the Next Generations Products (NGP) category in order to complement its core cigar & pipe tobacco range (portfolio diversification) and to re-ignite revenue growth (“Growth Enablers”).
Q3 2025 (November 11, 2025)1
“One half of the business is in better shape, the other half is in worse shape. Net net: guidance narrowed & lowered”
Commentary: “Early signs of stable sales, but continued margin compression (driven by market/product mix and a more intense promotion environment) in Q3 2025. Global SAP solution roll-out negatively impacted the market share performance in machine-rolled cigars. The 2030 Strategy to be shared on November 20, 2025 at the Capital Markets Day”

– Net sales: down -3% to kr.2.36 billion on reported basis and up +0.3% on an organic basis (i.e. reported-to-organic: unfavorable FX-rate) in Q3 2025. Organic growth in Handmade Cigars and Next Generation Products, partially offset by organic decline in Machine-Rolled Cigars & Smoking Tobacco delivered negative organic growth. The underlying business trends remain largely unchanged with early signs of stabilization in handmade cigars
– EBITDA margin (before special items): 22% (-1.4pp) in Q3 2025 (recovery from 21.1% in Q2 2025 and 16.1% in Q1 2025). Margin decline driven by unfavorable product/market mix and commerical investments in machine-rolled cigars in key European markets
– Adjusted EPS: kr.3.4 in Q3 2025 (vs. kr.4.1 in Q3 2024)
– FCF before acquisitions: kr.173 million in Q3 2025 (vs. kr.275 million in Q3 2024)
– Leverage ratio: 2.9x at the end of Q3 2025 (vs. 2.6x at the end of 2024; leverage improvement expected in Q4 2025; year-end leverage to remain above the 2.5x target)
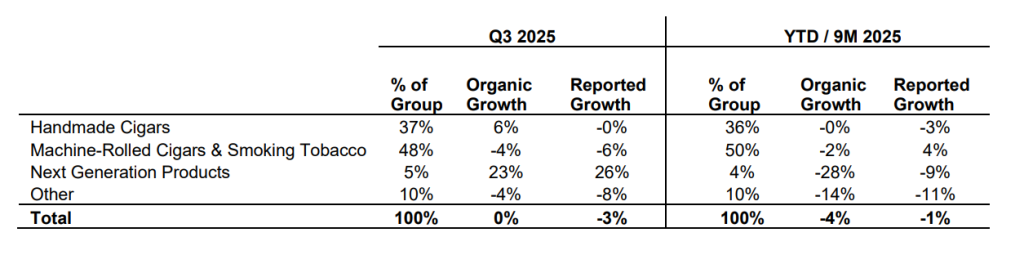
– Handmade cigars (37% of sales): revenue up +6% on an organic basis, flat on a reported basis mainly due to the weaker US$. Low single-digit organic net sales growth in U.S. handmade cigar sales (both through wholesalers/distributors and online). Double-digit growth in sales through own retail superstores, primarily driven by new store openings. Double-digit growth in international sales, following two quarters of decline
– Machine-rolled Cigars and Smoking Tobacco (48% of sales): revenue down -4% on an organic basis (Machine-Rolled Cigars: -4%, Smoking tobacco: -5%). Total market for machine-rolled cigars in key European markets down -0.6% in Q3 2025 and down -0.7% in YTD2025 (vs. -3.5% decline in FY24). Volume share down to 26.2% in Q3 2025, due to the supply instability caused by the SAP roll-out, and 26.9% in YTD25 (volume share: 27.3% in H1 2025 and 27.8% in H1 2024).
– Next Generation Products (5% of sales): revenue up +23% on an organic basis, driven by double-digit XQS growth in Sweden and the UK. XQS continues to gain market share in Sweden, now exceeding 13%. Removal of Mac Baren nicotine pouch brands, Ace and Gritt, from some markets negatively affected growth
– Other (10% of sales): revenue down -4% on an organic basis, primarily related to lower contract manufacturing
FY25 Guidance (narrowed & lowered)
– Reported net sales: kr. 9.1-9.2 billion (before: lower-end of kr. 9.1-9.5 billion)
– EBITDA margin before special items: 19.5% – 20.5% (before: 18-22%)
– Free cash flow before acquisitions: kr. 0.8-1.0 billion (no change)
– Adjusted EPS: kr. 10-12 (before: kr. 10-13)
Q2 2025 (August 27, 2025)1
“Recovery is in progress, but not at the level expected. Wide-ranging FY25 guidance indicates elevated business uncertainity”
Commentary: “Despite the challenging market environment driven by tariffs and geopolitical unrest, STG remained focused on delivering on strategic priorities. The Mac Baren integration is on track. Market positions in machine-rolled cigars stabilized. Despite a lower EBITDA margin, FY25 guidance is re-affirmed; kr. 800-1,000 million FCF in 2025. The biggest uncertainties include consumer behaviour and pricing for handmade cigars in the US as well as the US$ exchange rate. Strategy for the next five years to 2030 to be announced in Nov 2025”
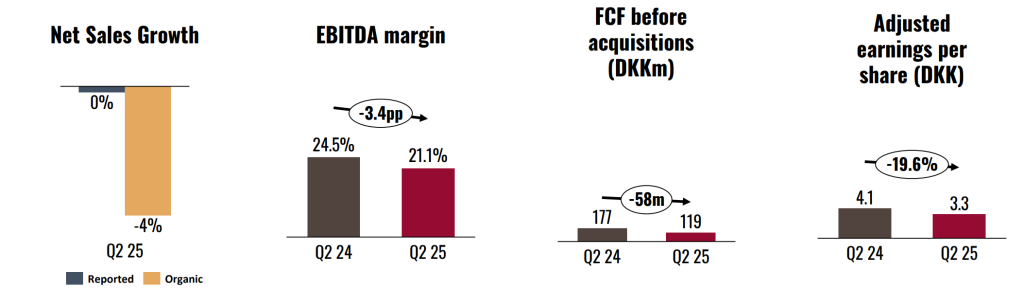
– Net sales: down -0.2% to kr.2.36 billion on reported basis and down -4.1% on an organic basis (i.e. reported-to-organic: mostly, Mac Baren acquisition and FX-rate) in Q2 2025
– Net sales negatively impacted by the discontinued online distribution of ZYN in the U.S (-3% impact) and lower sales from contract manufacturing and of accessories in the profitable Australian market. Net sales flat excluding these two items. Organic growth recovered in Handmade Cigars and Machine-Rolled Cigars & Smoking Tobacco. Double-digit growth (+17%) in XQS nicotine pouches.
– EBITDA margin (before special items): 21.1% (-3.4pp) in Q2 2025 (recovery from 16.1% in Q1 2025)
– EBITDA margin decline driven by a combination of product and market mix, investments made in re-gaining market shares in machine-rolled cigars in key European markets, discontinuation of distribution of ZYN in the US and generally challenging market conditions. The discontinuation of ZYN will not impact the year-on-year comparisons from Q3 2025
– Adjusted EPS: kr.3.3 in Q2 2025 (vs. kr.4.1 in Q2 2024)
– FCF before acquisitions: kr.119 million in Q2 2025 (vs. kr.177 million in Q2 2024)
– Leverage ratio: 2.9x at the end of Q1 2025 (vs. 2.6x at the end of 2024; net interest-bearing debt increased by kr.275 million versus year-end 2024 to kr.5,698 million; leverage increase further amplified by lower EBITDA)
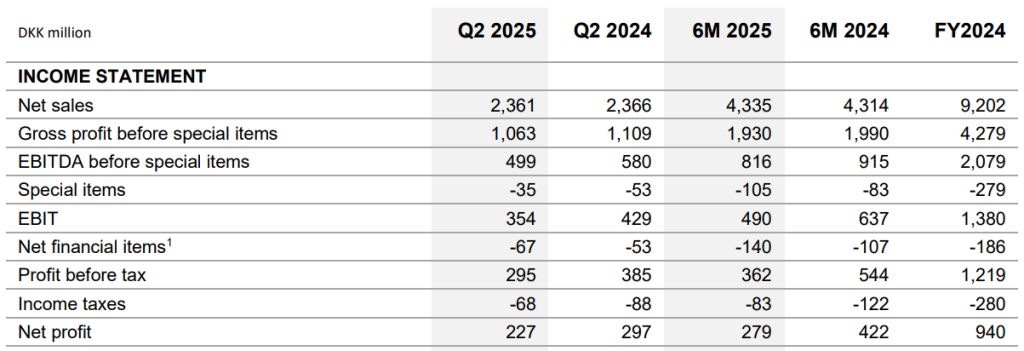
– Handmade cigars (36% of sales): revenue up +1% on an organic basis, driven by the recovery of sales in the key U.S. market. Online sales of handmade cigars were slightly down, while sales through retail superstores continue to increase (note: 2 new store openings in H2 2025, bringing the total number to 15). In B2B, a low single-digit volume decline rate was more than offset by strong pricing. Negative growth in international markets (less than 3% of group net sales), driven by the Asian markets. With 6% volume share outside North America, STG is #3 in the international markets
– Machine-rolled Cigars and Smoking Tobacco (51% of sales): revenue up +3% on an organic basis, primarily driven by the smoking tobacco (+10%). Machine-rolled cigars delivered negative growth (-2%). Machine-rolled cigar category in key European markets grew+1.5% in Q2 2025 (vs. -2.2% in Q1 2025 and -3.5% in FY24). Despite the +1.5% market growth in Q2 2025, STG continues to expect the market to decline by 2%-3% per annum. STG volume share recovered to 27.7% compared with the temporary drop in Q1 2025. STG volume share is estimated at 27.3% in H1 2025 (vs. 27.8% in H1 2024). Revenue up +11%, including the Mac Baren acquisition.
– Next Generation Products (4% of sales): revenue down -43% on an organic basis, driven by the discontinuation of the distribution of ZYN in US online business (-47% impact) and market exits for the Ace and Gritt nicotine pouches. XQS delivered double-digit growth both in Sweden and in the UK; XQS market share in Sweden exceeded 12% at the end of the quarter. However, XQS investments continue to put pressure on the margins
– Other (9% of sales): revenue down -23% on an organic basis, primarily related to lower contract manufacturing and lower sales of accessories in Australia.
– The new five-year strategy: to be announced at the virtual Capital Markets Day on Nov 20 2025
– Net debt increased by kr.275Mn due to kr.670Mn dividend payment in April 2025; leverage increased to 2.9x and will remain above the 2.5x target at the end of 2025
FY25 Guidance (re-affirmed)
– Reported net sales: kr. 9.1-9.5 billion (lower-end)
– EBITDA margin before special items: 18-22%
– Free cash flow before acquisitions: kr. 0.8-1.0 billion
– Adjusted EPS: kr. 10-13
Q1 2025 (May 20, 2025)
“Weak Q1 2025 results across the board. Facing multiple challenges at the same time. FY25 Guidance lowered”
Commentary: “Adjusting FY25 expectations to reflect the impact of a weaker US$ and increasing tariffs on imported goods to the U.S. Although consumer sentiment is affected negatively, the underlying business trends remain largely unchanged. Focus is on preserving market shares and cash flow with a wider guidance range on the EBITDA margin. Good progress in the integration of Mac Baren”
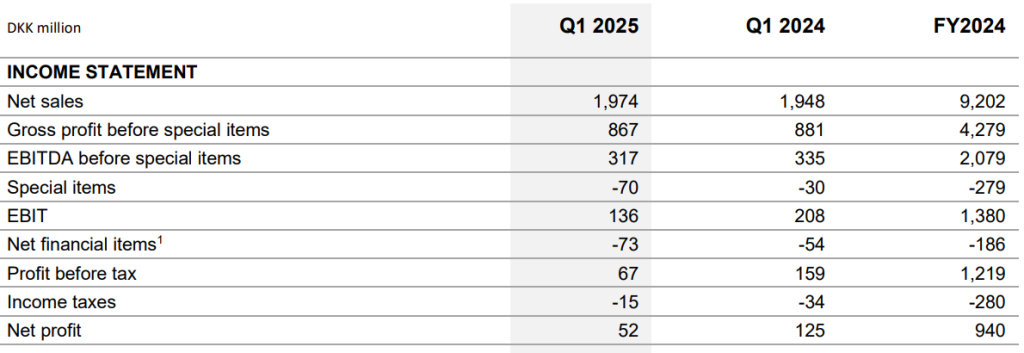
– Net sales: Up +1.3% to kr.2.0 billion on reported basis and down -8.8% on an organic basis (i.e. reported-to-organic: mostly, Mac Baren acquisition) in Q1 2025
– Net sales negatively impacted by the discontinued online distribution of ZYN in the U.S, lower consumption of handmade cigar sales in the U.S. and temporary supply issues related to the go-live of SAP in European factories phasing some machine-rolled cigar sales later quarters, partially offset by the high double-digit (+41%) growth in XQS nicotine pouches
– EBITDA margin (before special items): 16.1% (-1.0pp) in Q1 2025
– EBITDA margin decline driven by a combination of product and market mix, investments made in re-gaining market shares in machine-rolled cigars in key European markets and the expansion of nicotine pouch business
– Adjusted EPS: kr.1.5 in Q1 2025 (vs. kr.1.8 in Q1 2024)
– FCF before acquisitions: kr.156 million in Q1 2025 (vs. -kr.126 million in Q1 2024)
– Leverage ratio: 2.5x at the end of Q1 2025 (vs. 2.6x at the end of 2024)
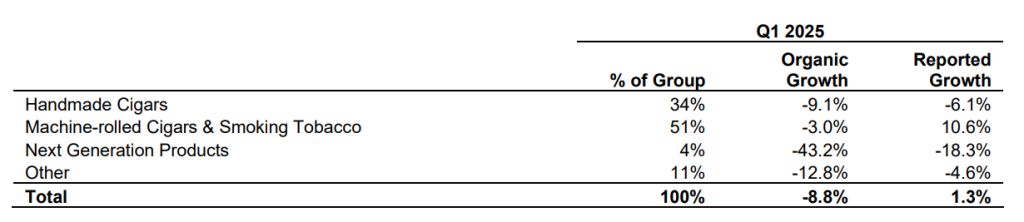
– Handmade cigars (34% of sales): revenue down -9.1% on an organic basis, driven by a double-digit decline in sales to wholesalers and distributors in the US and international markets. Impacted by the general decline in consumption in the US and by phasing between the quarters. Sales through retail superstores increased by 21% driven by new store openings (13 “Cigars International” branded retail superstores in the U.S.)
– Machine-rolled Cigars and Smoking Tobacco (51% of sales): revenue down -3.0% on an organic basis, primarily driven by -2.2% decline in machine-rolled cigar category in key European markets (vs. -3.5% decline in FY24). Market share down from 28.1% in Q4 2024 to 26.9% in Q1 2025 due to the SAP implementation in Q1 2025 in European factories. Production and shipments are normalized with market share recovering in April 2025
– Next Generation Products (4% of sales): revenue down -43% on an organic basis, driven by the discontinuation of the distribution of ZYN in US online business (-34% impact) and market exits for the Ace and Gritt nicotine pouches. XQS continues to deliver strong growth (+41%) and XQS market share in Sweden exceeded 11% at the end of the quarter. The roll-out of the brand in the UK and Denmark continues to progress albeit at a slower pace
– Other (11% of sales): revenue down -13% on an organic basis, primarily related to contract manufacturing and filters/accessories in Australia
FY25 Guidance: Revised down
As consequence of the recent changes in U.S. international trade policy (i.e. 10% tariff on imported goods, partially offset by price adjustments introduced ) and due to the translation effect from a lower US$ (i.e. 5% depreciation versus kr. since March 2025), STG revises down the FY25 guidance. Despite a weak Q1 2025, the underlying business trends remain largely unchanged. However, uncertainty related to U.S. consumer sentiment, down trading and retailer decisions on inventory has increased. The U.S. market accounts for ~45% of the STG’s net sales.
– Reported net sales: kr.9.1-9.5 billion (previously: kr.9.2-9.7 billion)
– EBITDA margin: 18-22% (previously: 20%-23%); negatively impacted by ~50bps solely due to the tariffs impacting both the cost and retail prices. To maintain full flexibility to protect market shares and develop business, the range for the FY25 EBITDA margin expectation widened to 400bps
– Free cash flow: kr.0.8-1.0 billion (previously: kr.0.8-1.1 billion); impacted by CAPEX investments of up to kr.300 million including factory consolidations, OneProcess investments and the opening of two new retail super stores in the US. Special cash items of kr.200 million, primarily relating to the Mac Baren integration and roll-out of SAP 4/Hana ERP solution
– Adjusted EPS: kr.10.0-13.0 (previously: kr.11.0-14.0)
References:

