


Key Business Metrics1
Revenue: up +9.3% to $9.14Bn (vs. $9.2Bn expected). Surpassed the $9Bn threshold for the first-time
Adjusted diluted EPS: up +20.3% to $1.67 (vs. $1.61 expected)
Adjusted operating income margin: 40.8% (still 0.7pp below Q3 2022)
Total volume: up +2.2% to 193.6Bn (HnB volume: +18% to 32.5Bn; cigarette volume: -0.5% to 161.1Bn)
Smoke-free revenue: $3.3Bn => 35.6% of total revenue

Key Highlights
– Combustibles: Strong pricing (+9%) & resilient volume (-0.5%) resulting in net revenue growth of 4.3% (6.2% on an organic basis) => implies some deterioration in market/product mix
– Heated Tobacco: HnB SoM in IQOS markets up by 1.2pp to 9.0% (- versus 9.2% in Q2 2023). Adjusted HnB in-market sales volume up +14.4%. Total IQOS users at quarter-end: 19.7Mn exclusive, 27.4Mn total (up by 0.2 Mn vs. June 2023 => significant slow-down in consumer acquisition due to “seasonality”)
– Oral Tobacco: Total volume up +20% to 204.9Mn cans. ZYN shipment volume in the US is up +65.7% to 105.4Mn cans (vs. Q3 2022 Swedish Match shipments of 63.6Mn cans) whereas the nicotine pouch volume is up only by +2.8% in Scandinavia and snus volume is down by -11.6% (primarily, due to Scandinavia)
– Inventory Movements: Net favorable, primarily driven by the HnB inventory movements in Japan (i.e. shift from air to sea freight). Adjusted HnB IMS increased by +14.4% (Europe: +16.1%, Japan: +11.7%). Excluding Russia & Ukraine, adjusted HnB IMS increased by +15.7%.
FY23 Guidance
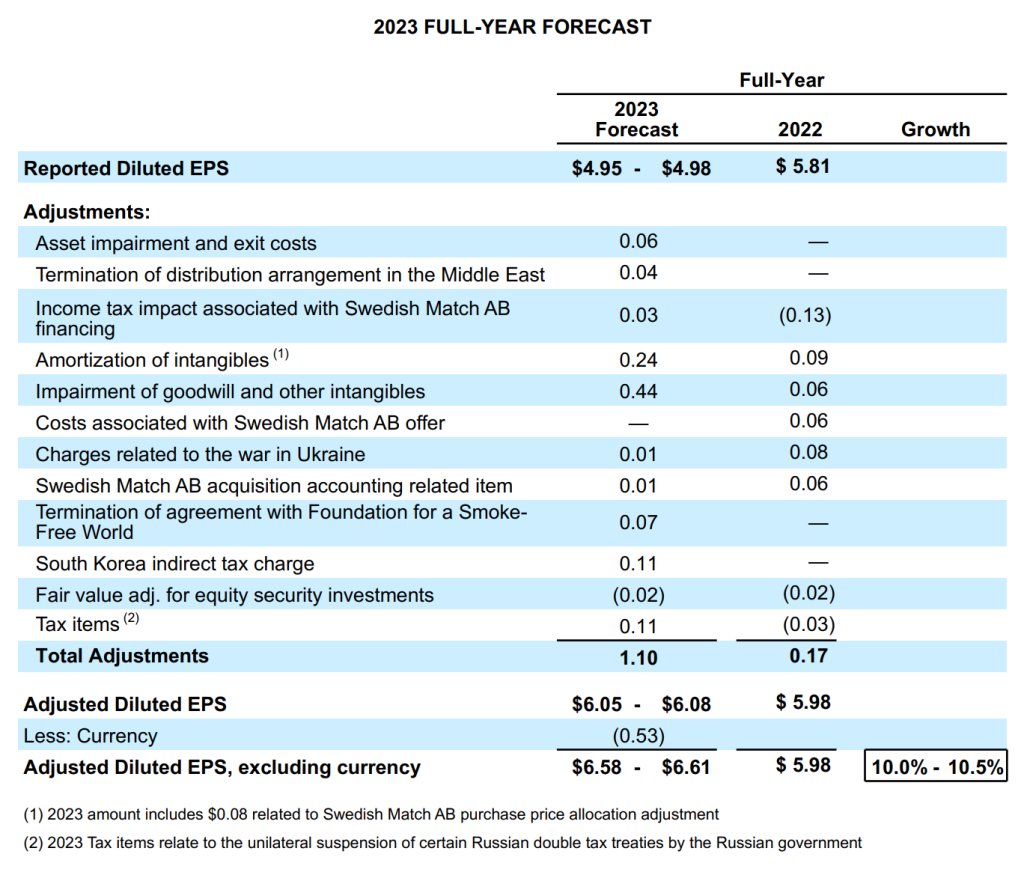
PMI revises the reported FY23 EPS further down to $4.95-4.98 (from $5.19-5.28) and revises the fully adjusted EPS (excluding the one-off items & currency) further up to $6.58-$6.61 (from $6.46-$6.55). One-off adjustments are up from $0.77 to $1.10 and negative FX-impact is up from $0.50 to $0.53. Thereby, PMI’s reported EPS is set to decline by 14.3%-14.8% whereas its fully adj. EPS is set to increase by 10%-10.5% in 2023.
New one-off adjustments include:
– a tax charge related to the unilateral suspension of certain Russian double tax treaties by Russia ($0.11)
– an income tax impact associated with the Swedish Match financing ($0.09)
– higher amortization of intangibles related to purchase price allocation adjustments for the SWMA acquisition ($0.08)
– costs related to the termination of pledge agreement with the Foundation for a Smoke-Free World ($0.07)
FY23 Assumptions
International (ex-China & US) industry volume: down -1.5% to -2% (previously down -0.5% to -1.5%; industry volume trend deteriorating)
PMI volume: up +1% to 1.5% (previously, up +1% at best)
HnB volume: 125-130Bn (lower half: reflecting the impact of a further delayed market launch in Taiwan, very limited growth in Russia and Ukraine, as well as some uncertainty related to inventory levels in the EU due to the upcoming HTU flavor ban)
Nicotine pouch volume: 390-410Mn cans (previously, 370-400Mn cans, reflecting the stellar performance of ZYN in the US)
PMI cigarette volume: down -1% to -2% (previously down -1.5% to -2.5%; PMI is set to gain SoM in the cigarette category)
Net revenue: up +8% (previously, +7.5% to +8%)
Adjusted operating income margin: towards the upper-end of -50 to -150 basis points decline range
Incremental investments: $150Mn, broadly even split between the US and the Wellness & Healthcare segment
Net financing costs: $1.1Bn (previously, $1.2Bn)
Operating cash flow: $10Bn (previously, $10-11Bn); Capex: $1.3Bn; No share repurchases
Wellness & Healthcare revenues of $300Mn with an operating loss of $150Mn (no change)
Recollection
All as foreseen in our previous articles:
PMI – Q3 2023 Results: Preview
References:

