


Top-line & Bottom-line Results1
Q1 2025 Revenue: $4.52Bn (exp. $4.62Bn; down -4.2% vs. $4.72Bn in Q1 2024)
Q1 2025 EPS: $1.23 (exp. $1.19; up +6% vs. $1.16 in Q1 2024)
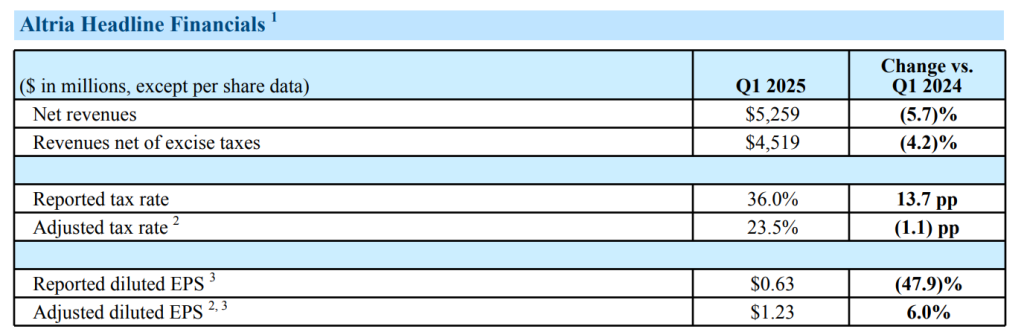
FY25 Guidance: EPS in a range of $5.30 to $5.45, representing a growth rate of 2% to 5% from $5.19 in 2024 (re-affirmed)
Business Segments: Smokable
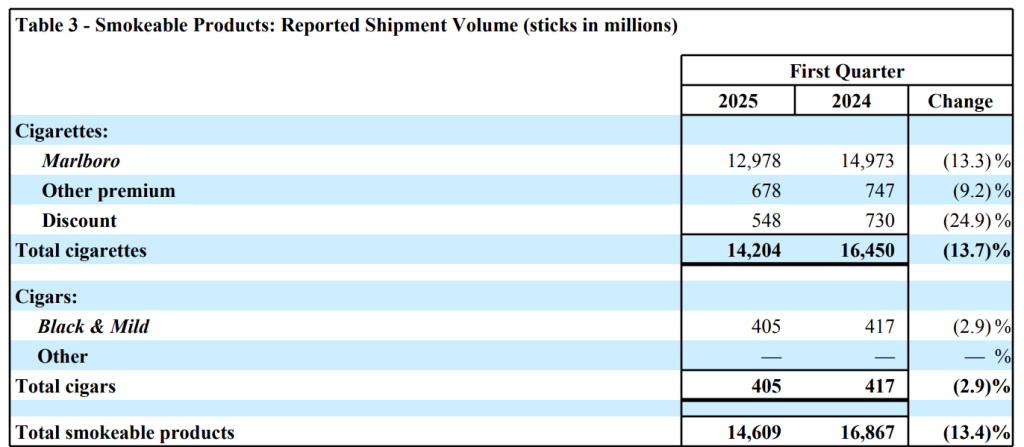
– Cigarette volume decreased -13.7% (down -12% on an adjusted basis), driven by the industry’s decline (down 9% on an adjustment basis; impacted by macroeconomic pressures on discretionary income and the growth of illicit e-vapor products) and retail share losses
– Marlboro retail share: 41.0% (down -1pp vs. Q1 2024 and -0.3pp sequentially)
– Marlboro share of the premium segment: 59.3% (up +0.1pp vs. Q1 2024 and unchanged sequentially)
– Altria retail share: 45.0% (down -1.4pp vs. Q1 2024)
– Average Marlboro net price: $9.35 (+$0.66 or +7.6% versus previous year)
– Cigar volume decreased 2.9%
Business Segments: Smokeless
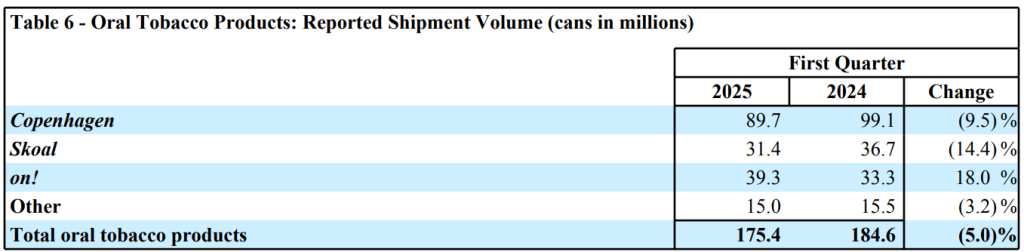
– Oral tobacco shipment volume: down -5% (adjusted -1%), driven by retail share losses (to ZYN) and trade inventory movements, despite the category growth (up +10% in Q1 2025, driven by growth in nicotine pouches, partially offset by declines in MST)
– Oral tobacco retail share: 34.7% (down -3.1pp, due to Copenhagen & Skoal share losses)
– On! retail share: 8.8% (+1.8pp vs. Q1 2024 and +0.1pp sequentially)
– The U.S. nicotine pouch category: 49.1% of the U.S. oral tobacco category (+8.7pp vs. Q1 2024)
– On! shipment volume: +18% to 39.3 million cans in Q1 2025 (ZYN shipment volume up +53.8% to 202.4 million cans in the same period)
– On!’s share of the nicotine pouch category: 17.9% (+0.5pp vs. Q1 2024); Average on! price: $3.94/can (+14.2% vs. Q1 2025)
Note: In September 2008, Altria acquired UST in a transaction valued at ~$11.7 billion (including $1.3 billion debt) to gain the control of the leading premium MST brands, Copenhagen and Skoal. Altria’s smokeless share (Copenhagen, Skoal, on!) is now down to 34.7%. In Q1 2025, ZYN alone shipped 202 million cans in the U.S. – more than Copenhagen, Skoal, on! combined (175 million cans).
Business Segments: E-vapor
– NJOY shipment volume: 13.5Mn consumable units (+23.9%) and 0.3Mn devices (-70%)
– Retail share of NJOY (multi-outlet and c-stores): 6.6% in Q1 2025 (up +2.4pp sequentially)
– 20.5 million vapers (+2.5 million, +14% year-on-year basis) in the U.S. at the end of Q1 2025: 14.5 million (71%) of which are disposable vape users (+4 million, +38% year-on-year basis)
– On March 31, 2025, the ITC’s importation ban and cease-and-desist orders applicable to NJOY ACE went into effect. While NJOY discontinued shipments of ACE to wholesalers as of March 24, 2025, retailers are permitted to sell through their existing inventory of ACE
– As a result of the ITC orders going into effect, Altria recorded a non-cash impairment charge of $873 million to the e-vapor reporting unit goodwill in Q1 2025 (no income tax benefit)
Capital Allocation
– Dividend payments: $1.7 billion in Q1 2025
– Share repurchases: 5.7 million shares for $326 million (average price: $57.2/share). $674 million remaining under the authorized $1 billion SRP to be completed by the end of this year
– Debt: 2.1x total debt-to-EBITDA ratio (as of March 31, 2025)
Summary
In terms of the current state of business, there is nothing much to cheer about in Altria’s Q1 2025 disclosures: fast-declining traditional U.S. tobacco market (both cigarettes & moist smokeless) and the minimal presence of Altria in the new nicotine categories drive 4.2% year-on-year decline in net revenue. Altria is under increasing pressure to extract profit growth from a smaller top-line.
The brighest spot in Altria’s Q1 2025 results is the growth of on! nicotine pouches (+18% year-on-year) – yet, on!’s performance is pretty bleak when compared to the distant market-leader ZYN’s performance (+54% year-on-year). Moreover, the rampant illicit trade in vape products and NJOY importation ban continue to be the major headaches for Altria. NJOY impairment charges, the need to re-assess the 2028 smoke-free volume/revenue targets and the abolishment of NJOY-specific financial targets resurface the reluctance on Altria’s ability to achieve success in transformation to smoke-free (i.e. by maintaining its market position and profitability).
Nevertheless, we will re-iterate: Marlboro has enough gas power to finance Altria’s transformation provided that Altria makes smart investment decisions and achieves a quantum leap in the next 5 years. For further details: Altria: Winds of Change. That being said, as NJOY turns out to be another scandalous investment by Altria, it is increasingly difficult to be optimistic about Altria’s transformation journey.
Further Readings:
References:

