


Ahead of Q2 2025 Earnings release
Release date: July 30, 2025 (before the opening bell)
Revenue: $5.19 billion expected (-1.7% vs. $5.28Bn in Q2 2024)
EPS: $1.387 expected (+5.9% vs. $1.31 in Q2 2024)
Latest guidance: FY25 adjusted diluted EPS in a range of $5.30 to $5.45, representing a growth of 2% to 5% from a base of $5.19 in 2024
Q2 2025 Results1
Q2 2025 Revenue: $5.29Bn (expected $5.19Bn; up +0.2% vs. $5.28Bn in Q2 2024)
Q2 2025 EPS: $1.44 (expected $1.387; up +8.3% vs. $1.31 in Q2 2024)
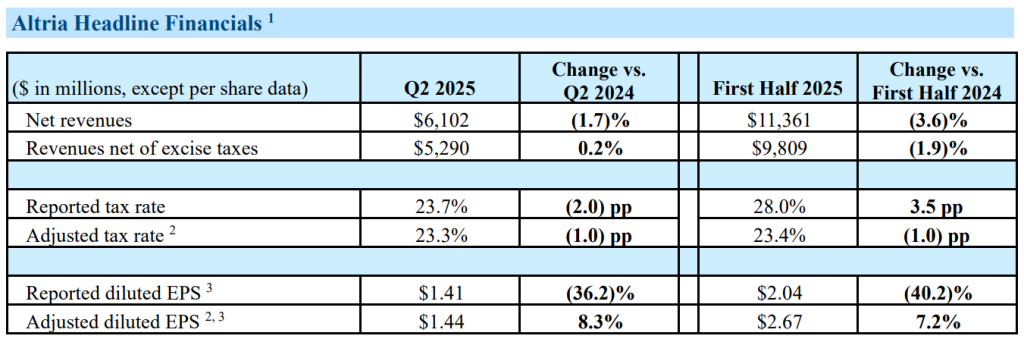
FY25 Guidance: EPS in a range of $5.35 to $5.45, representing a growth rate of 3% to 5% from $5.19 in 2024 (previously, $5.30 to $5.45; lifts up the lower-end of the range by 5¢)
Business Segment: Smokable
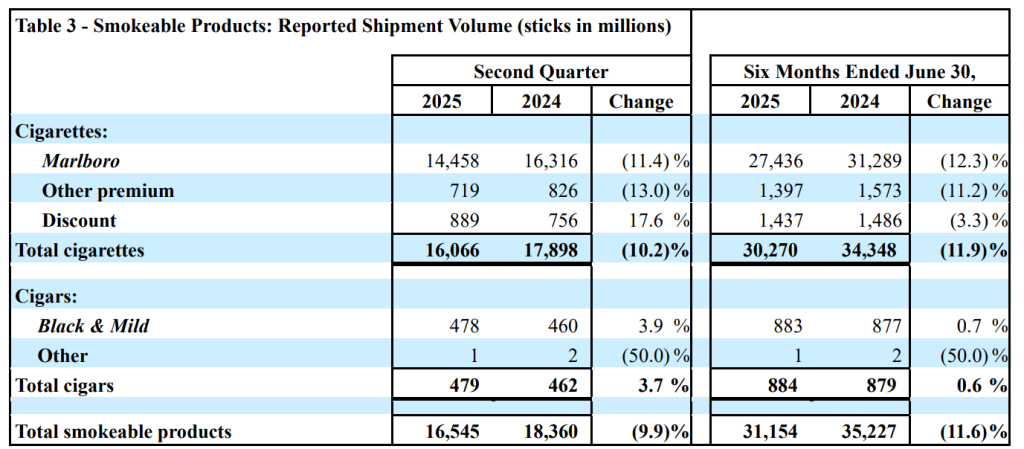
– Cigarette volume decreased -10.2% (down -10.5% on an adjusted basis), driven by the industry’s decline (down 8.5% on an adjustment basis; impacted by macroeconomic pressures on discretionary income and the growth of illicit e-vapor products) and retail share losses
– Marlboro retail share: 41.0% (down -0.9pp vs. Q2 2024 and unchanged sequentially)
– Marlboro share of the premium segment: 59.5% (up +0.2pp vs. Q2 2024 and sequentially)
– Altria retail share: 45.2% (down -1.0pp vs. Q2 2024, up +0.2pp sequentially)
– Targeted deployment of Basic brand in 30k stores [to attract consumers impacted by macroeconomic pressures on discretionary income] is supportive of Altria SoM without jeopardizing the strength of the Marlboro brand
– Altria will look for partnerships to take advantage of the federal tax rebate for imported cigarettes when the same amount is exported. Altria paid close to $3.5 billion cigarette federal excise tax in 2024

– Average Marlboro net price: $9.54 (+$0.66 or +7.4% versus previous year)
– Wholesale Inventory: 2.4 billion sticks at the end of Q2 2025 (+0.2 billion vs. Q2 2024)
– Cigar volume increased by +3.7%
Business Segment: Smokeless
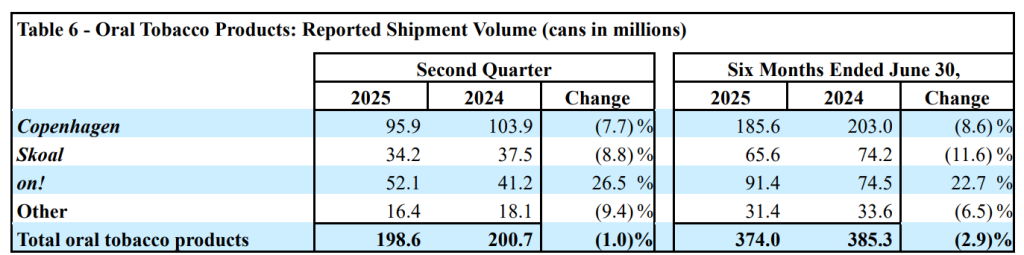
– Oral tobacco shipment volume: down -1% (adjusted -4%), driven by retail share losses (to ZYN and VELO) and trade inventory movements, despite the category growth (up +11% in H1 2025, driven by growth in nicotine pouches, partially offset by declines in MST)
– Oral tobacco retail share: 33.1% (down -4.6pp, due to Copenhagen & Skoal share losses)
– On! retail share: 8.7% (+1.2pp vs. Q2 2024 and -0.1pp sequentially)
– The U.S. nicotine pouch category: 50.6% of the U.S. oral tobacco category (+9.4pp vs. Q2 2024)
– On! shipment volume: +26.5% to 52.1 million cans in Q2 2025 (ZYN shipment volume up +40% to 190 million cans in the same period)
– On!’s share of the nicotine pouch category: 17.3% (-0.9pp vs. Q2 2024)
Business Segment: E-vapor
– In June 2025, the Patent Trial & Appeal Board rejected Altria’s request to invalidate JUUL’s patent
– Completed the product design of a modified NJOY ACE solution that addresses all four disputed patents. In addition, actively building out a broader vapor portfolio with products that align with evolving consumer expectations
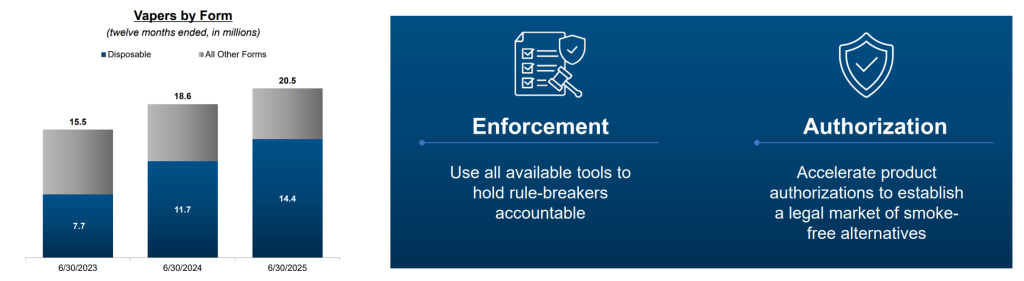
– 20.5Mn vapers in the U.S. (+10% yoy), 70% of which uses (illicit) disposable vapes
– Positive enforcement actions against illicit e-vapor: Strengthened FDA importation policy (reduced possibility of imported vapor products bypassing FDA review), Tighter border controls (increased percentage of rejections of inproperly declared e-vapor shipments), FDA warning letters to 24 importers responsible for importing illicit products, State attorneys general warnings and civil litigation addressing illicit Chinese vapor importers and distributors
Capital Allocation
– Dividend payments: $1.7 billion in Q2 2025 ($3.5 billion in H1 2025)
– Share repurchases: 4.7 million shares for $274 million in Q2 2025 (average price: $58.63 per share). 10.4 million shares for $600 million in H1 2025 (average price: $57.71per share). $400 million remaining under the authorized $1 billion SRP to be completed by the end of this year
– Leverage: 2.0x debt-to-EBITDA ratio (as of June 30, 2025)
Summary
In terms of the current state of business, there is nothing much to cheer about in Altria’s Q2 2025 disclosures: fast-declining traditional U.S. tobacco market (both cigarettes & moist smokeless) and the minimal presence of Altria in the new nicotine categories – except on!, which losing category share. However, we have seen a more scrapy Altria in the Q2 2025 Earnings release:
– Tactical/targeted deployment of Basic in the discount segment and sequential cigarette market share increase
– Plan to look for partnerships to take advantage of the federal tax rebate ($3.5 billion paid in 2024)
– Strength of John Middleton in the large machine-made cigar segment
– A suprisingly strong on! shipment volume despite a tough comparator and share loss (caveat: inventory build-up as an indicator of strong promotional activity in H2 2025)
– Readiness of NJOY ACE workaround and future vape product pipeline
– Altria’s ability to influence the fight against the illicit/illegal vapes.
We will repeat for the millionth time: Marlboro has enough gas power to finance Altria’s transformation provided that Altria makes smart investment decisions and achieves a quantum leap in the next 5 years. For further details: Altria: Winds of Change. Today could be a good start to this long, treacherous journey – at the end of which, the success is not guaranteed.
Further Readings:
References:

