


Ahead of Q4 2025 Earnings release
Release date: January 29, 2026 (before the opening bell)
Revenue: $5.03 billion expected (-1.5% vs. $5.106Bn in Q4 2024)
EPS: $1.32 expected (+2.3% vs. $1.29 in Q4 2024)
Latest guidance: FY25 EPS in a range of $5.37 to $5.45, representing a growth rate of 3.5% to 5.0% from a base of $5.19 in 2024. YTD25 EPS of $4.12 => implying Q4 2025 EPS of $1.25 to $1.33
Q4 2025 Results1
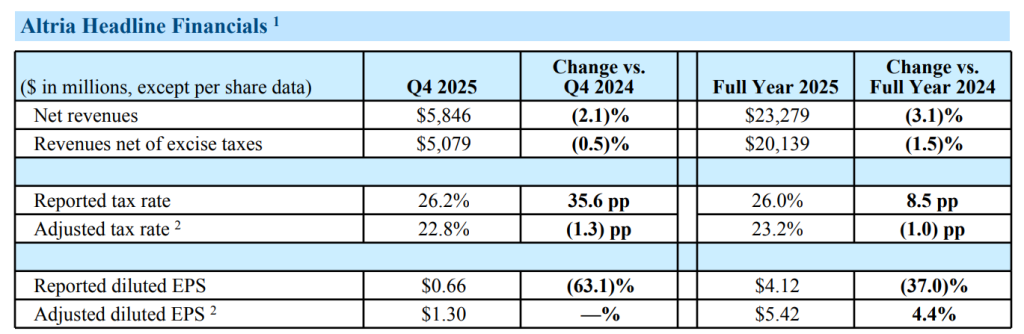
Q4 2025 Revenue: $5.079 billion (expected $5.03 billion; down -0.5% vs. $5.106Bn in Q4 2024)
Q4 2025 EPS: $1.30 (expected $1.32)
FY25: EPS of $5.42, representing a growth rate of 4.4% from $5.19 in 2024 (guidance: in a range of $5.37 to $5.45)
Business Segment: Smokable
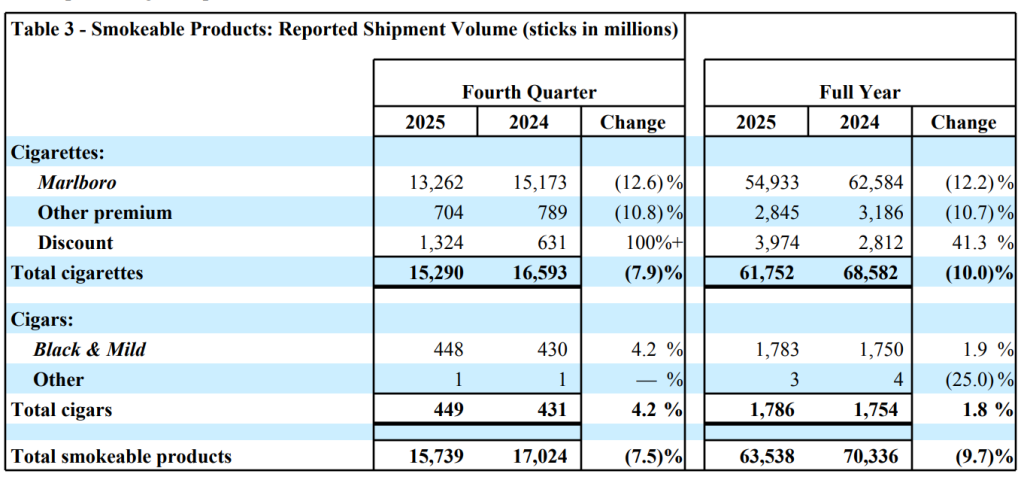
– Cigarette volume decreased by -7.9% (down -7% on an adjusted basis), driven by the industry’s decline (down -6.5% on an adjusted basis; impacted by macroeconomic pressures on discretionary income and the growth of illicit e-vapor products) and retail share losses
– Marlboro retail share: 39.8% (down -1.5pp vs. Q4 2024 and -0.6pp sequentially; below 40% for the first-time ever in the moderrn history)
– Marlboro share of the premium segment: 59.2% (down -0.1pp vs. Q4 2024 and -0.4pp sequentially)
– Altria retail share: 45.2% (down -0.2pp vs. Q4 2024 and sequentially); targeted deployment of Basic brand [to attract consumers impacted by macroeconomic pressures on discretionary income] is supportive of Altria SoM
– Average Marlboro net price: $9.87 (+$0.67 or +7.3% versus previous year)
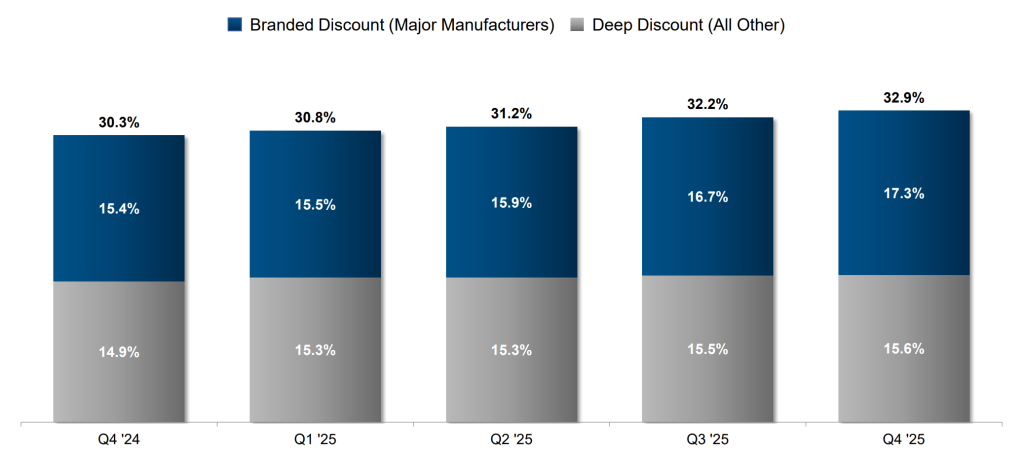
– Discount segment: up 2.6pp to 32.9% in Q4 2025. Altria’s Basic SoM: up +1.9pp to 2.1%
– Wholesale Inventory: 2.6 billion sticks at the end of Q4 2025 (vs. 2.5 billion sticks Q4 2024; +0.1 billion sticks inventory build-up)
– Cigar (John Middleton) volume increased by +4.2% to 449 million units (outperforming the mass cigar segment)
Business Segment: Smokeless
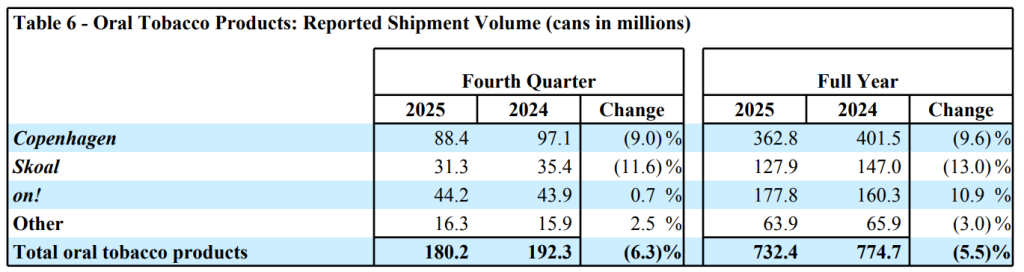
– Oral tobacco shipment volume: down -6.3% (down -6% adjusted), driven by retail share losses (to ZYN and VELO) and trade inventory movements, despite the category growth (up +14% in the past six months, driven by growth in nicotine pouches, partially offset by declines in MST)
– Oral tobacco retail share: %29.6 (down -6.5pp, all brands losing market share)
– On! retail share: 7.7% (-1.0pp vs. Q4 2024 and -0.6pp sequentially)
– The U.S. nicotine pouch category: 56.9% of the U.S. oral tobacco category in Q4 2025 (+10.4pp vs. Q4 2024)
– On! shipment volume: +0.7% to 44.2 million cans in Q4 2025
– On!’s share of the nicotine pouch category: 13.4% (-5.3pp vs. Q4 2024)
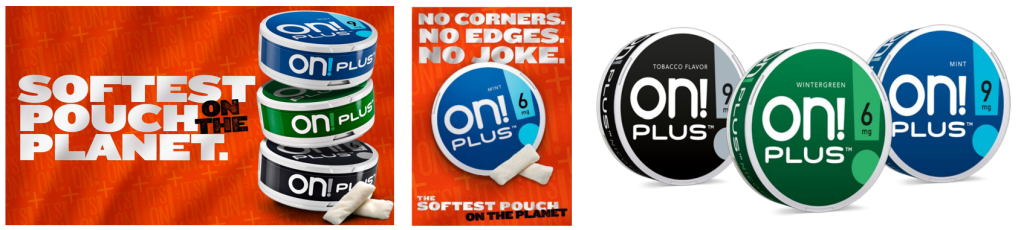
– Launched premium, differentiated on! PLUS product in Florida, North Carolina and Texas in mint, wintergreen and tobacco flavors, each with 6mg, 9mg and 12mg nicotine strengths. National on! PLUS launch planned in the first half of 2026
– In December 2025, Altria received U.S. FDA marketing authorizations for the 6mg and 9mg variants. The 12mg nicotine strength variants remain under FDA review. In November 2025, Altria submitted premarket tobacco product applications (PMTAs) for on! PLUS products in six additional flavor varieties across three nicotine strengths
– International expansion: on! and on! PLUS are competing internationally via e-commerce and at select retail locations in Sweden and the United Kingdom. FUMi is available across 40,000 retail locations in seven international markets, supported by a differentiated portfolio with 12 flavors
Business Segment: E-vapor & Heated tobacco
– In FY26 Guidance, Altria assumes limited impact on combustible and e-vapor product volumes from illicit enforcement efforts and no NJOY ACE return to the marketplace in 2026.
– For Q4 2025 and FY25, Altria recorded pre-tax charges of $1.3 billion (or $0.61 per share) and $2.2 billion (or $1.14 per share), respectively, primarily due to non-cash impairments of the e-vapor reporting unit goodwill and definite-lived intangible assets in the e-vapor products segment
– Number of vapers up +5% to 21 million. 72.5% uses disposable vapes. E-vapor category volume up +15% to 7-billion packs equivalent. Illicit products represent 70% of the category
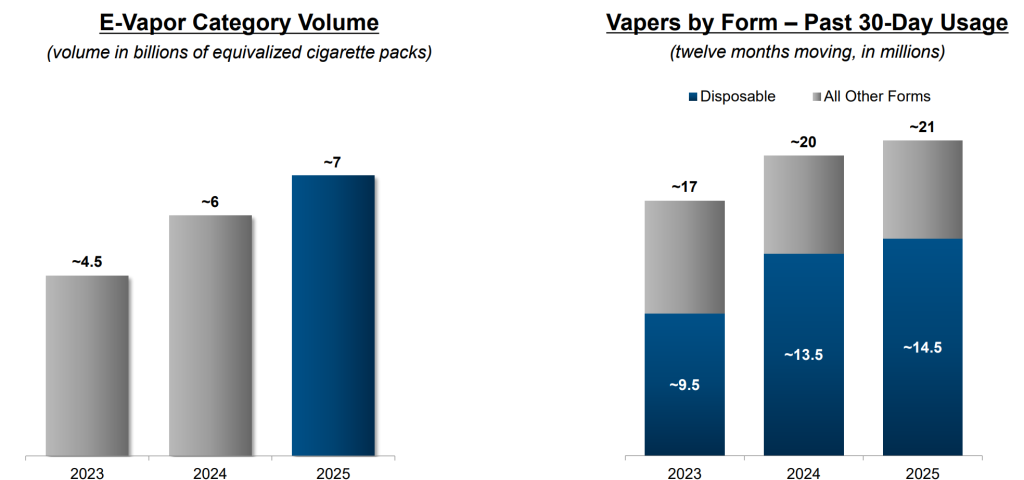
– Cross-category cigarette volume impact: now estimated at 2% to 3%, primarily driven by illicit flavored disposable e-vapor products (previously, 3% to 4%)
Capital Allocation
– Dividend payments: $1.8 billion in Q4 2025 ($7.0 billion in FY25)
– Share repurchases: 4.8 million shares for $288 million in Q4 2025 (average price: $59.56 per share). 17.1 million shares for $1 billion in FY25 (average price: $58.50 per share). Existing share repurchase program (SRP) expanded from $1 billion to $2 billion, which now expires on December 31, 2026. $1 billion remaining under the authorized $2 billion SRP
– Leverage: 2.0x debt-to-EBITDA ratio as of December 31, 2025
– Optimize & Accelerate Initiative: a cumulative saving of at least $600 million by the end of 2029 (over a 5-year period) – excluding exit and implementation costs (pre-tax charges of c.$175 million vs. the previous estimate of c.$125 million)
FY26 Guidance
– Adjusted diluted EPS in a range of $5.56 to $5.72, representing a growth rate of 2.5% to 5.5% from a base of $5.42 in 2025
– H2-weighted growth, reflecting a progressive increase in cigarette import and export activity over the course of the year
– Effective tax rate: in a range of 22.5% to 23.5% (versus 23.2% in FY25)
– CAPEX: $300-$375 million, which includes planned investments to support contract manufacturing capabilities and innovative products (note: a major bump compared to the FY25 guidance of $175-$225 million). Depreciation and amortization expenses: c.$225 million
Downloads:
Altria – Q4 2025 – Press Release
Altria – Q4 2025 – Quarterly Metrics
Altria – Q4 2025 – Presentation
Further Readings:
References:

