Every Sunday, we run a quick poll on the hottest subject in the Tobacco Industry. Hundreds of our Twitter/X followers vote, offering a collective wisdom on the subject matter or an immediate pulse on the market/industry developments.
Results of the Sunday polls:
What is your small-cap tobacco (nicotine) stock pick for 2025? (mcap <$2 billion)
– Scandinavian Tobacco: 31%
– Haypp: 30%
– Turning Point Brands: 20%
– Other: 19%
What would be the most consequential product portfolio event of 2025 in tobacco?
– US expansion of Velo Plus: 44%
– IQOS Iluma launch in the US: 36%
– NJOY importation ban: 11%
– International expansion of glo HILO: 9%
What is your one key takeaway from BAT’s FY24 trading update?
– Nothing burger: 44%
– Improvement in financial delivery: 22%
– Improved New Category performance: 18%
– Non-linear progress expected in FY25-26: 16%
How would you rate the (sell-side) analyst coverage of the tobacco industry?
– Mediocre: 53%
– Bottom of the barrel: 27%
– Good: 15%
– Inspiring: 5%
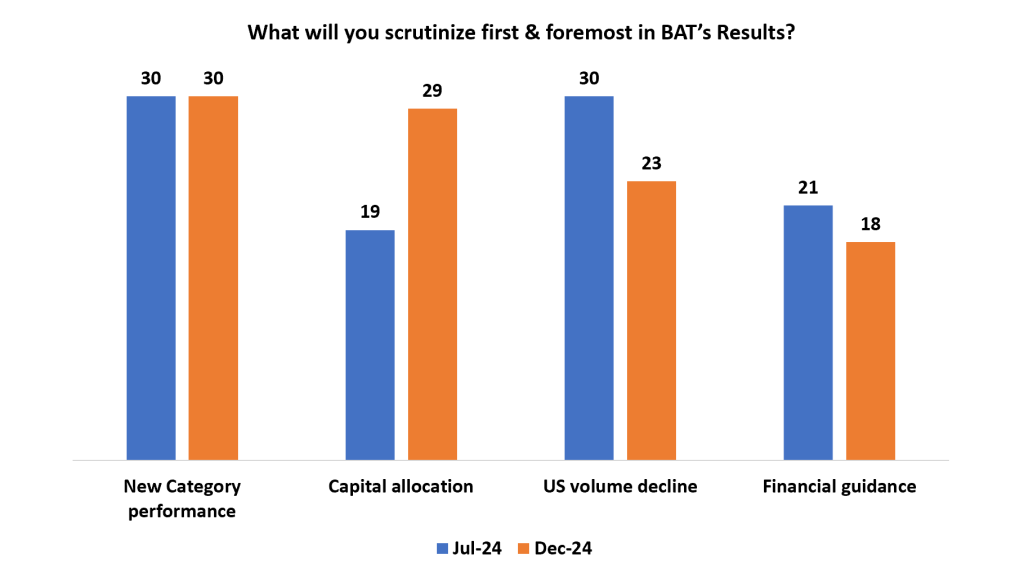
What will you scrutinize first & foremost in BAT’s FY24 Trading Update (December 11, 2024)? (Re-running the July 14, 2024 poll)
– New Category (RRP) performance: 30%
– Capital allocation: Deleveraging & Share buybacks: 29%
– US cigarette volume decline: 23%
– Guidance: acceleration in financial delivery: 18%
Does Philip Morris International (PMI) understate the regulatory, fiscal, and social risks surrounding ZYN and IQOS? (Re-running the March 24, 2024 poll)
– Yes (PMI understates): 51%
– No (PMI provides reasonable, comprehensive, and timely risk assessments): 49%
What is the most important driver of Altria’s outperformance vis-à-vis BAT despite being less diversified?
– US listing: 37%
– Marlboro brand power: 32%
– Large share repurchase program: 25%
– Corporate trustworthiness: 6%
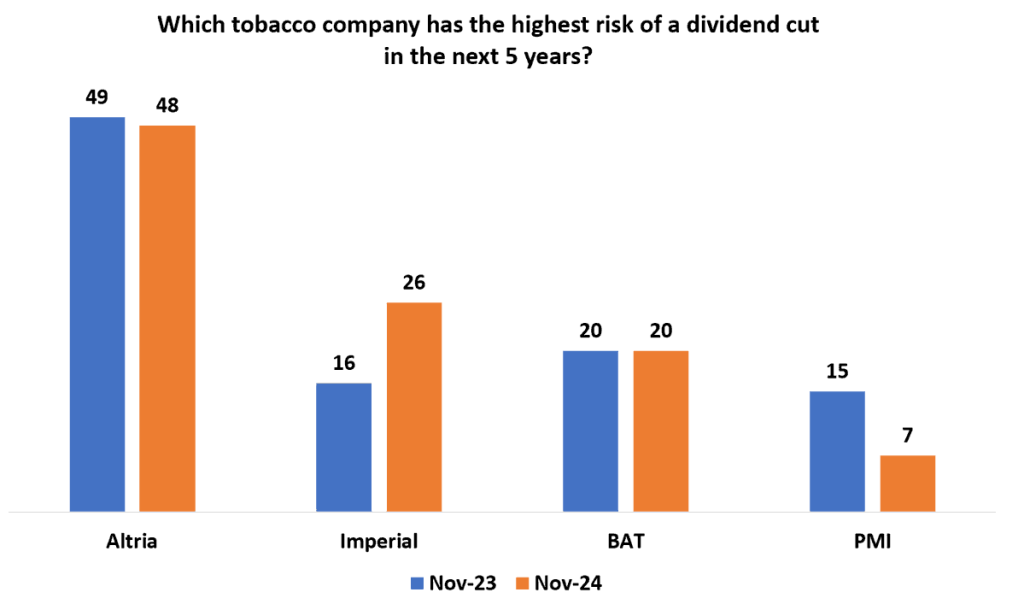
Which tobacco company has the highest risk of dividend cut in the next 5 years? (Re-running the Nov 12, 2023 poll)
– Altria: 48%
– Imperial Brands: 26%
– British American Tobacco: 20%
– Philip Morris International: 7%
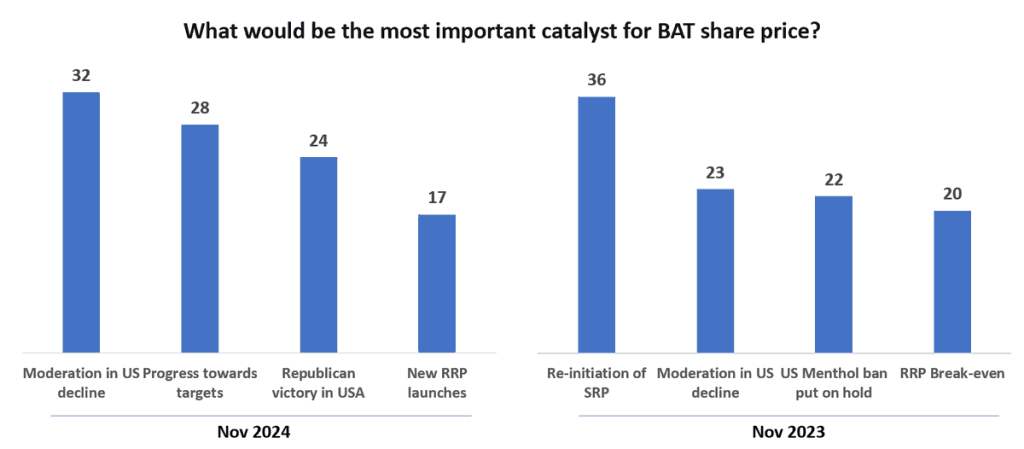
What would be the most important catalyst for BAT share price? (Re-running the Nov 26, 2023 poll)
– Moderation in US cigarette volume decline: 32%
– Progress towards medium-term targets: 28%
– Republican victory in US elections: 24%
– New RRP launches (glo Hilo, Velo Plus): 17%
Despite being businesses of similar size, Philip Morris International / British American Tobacco market cap ratio reaches 2.7x (a new ATH). What is the most important differentiator between the two?
– Progress in transformation: 45%
– Brand portfolio & Geographical mix: 36%
– Circumstantial factors (US listing, media coverage, market irrationality, etc.): 10%
– Quality of earnings & balance sheet: 9%
What is the most important piece of news you heard about BAT this week?
– Canadian settlement: 45%
– Confirmation of the FY24 & medium-term targets: 29%
– Velo Plus (synthetic) launch: 17%
– Glo Hilo launch (IQOS fighter): 9%
What are you most interested to hear about at the British American Tobacco (BAT) Investor Day on October 16, 2024?
– Vuse & Velo growth trajectory: 45%
– US combustibles road map: 28%
– Regulatory risk assessment & engagement: 14%
– Heated tobacco turnaround: 13%
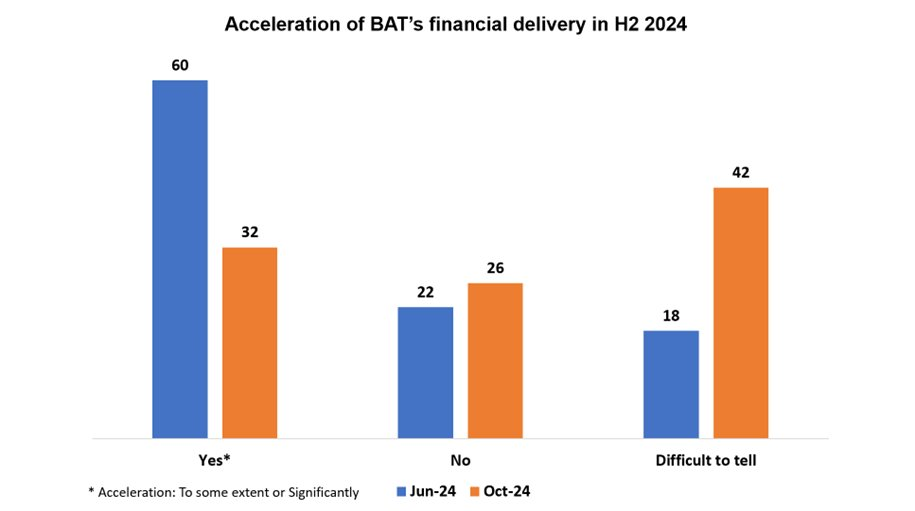
Will British American Tobacco (BAT) deliver the promised acceleration in revenue and profit growth in the second half of 2024? BAT’s latest guidance [July 2024]: “an acceleration in financial delivery to low-single digit revenue and operating profit growth in H2 2024, from -0.8% and -0.9% decline in H1 2024 respectively” (re-running the June 9, 2023 poll)
– Difficult to tell: 42%
– Yes: 32%
– No: 26%